RESULTS of the Property118 Landlord Sentiment Survey: Q3 2026
 admin


Property118
RESULTS of the Property118 Landlord Sentiment Survey: Q3 2026
The survey was sent to around 40,000 Property118 readers and ran from 1 to 8 October 2026. This quarter’s questionnaire was roughly twice as long as before, with 14 new questions, so we are especially grateful to everyone who gave us their time. Your answers give the sector something it badly lacks: a regular, evidence-based record of what landlords actually think and plan to do.
This is our third survey of 2026, which means that for the first time we can look at how sentiment has moved across three quarters rather than two. Three themes stand out this quarter.
-
Confidence is falling. More landlords now expect property values to fall behind inflation, and almost three quarters lack confidence in the outlook for the private rented sector.
-
The exit is already happening. Intentions to sell or leave remain at two thirds, as they were in the summer, and the new questions show that landlords are acting on those intentions, not just talking about them.
-
Policy, not the market, is driving decisions. Asked what is pushing them to sell, and what would keep them in the sector, landlords point overwhelmingly to tax, regulation and the balance of rights between landlord and tenant.
You can read our earlier results here: and .
A Note on Comparisons
In Q2 we said we would rather show an honest gap than a false trend line, and we have kept to that principle. We only compare a result across quarters where the question, the answer options and the time horizon were identical. Where something changed, we show the Q3 result on its own and explain why.
What is comparable across all three quarters (Q1, Q2 and Q3): how portfolios have changed over the last two years, remortgaging plans, the factors that would encourage buying, the preferred structure for future purchases, ownership structure, management approach and gearing.
What is comparable with Q2 only: expectations for property values (first asked in Q2), intentions over the next three years (Q1 asked about the next 12 months), the factors behind selling (Q1 ranked only three factors, not six), the regions where landlords own property, tenant types and property types (Q1 allowed only one answer), and tax residency.
What is new this quarter: 14 questions, covering confidence, recent sales, rents, losses, Making Tax Digital, age, experience and two open questions in landlords’ own words. These set a baseline for future quarters.
Other changes to bear in mind:
-
In Q1 and Q2 every question had to be answered. In Q3 every question could be skipped, so the number answering (the base) differs from question to question. We give the base for each result.
-
The Q1 survey received 2,380 completed responses and the Q2 survey 2,096. Bases for each question are shown in the charts.
-
Respondents are self-selecting Property118 readers, not a random sample of all UK landlords. Readers rightly raised this after our Q2 article. The results describe the views of an engaged, experienced and largely older group of landlords, and should be read in that light.
-
Movements of a point or two between quarters are within normal survey variation at these sample sizes. We describe them as slight or broadly unchanged. Where something has genuinely shifted, we say so.
Confidence and Property Values
More than half of respondents (54.6%) now expect property values to stagnate or fall below inflation over the next three years, up from 48.7% in Q2. The share expecting values to keep pace with inflation has fallen from 43.3% to 38.2%, and only 7.2% expect real growth (8.0% in Q2). Base: 1,629 (Q2: 2,096).
Critical Finding: This is the largest like-for-like movement in the survey this quarter, and it is not simply the result of different landlords taking part. Among the 474 landlords who answered this question in both Q2 and Q3, the pessimistic share rose from 52.7% to 58.2%, a similar shift to the survey as a whole. For a sector whose investment case has always rested on long-term capital growth, a majority now expecting values to fall behind inflation is a significant change in three months.
Comparison note: first asked in Q2 2026, so only two data points are available.
We also asked, for the first time, how confident landlords feel about the outlook for the private rented sector over the next three years. Almost three quarters (73.6%) are not confident: 44.5% are not at all confident and 29.1% not very confident. Only 10.9% are confident (8.9% fairly, 2.0% very), 14.9% are neutral and 0.7% don’t know. Base: 1,534.
Key Insight: With fewer than 1% unsure, this is not a sector undecided about its future; most landlords have already formed a view, and it is a negative one. The gloom is consistent: at least two in three respondents are not confident in every management, gearing and portfolio-size group we examined. Confidence also tracks intentions closely. Of those planning to exit completely, 90.4% are not confident (base 376), against 28.8% of those planning to buy (base 104).
Comparison note: new question this quarter; this result sets the baseline.
Future Intentions and Portfolio Change
Asked what is most likely for them over the next three years, 40.4% of landlords plan to sell one or more properties and a quarter (25.2%) intend to exit the sector completely. Together, 65.6% intend to sell or leave, broadly unchanged from 67.7% in Q2. Only 6.8% expect to buy, down from 9.5%, while the share expecting to stay the same rose from 22.8% to 27.6%. Base: 1,629 (Q2: 2,096).
Key Insight: Two in three landlords still expect to reduce or close their portfolios within three years. The fall in buyers and the rise in those standing still look like a change in who took part rather than a change of heart: among the 473 landlords who answered in both Q2 and Q3, the share planning to sell or exit barely moved (68.5% to 68.9%). The direction of travel remains firmly towards the exit.
Comparison note: Q1 asked about the next 12 months rather than three years, so its results are not directly comparable and are not shown.
Over the last two years, 37.1% of landlords say their portfolio has shrunk because they have been selling, while just 6.5% have grown by buying. The remaining 56.4% say it has stayed roughly the same. Base: 1,642 (Q2: 2,096; Q1: 2,190).
Key Insight: Across three surveys the picture is strikingly stable: for every landlord expanding, almost six are contracting. The share reporting a shrinking portfolio is slightly lower than in Q1 (40.4%) and Q2 (40.2%), but a three-point movement is at the edge of what we can reliably detect and may reflect who responded rather than any slowdown in selling. The share growing has barely moved all year, at around 6%.
Comparison note: identical question in all three quarters, so this is a like-for-like trend.
New this quarter, we asked for the largest number of rental properties each landlord has ever owned at one time. The typical (median) respondent peaked at seven properties; the average of 13.1 is pulled up by a smaller number of larger landlords. Base: 1,495.
Key Insight: Setting these answers against today’s portfolios shows how far respondents have already contracted. More than half (55.9%) now own fewer properties than at their peak, one in five (20.0%) hold half or less of their peak, and together respondents own 26.4% fewer homes than they once did. The exodus is not only an intention; for many landlords it is already well under way.
Comparison note: new question this quarter. The comparison with current portfolios uses 1,441 landlords who answered both questions consistently.
The Exit Is Already Happening
Almost a third of respondents (31.5%) have sold at least one rental property in the last 12 months. Base: 1,502.
Key Insight: This confirms that the selling intentions recorded since the start of the year are being acted upon. Sellers are also markedly less confident than other landlords: 87.3% of those who sold are not confident about the sector’s outlook (base 472), against 66.9% of those who have not sold (base 1,028).
Comparison note: new question this quarter.
We asked those who had sold who bought their properties. The most common buyer was a first-time buyer (35.3%), followed by another private landlord (29.6%) and another owner-occupier (28.8%). Corporate or institutional buyers accounted for 7.6% and sitting tenants 6.1%; 10.9% did not know. Base: 476 sellers; respondents could choose more than one option, so the figures total more than 100%.
Key Insight: Fewer than a third of sellers sold to another private landlord. Most of the properties described here are likely to have left the private rented sector altogether, bought by people who will live in them. Large-scale institutional investors, often presented as the answer to the shortfall in rental homes, bought from fewer than one seller in thirteen.
Comparison note: new question this quarter, asked only of landlords who had sold.
We also asked what happened to the tenants. The most common outcome was that they found another private rental (31.5%). However, almost a quarter of sellers (23.6%) said their tenants had to leave and they do not know where they went, and 13.1% said the tenants were rehoused by the council. In 21.9% of cases the property was already empty, 9.4% of tenants bought the property themselves and 3.9% moved to another of the landlord’s properties; 13.8% did not know. Base: 457 sellers; respondents could choose more than one option.
Key Insight: When landlords sell, a substantial share of tenants leave the private rented sector or move into council housing. One seller in eight reports tenants rehoused by their council, which points to a direct cost of landlord exits for local authorities already under pressure.
Comparison note: new question this quarter, asked only of landlords who had sold.
What Would Bring Buyers Back?
Landlords ranked four possible changes in order of how much they would encourage them to buy more rental property. Results are shown as SurveyMonkey weighted scores: a first-place ranking scores 4 and a last-place ranking scores 1, so a higher score means more important. Base: 1,468 (Q2: 2,096; Q1: 2,190).
| Factor | Q1 2026 | Q2 2026 | Q3 2026 |
|---|---|---|---|
| Reversal of Section 24 | 2.81 | 2.76 | 2.82 |
| Interest rates falling | 2.49 | 2.54 | 2.58 |
| Repeal of the Renters Rights Act | 2.48 | 2.44 | 2.40 |
| Lower Stamp Duty | 2.22 | 2.25 | 2.21 |
Key Insight: For the third survey in a row, reversing Section 24 is the change most likely to persuade landlords to buy again, and the order of all four factors has not changed all year. Falling interest rates have edged up each quarter while repeal of the Renters Rights Act has edged down, although both movements are small. The Act divides opinion more than any other factor: it is the most common first choice (29.9%), yet more than a third of landlords (36.0%) rank it last.
Comparison note: identical question and options in all three quarters, so the scores are directly comparable.
We also asked which other factors influence decisions about buying. The most common was the higher income tax rates on rental income due from April 2027 (59.8%), followed by selective and additional licensing costs (51.3%), landlords’ own age, retirement or health plans (50.2%) and EPC requirements from 2030 (48.0%). Making Tax Digital and compliance admin was cited by 39.1%. Only 32.4% mentioned achievable rents and yields and 19.7% the availability of property at the right price. Just 6.8% said none of these applied. Base: 1,466; respondents could choose more than one option, so the figures total more than 100%.
Key Insight: The buying decision is being shaped far more by tax, regulation and life stage than by the market itself. Market fundamentals, rents and prices, came well behind policy. The one group that still weighs the market is those planning to buy: 56% of them cite achievable rents and 55% availability at the right price (base 100), against 29% and 11% of those planning to exit (base 351).
Comparison note: new question this quarter.
If they were to buy again, just over half of landlords (53.1%) would use a limited company (SPV). 28.9% would buy in their personal name, 11.8% through a Family Investment Company, 4.5% through an ordinary partnership and 1.7% through an LLP. Base: 1,434 (Q2: 2,096; Q1: 2,190).
Key Insight: Preferences have barely moved all year: SPV use is at 53.1%, against 52.6% in Q1 and 53.1% in Q2. The striking point is the gap between how landlords own property today and how they would buy tomorrow. 60.7% currently hold property in their personal name only, yet among those personal-name owners, fewer than half (46.0%) would buy that way again and 40.7% would use an SPV (base 819).
Comparison note: identical question in all three quarters.
What Is Pushing Landlords to Sell?
Landlords ranked six factors in their decision to sell. A first-place ranking scores 6 and last place 1, so a higher score means more important. Base: 1,499 (Q2: 2,096).
| Factor | Q2 2026 | Q3 2026 |
|---|---|---|
| Lower Capital Gains Tax | 4.13 | 4.09 |
| Higher interest rates | 4.14 | 4.09 |
| Renters Rights Act | 3.74 | 3.77 |
| New EPC rules | 3.58 | 3.51 |
| Tenants moving out | 2.72 | 2.87 |
| Death of a spouse or partner | 2.69 | 2.66 |
Key Insight: Lower Capital Gains Tax and higher interest rates are now joint first, and the order of all six factors is the same as in Q2, which suggests these are settled concerns rather than reactions to the news cycle. The Renters Rights Act matters most to those leaving: among landlords planning to exit completely (base 379), and among those who have sold in the last 12 months (base 458), it moves into first place.
Comparison note: Q1 asked landlords to rank only three factors, so its scores are on a different scale and cannot be compared. The option labelled “Renters Reform Act” in Q2 appears as “Renters Rights Act” in Q3 and is treated as the same item.
Beyond the ranked factors, we asked what else influences decisions to sell. Two factors were each cited by six in ten landlords: difficulty removing tenants who do not pay or cause damage (59.8%) and the higher income tax rates on rental income from April 2027 (59.7%). More than half (53.4%) named selective and additional licensing and council enforcement, and 46.2% their own age, retirement or health. Section 24 was cited by 40.2%, Making Tax Digital by 37.8%, rent no longer covering costs by 37.1% and proposed land value or property taxes by 36.5%. By contrast, just 5.2% said good sale prices were a factor, and only 2.2% said none of these applied. Base: 1,486; respondents could choose more than one option.
Key Insight: Decisions to sell rarely rest on a single cause: landlords chose more than four factors each on average. Almost all of the most common reasons are matters of government policy, and very few landlords are selling because prices are attractive. This is not a sector cashing in at the top of the market; it is one responding to the rules it operates under.
Comparison note: new question this quarter.
The Money: Losses, Rents and Refinancing
For the first time we asked how much of each landlord’s portfolio is making a loss after all costs and tax. Almost two thirds (62.9%) say none of it is. However, more than a quarter (26.2%) say at least part of their portfolio is loss-making: 12.7% up to a quarter, 4.9% a quarter to a half, 3.7% more than half, and 4.9% all of it. A further 7.6% did not know or preferred not to say, and 3.3% said the question did not apply. Base: 1,485.
Key Insight: One landlord in eight (13.5%) says a quarter or more of their portfolio is running at a loss, and nearly one in twenty say every property is. Losses are closely linked to borrowing: 12.5% of mortgage-free landlords report any loss (base 503), rising to 46.9% of those at 71% loan to value or more (base 128). Losses are also linked to leaving: among those whose entire portfolio is loss-making (base 72), more than half (54.2%) plan to exit completely.
Comparison note: new question this quarter; this sets a baseline to track.
Over the last 12 months, more than a quarter of landlords (26.4%) have not increased rents at all, and a further 22.6% have raised them by 3% or less on average. The most common band was over 3% up to 5% (27.2%). Only 20.9% raised rents by more than 5%, and just 4.8% by more than 10%. Base: 1,502.
Key Insight: Landlords are not uniformly pushing rents up. Almost half have held rents or raised them by 3% or less across their portfolios. Smaller landlords have been the most restrained: 37.8% of single-property landlords made no increase (base 172), against 15.0% of those with 21 or more properties (base 173).
Comparison note: new question this quarter. This is a self-reported portfolio average, not a measure of rents on new lettings.
Looking ahead 12 months, the largest group (39.3%) plan to raise rents in line with inflation and a further 10.0% below inflation. Fewer than one in five (18.6%) expect to go above inflation. Almost a quarter (22.8%) plan to hold rents where they are, and 0.9% expect to reduce them; 5.4% don’t know and 3.0% said the question did not apply. Base: 1,497.
Key Insight: Set against the cost pressures and losses reported elsewhere in this survey, landlords appear to be passing on rising costs cautiously rather than seeking real-terms gains.
Comparison note: new question this quarter.
Around a third of landlords (33.8%) expect to remortgage at least one rental property in the next 12 months, almost identical to Q2 (34.2%) and slightly above Q1 (31.1%). Base: 1,614 (Q2: 2,096; Q1: 2,190).
Key Insight: The headline has held steady all year, but it includes the third of respondents with no mortgages at all. Among landlords who do borrow, half (50.9%) now expect to refinance within a year, up from 48.2% in Q2 and 43.8% in Q1 (bases 959, 1,392 and 1,442). For many geared landlords, the next fixed-rate expiry is close, and the terms on offer will shape whether they hold, sell or exit.
Comparison note: identical question in all three quarters.
Making Tax Digital
We asked how prepared landlords feel for Making Tax Digital (MTD) for Income Tax. 19.3% say they are fully prepared and compliant and 17.8% are getting there. A quarter (25.6%) are aware of MTD but have not started, and 5.0% are not aware of the details. One in five (20.9%) say they are not yet required to use it, and 11.4% say it does not apply to them. Base: 1,496.
Key Insight: Among landlords who did not place themselves outside its scope, almost half (45.2%) have yet to start or are unclear on the detail. Larger landlords are much further ahead: around half of those with six or more properties are prepared or getting there, against 14.5% of those with one property or none. Many smaller landlords will come into scope over the next two years as the income threshold falls.
Comparison note: new question this quarter.
In Landlords’ Own Words
We asked landlords to describe, in their own words, the single biggest issue they face right now. 1,395 did so. We grouped the answers into themes; many answers mention more than one, so the figures total more than 100%. Regulation, compliance and red tape was the most common theme (30.0%), followed by tax including Section 24 (22.4%), the government’s attitude towards landlords (22.1%), the Renters’ Rights Act, possession and tenant rights (19.1%) and rising costs, repairs and maintenance (17.0%). Interest rates and mortgages (7.5%), problem tenants and arrears (6.7%) and property values (4.2%) were mentioned far less often.
Key Insight: More than three quarters (78.1%) named an issue driven by government policy, whether regulation, tax, the Renters’ Rights Act, EPC rules, licensing or MTD. Day-to-day market pressures came a long way behind. A recurring thread was not any single rule but the sheer volume and pace of change.
Comparison note: new question this quarter.
We also asked what, if anything, would make landlords want to stay in the sector or expand. Around a quarter of the 1,314 who answered (25.4%) said nothing would, or that it was already too late. Most of the rest pointed to government: less regulation, licensing and admin (20.1%), lower or fairer tax on rental income (16.2%), fair treatment and respect for landlords (13.9%), changes to the Renters’ Rights Act or the return of Section 21 (13.7%) and reversing Section 24 (12.6%). Better returns were mentioned by 13.5% and lower interest rates by only 5.3%.
Key Insight: Almost six in ten (58.7%) named a specific change in policy or government that would keep them in the sector. Even among landlords planning to exit completely, six in ten named something that could change their mind (base 327). That is the most hopeful finding in this survey: much of the exodus is a response to policy, and policy can change.
Comparison note: new question this quarter.
Who Are the UK’s Landlords?
The typical (median) respondent owns five rental properties, the same as in Q2 and up from four in Q1. The average (mean) is 11.7 (Q2: 11.8), pulled up by a small number of large portfolios: three respondents chose the scale’s maximum of 500 or more, and the largest 1% of respondents hold about a fifth (20.8%) of all the properties reported. Together, respondents own at least 17,912 rental properties. Base: 1,531.
Key Insight: Most respondents are small to medium landlords, but a handful of large portfolios have an outsized effect on averages, which is why we lead with the median.
Comparison note: Q2 and Q3 used the same slider, so the median and mean are comparable. Q1 used a free-text box, so only the median is compared. Because Q3 questions could be skipped, the total number of properties is not comparable with earlier quarters.
Four in five respondents (81.0%) are aged 55 or over, and almost half (46.0%) are 65 or over. Just 3.7% are under 45. The largest groups are 55 to 64 (35.0%) and 65 to 74 (33.0%), with 13.0% aged 75 or over and 12.9% aged 45 to 54. Base: 1,496.
Key Insight: Many of the landlords in this survey are planning for retirement, succession or simply stepping back, and their decisions to sell will be shaped by age as much as by policy. Buying falls steeply with age: 18.6% of those under 55 plan to buy (base 247), against 4.0% of those 55 and over (base 1,210).
Comparison note: age was not asked in Q2, and Q1 used different age bands, so the results cannot be compared directly.
More than half of respondents (57.3%) have been landlords for over 20 years, and almost a quarter (23.9%) for more than 30. Only one in ten (10.7%) started within the last decade, and just 2.5% in the last five years. Base: 1,497.
Key Insight: The views in this survey come overwhelmingly from people who have seen several housing cycles, tax regimes and rounds of reform. When landlords with this experience say they intend to sell, it is not inexperience talking.
Comparison note: new question this quarter.
60.7% of respondents own property in their personal name only, 15.5% through a company and 13.9% through a mix of structures. 6.7% use a partnership and 1.5% an LLP; 1.6% preferred not to say. Base: 1,551 (Q2: 2,096; Q1: 2,190).
Key Insight: Personal ownership has edged down from 62.4% in Q1 to 60.7%, while company and mixed ownership have edged up, but each movement is small and the overall picture is broadly unchanged across the year.
Comparison note: identical question in all three quarters.
39.0% of landlords manage their properties entirely themselves, 26.1% use an agent for full management, 18.8% use a mixture and 15.6% use an agent for letting only. Base: 1,545 (Q2: 2,096; Q1: 2,190).
Key Insight: Management approach is unchanged across all three quarters, with every movement under two points. Self-management is, if anything, most common among the largest landlords. Sentiment barely differs by management approach: the share planning to sell or exit sits between 63.9% and 67.0% across the four main groups.
Comparison note: identical question in all three quarters.
A third of respondents (33.7%) have no mortgages. Among the rest, average gearing is spread widely: 13.5% under 30% loan to value, 16.0% at 31% to 50%, 13.1% at 51% to 60%, 10.9% at 61% to 70%, 7.1% at 71% to 75% and 1.7% at 76% or more; 4.0% preferred not to say. Base: 1,539 (Q2: 2,096; Q1: 2,190).
Key Insight: The share with no mortgages has risen from 29.3% in Q2 to 33.7%. Because gearing is a characteristic of who responds rather than an opinion, this mainly reflects a different mix of landlords taking part this quarter; among landlords who answered both surveys, the change was much smaller. It should not be read as landlords paying down debt.
Comparison note: identical question in all three quarters (Q1: 30.3% no mortgages).
77.4% of landlords let to working tenants, 18.6% to a mixture, 15.0% to tenants receiving benefits and 7.9% to students. Base: 1,551; respondents could choose more than one option, so the figures total more than 100%.
Key Insight: The mix of tenants housed by respondents is almost identical to Q2, with every movement within normal variation. These are the households most directly affected if landlords follow through on their intentions to sell or exit.
Comparison note: Q1 asked for a single tenant type, so it is not comparable and is not shown. Our Q2 article compared tenant types with Q1; the apparent rises in benefit and student lets then were mainly caused by that change of question format.
Houses are let by 68.9% of respondents and flats by 59.0%. HMOs (14.4%), commercial property (8.2%) and bungalows (7.1%) are each held by a minority. Base: 1,552; respondents could choose more than one option.
Key Insight: The make-up of portfolios is almost unchanged since Q2. One clear difference stands out within it: a third (33.2%) of flats-only landlords cite service charges, ground rents or leasehold problems as a reason to sell (base 352), against 5.0% of houses-only landlords (base 501).
Comparison note: Q1 asked for a single answer and grouped houses, flats and bungalows together, so property types are compared with Q2 only.
London (24.0%) and the South East (23.3%) remain the most common places to own rental property, followed by the South West (15.6%) and the North West (14.6%). Base: 1,560; respondents could choose more than one region, so the figures total more than 100%.
Key Insight: No region moved by more than two points since Q2. That stability matters: shifts elsewhere in this survey, such as the rise in pessimism about property values, are not explained by a change in where respondents own property. Intentions to sell or exit vary only modestly by region, which suggests the pressure is national rather than regional.
Comparison note: Q1 asked for a single region, so it is compared with Q2 only.
95.1% of respondents are UK resident for tax purposes and 4.9% are not. Base: 1,537 (Q2: 95.8%, base 2,096).
Key Insight: Non-resident landlords remain a small but distinct group, broadly unchanged on last quarter.
Comparison note: not asked in Q1. In Q2 respondents could tick both answers (four did); in Q3 only one answer was allowed.
What Does This All Mean?
Three surveys into 2026, a consistent picture is emerging, and this quarter’s new questions add depth to it.
The intention to leave is steady, and it is being acted on. Since the spring, around two thirds of respondents have said they expect to sell some or all of their portfolio. That figure has not moved between Q2 and Q3, even among the same landlords answering twice. What is new is the evidence that intentions are turning into action: almost a third have sold in the last year, more than half now own fewer properties than at their peak, and when they sell, most of the buyers they describe are people who will live in the home rather than other landlords.
Confidence is weakening. The clearest change this quarter is in expectations for property values, with a majority now expecting them to fall behind inflation. Combined with almost three quarters lacking confidence in the sector’s outlook, this suggests the mood among landlords has darkened since the summer, not just held steady.
The drivers are policy, not the market. Whether asked about selling, buying or the single biggest issue they face, landlords point to tax, regulation, licensing and the Renters’ Rights Act far more than to prices, rents or demand. Section 24 has topped the list of reasons to buy again in every survey this year.
Not everyone has given up. Around six in ten landlords, including many who plan to exit, named a policy change that would keep them in the sector. Most are not chasing large rent rises, and a quarter made no increase at all last year. The sector’s future depends heavily on decisions still to be made in Westminster.
These results come from engaged Property118 readers, most of them experienced landlords aged 55 or over, not from a random sample of all UK landlords. But with over 1,600 responses this quarter and consistent findings across three surveys, they offer a clear, regular and evidence-based view of how landlords are responding to the policy environment around them.
Why Your Constructive Feedback Matters
375 of you took the time to tell us how we could improve future surveys, and we have read every suggestion. More than a quarter (26.7%) said the survey works well as it is. Only 3.5% asked for it to be shorter, even though this quarter’s questionnaire took about twice as long. One in ten (10.1%) pointed to missing answer options, and one in five (21.3%) suggested new topics, led by questions about landlords’ circumstances and motives, tax and costs, and arrears and possession. Respondents could raise more than one point, so the figures total more than 100%.
Two specific issues you raised will be fixed for Q4: the question about what happened to tenants after a sale will include an option for tenants who stayed in place, and the question about your largest-ever portfolio will no longer stop at 100.
Please tell us what you think in the comments below. Which results surprised you? What should we ask next quarter? Your comments shaped the changes we made this quarter, including more detail on how we compare results and the new questions on rents, losses and Making Tax Digital.
Look out for the Q4 2026 survey at the end of December. The more landlords who take part, the stronger the evidence we can put in front of journalists and policymakers. If you know a landlord who is not yet a Property118 reader, please share this article with them.
Over the coming weeks we will publish follow-up articles exploring individual results in more depth, including how intentions differ by age, portfolio size and gearing.
The post RESULTS of the Property118 Landlord Sentiment Survey: Q3 2026 appeared first on Property118.
View Full Article: RESULTS of the Property118 Landlord Sentiment Survey: Q3 2026
Government launches Awaab’s Law consultation for private rented sector
Property118
Government launches Awaab’s Law consultation for private rented sector
The government is seeking views on extending Awaab’s Law to the private rented sector (PRS), including how the rules should work and when they should come into force.
Private renters, landlords, and charities are being invited to share their views to help shape the new requirements.
Awaab’s Law is already in force for social housing landlords to fix damp and mould in strict timeframes.
Fix severe damp and mould
The government says the consultation will look at how Awaab’s Law should be introduced for private renters, as well as what other types of accommodation could benefit from the protections in future, including temporary accommodation for homeless people and families, and accommodation for young people leaving care.
The government claim Awaab’s Law will benefit more than five million households and force landlords to quickly fix dangers like severe damp and mould.
Housing Minister Matthew Pennycook said: “Irrespective of tenure, all renters have the right to live in a safe and decent home and have complaints responded to in a timely manner.
“Awaab’s Law is already helping to drive up standards in the social housing sector. We’re now moving to extend it to private landlords so that England’s 11 million private renters can enjoy the same protections.”
The government says the consultation will close on 18 December and an options assessment on the potential impacts of introducing Awaab’s Law to the private rented sector will be published alongside the consultation.
Take action on serious hazards
The government claims around one in 10 privately rented homes contain a category one hazard.
Under the Renters’ Rights Act, councils can issue landlords with financial penalties of up to £7,000 where they fail to take reasonably practicable steps to deal with these serious hazards.
The government says extending Awaab’s Law to the private rented sector would go further, requiring landlords to take action on serious hazards within set timeframes.
At the Labour Party conference, Prime Minister Andy Burnham also pledged to crack down on poor-quality private rented homes, with government plans allowing councils to take control of properties left empty for six months, down from the current two-year threshold.
Industry reaction
Ben Beadle, chief executive of the National Residential Landlords Association (NRLA), said: “The death of Awaab Ishak due to dangerous conditions in a social rented home was an unimaginable tragedy that should never have happened. The law in his name must ensure that no landlord, regardless of sector or size, can expect to get away with letting sub-standard, dangerous housing.
“Today’s consultation rightly recognises that there are important differences between the private and social rented sectors, and for the law to be effective, it must be designed and applied appropriately.
“However, changing the law means nothing unless it is properly enforced without exception or favour, and irrespective of tenure. For too long bad actors across the rental sectors have been able to ignore standards and regulations already in place because the chance of being held to account is too remote to cause concern. This must change.
“Alongside consulting on these measures, the government needs to deliver on its aspirations and put their words into action. All good landlords are united in the desire to root out those rogue and criminal operators who put tenants at risk and undermine the reputation of the compliant majority. More regulation alone will not achieve that.”
Timothy Douglas, head of policy and campaigns at Propertymark, said: “Everyone should have the right to live in a safe, decent home, and there can be no excuse for serious hazards being left to put tenants’ health and lives at risk. Awaab’s Law is a significant reminder of the devastating consequences when dangerous housing conditions are not addressed, and extending these protections to private renters and other vulnerable households is an important step.
“The consultation now needs to ensure the law works effectively in practice. Early identification, clear reporting routes and timely access to competent contractors will be vital, alongside properly diagnosing the underlying cause of damp and mould rather than relying on short-term fixes.
“Responsible landlords and agents want tenants to live in safe homes, and clear, workable requirements will help deliver that. Getting the detail right will be critical to ensuring these protections translate into faster action and, ultimately, safer homes.”
Holly Williamson, chief executive of Generation Rent, said: “Homes are the foundations of our lives. But too many renters live in homes that are harmful to our health and often wait months for landlords to act on issues.
“We’re pleased to see the government moving forward with bringing in Awaab’s Law. It must be put in action as soon as possible to make sure every renter can live in a good quality home.”
Clara Collingwood, director of the Renters’ Reform Coalition, said: “A home should be a place of safety, and nobody in the UK should have to live in a home that is making them ill or putting their lives at risk, regardless of whether they rent their home from the council or from private landlords.
“We welcome the government’s consultation, and hope that the public responds with urgency, every additional day in which a child like Awaab Ishak’s life continues to be at risk should weigh heavily on us.”
The post Government launches Awaab’s Law consultation for private rented sector appeared first on Property118.
View Full Article: Government launches Awaab’s Law consultation for private rented sector
Government fails to explain how landlord privacy will be protected under PRS Database
Property118
Government fails to explain how landlord privacy will be protected under PRS Database
The government has reassured landlords it will safeguard their privacy in the PRS Database, but has provided no details on how.
Property118 contacted the government after concerns were raised by landlords about privacy and how their data will be handled under the PRS Database.
Under the PRS Database, landlords will be required to provide information about their properties, including the address, number of residents and bedrooms, as well as copies of gas, electricity and EPC documents.
Safeguard the privacy of landlords
The government told Property118 that data will be handled in line with data protection legislation, with further details to be announced in due course.
A Ministry of Housing spokesperson told us: “The new database will help tenants make vital and informed decisions when entering into a tenancy agreement.
“However, we will ensure we safeguard the privacy of landlords, and any data shared will be in line with data protection legislation.”
The government adds that under future legislation, landlords will also be required to register any unoccupied properties before marketing them for let. Letting agents and landlords will need to include registration numbers on adverts.
Transparency must be balanced with landlords’ privacy
The PRS Database will launch regionally, with the first rollout set to begin in the West Midlands in December.
Industry bodies have urged the government to clarify what information will be publicly available on the PRS Database ahead of its launch.
Propertymark says a redacted version of a landlord’s address should be made available to help protect landlords’ privacy.
Timothy Douglas, the head of policy and campaigns at Propertymark, told Property118: “We support the principle of a national PRS Database, but transparency must be balanced with landlords’ privacy and personal safety.
“When it comes to databases, Propertymark has previously supported making a redacted version of a landlord’s address available, rather than publishing a full personal address. That distinction remains important as information may need to be held for regulatory and enforcement purposes without being made publicly searchable.
“The UK government should therefore clarify exactly what information will be publicly accessible and what safeguards will protect landlords from unnecessary privacy and security risks. Effective enforcement and transparency should not come at the expense of personal safety.”
Landlords need urgent clarity
The National Residential Landlords Association (NRLA) also echoed Propertymark’s stance and urged the government to give more clarity on the information accessible on the database.
A spokesperson for the NRLA said: “At the moment it’s unclear exactly what the architecture underpinning the PRS database is set to look like and how the new system will work in practice.
“Given that the roll-out of the PRS database is set to start from December, landlords urgently need clarity on these points.
“When it comes to data privacy, we believe that all safeguarding processes must be followed rigorously considering the vast quantities of data the new system is likely to possess.”
Cost the PRS £327 million a year
The NRLA has also warned that England’s planned landlord database could cost the private rented sector at least £327 million a year, with tenants ultimately footing the bill.
Landlords will have to pay a £65 annual fee per property to register on the PRS Database.
The NRLA spokesperson added: “More broadly, the ‘year one’ cost implications per property for landlords across the sector are likely to be considerable. The position of those landlords already complying with local licensing schemes under the new regime isn’t clear either.
“Landlords need to have sufficient time to make the transition to the new system, so the government must take all the steps it can to allay landlords’ concerns.”
The database fee will be charged alongside licensing fees in areas where councils operate their own schemes – which can reach as much as £2,300 per property, as charged by Arun District Council.
Raise rents to cover cost
Landlords are already factoring in the additional costs, with some warning they may need to raise rents to cover them. One landlord has said he will need to charge an extra £6 a month to cover the new database fee.
Mick Roberts, one of Nottingham’s largest landlords providing homes to benefit tenants, wrote in an article for Property118 that councils already hold much of the information required for the database through selective licensing schemes.
He wrote: “The government has just brought in yet another charge, a £65-a-year fee for each property to be registered on the PRS Database. That means you’ll need a rent increase of around £6 per month just to cover it.
“All the information needed for the property database, the council already has for selective licensing. The council already charges around £1,000 every five years for this, which works out at £200 per year, or another £20 per month in rent.”
The government has also warned that landlords who let or advertise a property without first registering it on the database could face a civil penalty of up to £7,000. Those who provide fraudulent information to the database could face a fine of up to £40,000.
More questions than answers
With the first rollout of the PRS Database only weeks away, landlords are being asked to pay for a system while concerns remain over privacy, costs and how the database will work in practice.
For now, many questions remain unanswered, and whether the government can deliver greater transparency for tenants while adequately protecting landlords’ privacy remains to be seen.
The post Government fails to explain how landlord privacy will be protected under PRS Database appeared first on Property118.
View Full Article: Government fails to explain how landlord privacy will be protected under PRS Database
Clearsprings’ asylum accommodation profits: are landlords getting a fair deal?
Property118
Clearsprings’ asylum accommodation profits: are landlords getting a fair deal?
MPs have questioned the profits, reinvestment and group payments associated with Clearsprings. What do the landlords supplying its properties make of the arrangement, and does their experience match the promise of guaranteed rent and less hassle?
Guaranteed rent, a long contract and less day-to-day management would appeal to plenty of landlords. Add a business supplying accommodation to the Home Office and the proposition deserves a proper look, especially for owners who want dependable income without managing every tenancy themselves.
After watching MPs question Clearsprings Ready Homes, I want to hear from the landlords who supply the homes. There is plenty of discussion about the money going through the asylum accommodation system, but readers with first-hand experience can tell us something the headline figures cannot: how the arrangement works when it is your property, your capital and your contract.
The questions put to Clearsprings
The short video bringing these questions together combines separate exchanges from the Home Affairs Committee hearing on 13 May 2025. The witness is managing director Steve Lakey, rather than Graham King, whose wealth is discussed.
In the official parliamentary transcript, Lakey puts Clearsprings’ average profit margin at approximately 6.9%, subject to contractual profit sharing. Later, referring to money held in the group bank account, he speaks of approximately £300 million in profits over five years, with most still available for reinvestment.
MP Chris Murray also raises reports of £17 million paid to an offshore consultancy. Lakey confirms that Bespoke Strategy Solutions, a UAE company owned by King, invoices Clearsprings Group for services. He disputes the stated amount and says the payments come from the group, rather than Ready Homes, and are excluded from the Home Office profit-share calculation. The exchange raises questions about the payments; it does not establish wrongdoing.
Profit is part of running a business, and large contracts involve substantial costs and responsibilities. The commercial questions are whether the customer receives value for money and whether the people supplying the service are rewarded fairly for the work, assets and risks they contribute.
What the £41,000 figure means
The figure that first caught my attention was £41,000 per asylum seeker per year. The underlying IPPR research published in October 2024 estimated the average cost of housing and supporting an asylum seeker across the system in 2023/24. It was not a published rental rate payable to a landlord or a tariff specific to Clearsprings.
Hotels and self-catering homes have very different operating costs. Parliamentary scrutiny has also examined whether the contracts give providers sufficient incentive to replace expensive hotels with cheaper accommodation. The Home Affairs Committee’s subsequent report concluded that the arrangements could reward providers more for hotel use than for procuring other suitable housing.
That leaves a question landlords will understand immediately: if ordinary rented homes can help reduce the public bill, what terms make supplying those homes worthwhile? Comparing a hotel’s total service cost with the rent on a house will not answer it.
The later evidence matters too
There have been developments since the hearing. The Home Office’s 2026–27 estimates memorandum says that, by 4 November 2025, Clearsprings had returned the full £33 million identified for profit sharing, through arrangements involving credit notes. The earlier discussion about money awaiting repayment should therefore be read alongside that update.
Clearsprings also submitted further written evidence in June 2025, saying it had recently invested approximately £7 million in specialist accommodation for people with significant medical needs and was purchasing dispersal properties. Those are relevant parts of the company’s account of how it uses its profits.
What does the landlord receive?
Clearsprings’ landlord recruitment page promotes “Zero Hassle”, “Long Term Contracts” and “Guaranteed Rent”. Those promises will interest owners who want to reduce their workload, but their value becomes clear through the contract and the experience of living with it.
In its parliamentary evidence, Clearsprings describes procurement taking up to three months, insurance costs deterring some owners, compliance works and competition from other housing providers. It also says it seeks to keep property rates low to provide value for the Home Office and avoid pushing up local rents. Landlords, understandably, have their own costs and returns to consider.
A lower headline rent may be perfectly acceptable if income is dependable and genuine management responsibilities are removed. Equally, a long agreement can become expensive if preparation costs, repairs or handback obligations are greater than the owner expected. The rent needs to be assessed alongside everything the landlord still has to fund and do.
Would you sign again?
If you have supplied accommodation to Clearsprings Ready Homes, please share your experience in the comments. Start by saying whether your contract was directly with Clearsprings or with an agent or subcontractor, and roughly when the arrangement began. That will help readers understand whose service you are describing.
Was the rent paid when expected?
What work did you have to complete before payments began, and how were repairs, inspections and access handled afterwards?
If the arrangement has ended, was the property returned on time and in the agreed condition, and were any outstanding costs settled fairly?
Good experiences are just as useful as difficult ones. If it has provided dependable income and more freedom, please explain what made it work. If something went wrong, describe what happened, how the company responded and whether it was resolved, without identifying residents or publishing property addresses.
Most of all, would you sign again, and what would you negotiate differently?
Your answer could help another landlord make a better decision before committing a property for several years.
The post Clearsprings’ asylum accommodation profits: are landlords getting a fair deal? appeared first on Property118.
View Full Article: Clearsprings’ asylum accommodation profits: are landlords getting a fair deal?
Housing benefit changes will help thousands claims government
Property118
Housing benefit changes will help thousands claims government
Prime Minister Andy Burnham has claimed a “common-sense change” will leave those in supported housing and temporary accommodation “better off”.
New rules coming into force this week mean more than 325,000 residents in supported housing and temporary accommodation will no longer face a drop in income when they increase their working hours.
Under the previous system, people living in supported housing and temporary accommodation often receive help with their day-to-day living costs through Universal Credit, while support for their rent was paid separately through Housing Benefit.
A cliff edge
The two systems had different rules on how much someone could earn before their benefits were reduced, with Housing Benefit less generous than Universal Credit.
That meant some residents moving into work or taking on more hours could see their Housing Benefit cut faster, leaving them worse off despite earning more.
The government says this created a “cliff edge”, with the risk of losing housing support discouraging some people from taking on more work. The new regulations change how housing benefit is calculated, bringing it in line with Universal Credit.
Prime Minister Andy Burnham said: “People should never have to choose between keeping a roof over their head or being able to work. But the system has been rigged against some of the very people trying their hardest to get on, particularly young people starting out, who are being left worse off for earning more.
“We’re putting that right through a common-sense change that will help people keep more of what they earn. This is what progressive welfare reform looks like: helping people into work and giving families the security and breathing space they need to get on. That’s how we make Britain better off.”
End homelessness for good
Homelessness minister, Florence Eshalomi, added: “We’re investing over £4 billion to end homelessness for good, and employment is an important step in many people’s recovery. This is a crucial intervention that supports this mission, helping people into secure work or increase their earnings from work, in turn building lasting independence.
“We’ll continue to support people in temporary accommodation by ensuring that safe, stable placements are available to all who need them, tackling the unlawful use of B&Bs for families and improving access to vital support services.”
The government says new earned income disregards are being introduced for working-age people in supported housing and temporary accommodation. This means more of their earnings will be ignored when housing benefit is calculated, allowing support to taper off more gradually as their income rises.
For example, a single claimant aged 25 or over will have £77.73 of their weekly earnings disregarded, while a couple with at least one person aged 25 or over will have £119.70 disregarded. These amounts will be increased each year in line with changes to Universal Credit.
The post Housing benefit changes will help thousands claims government appeared first on Property118.
View Full Article: Housing benefit changes will help thousands claims government
The government thinks a landlord’s house is more dangerous than a car with no MOT
Property118
The government thinks a landlord’s house is more dangerous than a car with no MOT
Police interceptors wouldn’t fine me £7,000 for no MOT, so why would the government fine me for having an MOT?
Yes, I can have the boiler certificate, EPC, EICR, all perfectly legal, but woe betide me if I make an admin error and forget to send it to the government, because that could land me a £7,000 fine.
A stationary house is 70 times more risky than a dangerous car with no MOT. That’s what the government seems to be saying.
We all know that cars with no MOT can be dangerous and can kill someone. That’s why, when you MOT your car, the result automatically goes onto a database. The police can check it instantly while they’re driving behind you.
And rightly so, if you’re driving a car without an MOT, you can be fined £100.
Yet apparently houses are more dangerous. Why? Because the government says so.
Retrospective rules are overtaking you
If they think a £7,000 fine is justified for not putting your boiler certificate on the database, even though you have actually got the certificate, then surely a car with no MOT should be fined more than £7,000, shouldn’t it?
You can have the boiler certificate. You can have everything legal. You’ve just messed up on your admin because all these new retrospective rules are overtaking you.
If this is so serious that it justifies a £7,000 fine, why aren’t the boiler certificates put onto a database automatically?
Now, with EPCs, we all know they do automatically get put onto the government website.
Those who have already uploaded these documents to councils that have selective licensing schemes, why do they have to do the same again?
Because it’s the same councils that have been put in charge of administering the database scheme, and the same councils that will be fining landlords for not uploading the certificate.
Constant threats from government
Do the government not get what they are doing with these constant threats?
Landlords are packing up. We’re not taking risky, vulnerable tenants. We’re neglecting the house and the tenant because the government and councils are taking our time and funds that would have gone on the house.
Do the government not get that this is an extra £6 a month on top of the rent?
And before you say, “well, it’s only a bit more admin,” read all the changes landlords have faced since 2015 and then tell me the government aren’t beating the landlord down and why rents are so expensive. I’ve written more about this here.
The rogue landlords are still going to ignore this like they have done with selective licensing.
Article by Mick Roberts, one of Nottingham’s largest landlords to house benefit tenants.
The post The government thinks a landlord’s house is more dangerous than a car with no MOT appeared first on Property118.
View Full Article: The government thinks a landlord’s house is more dangerous than a car with no MOT
Landlords urged to prepare for Making Tax Digital 2027
Property118
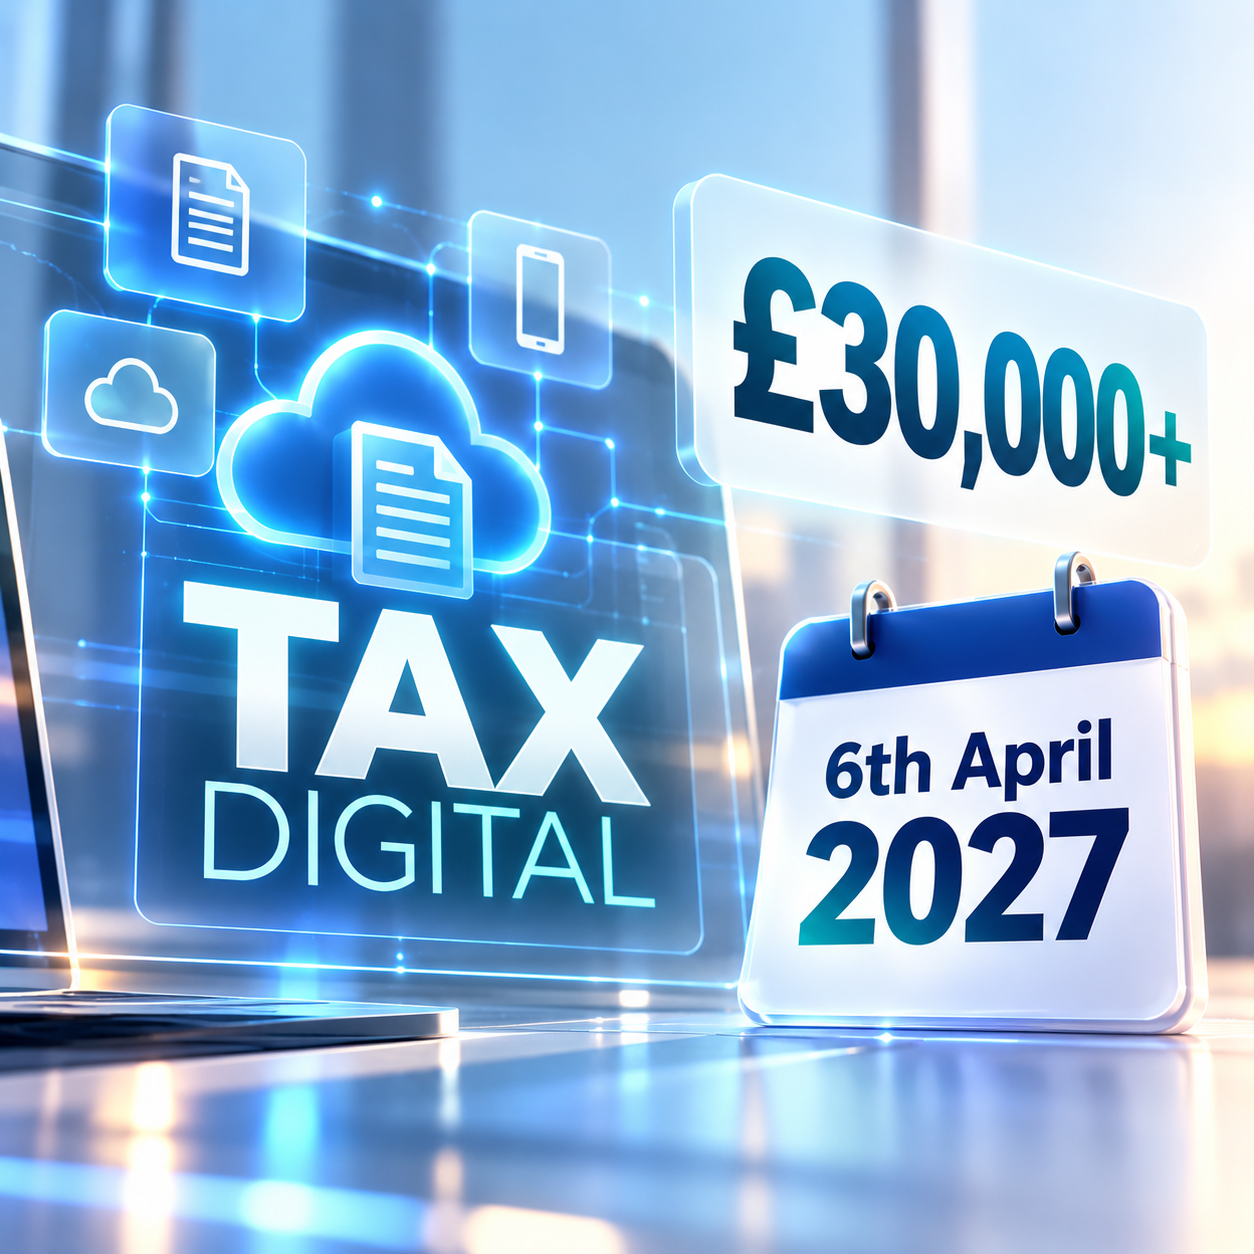
Landlords urged to prepare for Making Tax Digital 2027
Landlords with gross income above £30,000 have six months to prepare for Making Tax Digital for income tax before it becomes compulsory for them on 6 April 2027.
HM Revenue and Customs (HMRC) is urging the next group to sign up early, with around 1,077,000 additional landlords and sole traders expected to join.
The threshold includes combined income from property and self-employment before deducting expenses or tax allowances.
Signing up now gives those affected time to check their details and choose compatible software before the requirements take effect, HMRC says.
Landlords already using MTD face a separate deadline, with their second quarterly update due on 7 November.
Preparing for digital tax
Craig Ogilvie, HMRC’s director of Making Tax Digital, said: “Hundreds of thousands of sole traders and landlords are already successfully using Making Tax Digital and now it’s time for the next group to get ready.
“Signing up now means you can prepare and familiarise yourself with the process before it becomes mandatory next April.”
Those joining will need to keep digital records and use compatible software to send quarterly summaries of their income and expenses.
The updates are not additional tax returns, although the software must also be used to complete the tax return.
Signing up for MTD
HMRC says recording information throughout the year can reduce the time spent gathering paperwork ahead of the January deadline.
Its estimate of the expanding number of landlords joining next April is based on analysis of Self Assessment returns for 2024 to 2025.
To sign up, customers must be registered for Self Assessment and have submitted a tax return within the past two years.
Agents can enrol clients through GOV.UK, which also lists compatible software.
Exemptions are available, including for those who are ‘digitally excluded’.
The next expansion follows the introduction of MTD for those with income above £50,000 in April 2026, with the threshold due to fall further to £20,000 from April 2028.
Landlords may find this HMRC video helpful
The post Landlords urged to prepare for Making Tax Digital 2027 appeared first on Property118.
View Full Article: Landlords urged to prepare for Making Tax Digital 2027
Busy landlords need more than a buyer — They need a team that delivers
Property118
Busy landlords need more than a buyer — They need a team that delivers
A busy landlord in Kent had already accepted two offers through other estate agents. Both sales fell through when the buyers could not secure mortgages.
Months of waiting had brought her no closer to selling. Pulled in several directions, she did not have the time or energy to untangle the problems herself.
She needed more than another offer. She needed someone to take responsibility for getting the sale done.
That is why she turned to Landlord Sales Agency. We agreed a minimum of £105,000 for her, plus 90% of anything achieved above our estimated £120,000 value.
That guaranteed amount represented 87.5% of our estimated vacant possession value. The difference gave us room to fund the work, cover costs and solve the problems needed to deliver a faster, more reliable sale.
For this landlord, using some of her equity meant having an experienced team take the job off her hands – with an agreed amount protected for her.
Two failed sales gave us a head start on the problems
We began by finding out why the previous buyers had struggled. One lender had declined because the property was a basement flat. Another had requested information the freeholder could not supply.
Those were lessons we could use to prepare the next sale properly.
We secured a buyer and took their deposit in just over four weeks. When the lender then valued the flat below the agreed purchase price, we challenged the valuation with comparable sales and worked with the buyer and seller to find a way forward.
The lender valued the property at £115,000. The buyer agreed to pay £117,000 with vacant possession.
Our margin reduced. The seller’s agreed £105,000 did not.
Rather than leaving her to choose between taking another financial hit or starting again, we made the figures work within our own margin.
We protected the rental income while securing the next step
The buyer needed vacant possession, but moving the tenant before the mortgage position was clear could have left the seller with another failed sale – this time with an empty flat and no rent.
We obtained written confirmation from the lender that the mortgage could proceed before telling the tenant they would need to relocate.
As soon as we had that, we spoke directly to the tenant, offered practical and financial support funded from our margin, and stayed involved until her move was complete. We confirmed she had vacated and coordinated access for the buyer.
The seller did not have to manage the tenant’s move or fund that support separately. We took care of it as part of delivering the sale.
We kept the sale moving when the paperwork didn’t
Questions about ground rent, planned works, fire safety and building management all had the potential to hold things up.
We tracked down the answers, gathered the information, followed communication to make sure nothing was lost or misplaced and chased progress to ensure the sale would complete as fast as possible.
When a concern arose about the property’s condition, we established the cause and made sure it was rectified to everyone’s satisfaction.
These are the gaps where sales can stall or collapse while everyone waits for someone else to find the root of the problem before taking responsibility. We made it our business to close them.
After completion, the seller wrote:
“After trying with multiple estate agents, we finally tried Landlord Sales Agency! They sold the property first time and were helpful and professional throughout the sale. They were on top of it at all times and left me feeling in good hands with less stress! Would definitely recommend them to anyone wanting a straight forward sale of their property”
This is what your equity pays for
Busy landlords do not need another list of people to chase. They need a team with the contacts, experience and time to make things happen.
At Landlord Sales Agency, we reach buyers through our network of more than 30,000 investors and buyers, alongside local and nationwide agents. We arrange access, photographs and video tours, and work directly with tenants to make sales possible with them in situ or support a move where needed.
We secure buyers’ commitment with a non-refundable deposit, then manage the sale through to completion. We coordinate solicitors, lenders and surveyors, challenge delays and find practical solutions when problems threaten the deal.
Our service is funded from the agreed margin within the sale price, with no separate seller’s fee or commission. That margin pays for the work that helps turn an accepted offer into money in the bank.
You make the decision to sell. We take responsibility for making the sale work.
Complete the form below and tell us a little about your property. We can explain what you could receive, what work we expect to handle and how much of your equity our service would need to deliver a faster, more reliable sale.
(function(){var el=document.getElementById(“ts-607776b5-3f7b-431c-b5cc-fc304603fee3″);if(!el)return;var b=document.body,h=document.documentElement;var dark=b.classList.contains(“dark-mode”)||b.classList.contains(“dark”)||b.classList.contains(“night-mode”)||h.classList.contains(“dark”);if(!dark){var bg=window.getComputedStyle(b).backgroundColor,m=bg.match(/d+/g);if(m)dark=(m[0]*0.299+m[1]*0.587+m[2]*0.114)<128;}el.setAttribute("data-theme",dark?"dark":"light");if(window.turnstile&&el.childElementCount===0){try{window.turnstile.render(el,{sitekey:el.getAttribute("data-sitekey"),theme:el.getAttribute("data-theme")});}catch(e){}}})();
(function(){
var uid = “crm-form-ba09a29b”;
var form = document.getElementById(uid + ‘-form’);
var wrap = document.getElementById(uid);
var msg = wrap.querySelector(‘.crm-message’);
var totalPages = 1;
var curPage = 0;
// ── Name casing ──────────────────────────────────────────────────────
// Tidy a name box as the visitor leaves it, so they are not staring at
// “JOHN SMITH” in their own form. Deliberately cosmetic: the API runs
// the same normalisation on submit and is the authority on what gets
// stored, so a disagreement here is harmless. Kept in step with
// packages/shared/src/names.ts.
var NAME_PARTICLES = ‘ van von de del della der den di da dal du la le el bin ibn al dos das do ter ten ‘;
var NAME_MACS = ‘ macdonald macintyre macleod macarthur macgregor macneil macpherson macrae mackinnon macqueen ‘;
function nameUp(s){ return s.replace(/[a-z]/i, function(c){ return c.toUpperCase(); }); }
function isParticle(w){ return NAME_PARTICLES.indexOf(‘ ‘ + w.toLowerCase() + ‘ ‘) >= 0; }
function nameRecase(atom){
if (!/[a-z]/i.test(atom)) return atom;
var dot = atom.charAt(atom.length – 1) === ‘.’ ? ‘.’ : ”;
var core = dot ? atom.slice(0, -1) : atom;
var lower = core.toLowerCase();
if (/^(?:II|III|IV|VI|VII|VIII|IX|XI|XII)$/.test(core.toUpperCase())) return core.toUpperCase() + dot;
if (lower === ‘jr’ || lower === ‘sr’) return nameUp(lower) + dot;
if (core.length === 1) return core.toUpperCase() + dot;
var mc = /^mc([a-z]{2,})$/.exec(lower);
if (mc) return ‘Mc’ + nameUp(mc[1]) + dot;
if (NAME_MACS.indexOf(‘ ‘ + lower + ‘ ‘) >= 0) return ‘Mac’ + nameUp(lower.slice(3)) + dot;
return nameUp(lower) + dot;
}
function nameWellFormed(atom){
// “Mccoll” has its leading capital but still wants McColl. Safe only
// because “Mc” is unambiguous — “Mac” deliberately has no such rule.
if (/^Mc[a-z]{2,}$/.test(atom)) return false;
return /^(?:[A-Z][a-z]*|[A-Z][a-z]+[A-Z][A-Za-z]*|O[A-Z][a-z]+|[A-Z]{1,3}|[IVX]+)$/.test(atom);
}
function tidyName(value){
var v = (value || ”).replace(/s+/g, ‘ ‘).replace(/^ | $/g, ”);
if (!v) return value;
if (/[@d,]|&[a-z]+;|&#|https?:|www./i.test(v)) return value; // not a name
var words = v.split(‘ ‘);
var deliberate = words.every(function(w){
// A lone particle is not a particle — it is someone’s name (Di, Al).
if (words.length > 1 && isParticle(w)) return true;
return w.split(/[-‘u2019.]/).filter(function(seg){ return /[a-z]/i.test(seg); })
.every(function(seg){ return nameWellFormed(seg); });
});
if (deliberate) return v;
return words.map(function(w, i){
if (i > 0 && isParticle(w)) return w.toLowerCase();
return w.split(/([-‘u2019.])/).map(function(seg){
return /^[-‘u2019.]$/.test(seg) ? seg : nameRecase(seg);
}).join(”);
}).join(‘ ‘);
}
// ── Thousand separators ──────────────────────────────────────────────
// Opt-in per field (data-thousands). Mirrors formatThousands() and the
// caret helpers in the CRM’s packages/shared/src/numbers.ts. The CRM
// strips the separators again on submit, so storage is unaffected.
function groupThousands(value){
var raw = String(value == null ? ” : value).replace(/,/g, ”);
if (!raw) return ”;
var neg = raw.charAt(0) === ‘-‘;
var body = neg ? raw.slice(1) : raw;
var dot = body.indexOf(‘.’);
var digits = function(x){ return x.replace(/[^0-9]/g, ”); };
var whole = digits(dot === -1 ? body : body.slice(0, dot));
var frac = dot === -1 ? null : digits(body.slice(dot + 1));
if (!whole && frac === null) return neg ? ‘-‘ : ”;
var grouped = whole.replace(/B(?=(d{3})+(?!d))/g, ‘,’);
return (neg ? ‘-‘ : ”) + grouped + (frac === null ? ” : ‘.’ + frac);
}
// Reposition by digit count, not character index: commas appear and
// vanish to the left of the caret, and counting characters would throw
// it to the end of the field on every keystroke.
function caretAfterGrouping(formatted, digitsBefore){
if (digitsBefore <= 0) return 0;
var seen = 0;
for (var i = 0; i parseFloat(cmp);
case ‘lessthan': return parseFloat(val) < parseFloat(cmp);
case 'contains': return val.indexOf(cmp) !== -1;
case 'startswith': return val.indexOf(cmp) === 0;
case 'endswith': return val.slice(-cmp.length) === cmp;
default: return false; // fail closed — mirror the CRM shared matcher
}
}
function applyConditionals() {
Object.keys(condMap).forEach(function(fieldId) {
var cond = condMap[fieldId];
var rules = cond.rules || [];
var match = cond.logicType === 'any'
? rules.some(evalRule)
: rules.every(evalRule);
var show = cond.actionType === 'show' ? match : !match;
var wrapper = form.querySelector('[data-field-id="' + fieldId + '"]');
if (!wrapper) {
var el = form.querySelector('[name="' + fieldId + '"], [name="' + fieldId + '[]"]');
if (el) wrapper = el.closest('.crm-field, .crm-half');
}
if (wrapper) wrapper.style.display = show ? '' : 'none';
});
}
form.addEventListener('change', applyConditionals);
form.addEventListener('input', applyConditionals);
applyConditionals();
// ── Required-field validation (Next + Submit) ────────────────────────
// Validate from the form's field config (id + type), NOT the [required]
// HTML attribute: a checkbox group can't carry a meaningful `required`
// (native means "tick every box"), so attribute checks skip it — which is
// why empty checkbox questions slipped past Next straight to submit.
var crmRequired = [{"id":"c364951b-ecb0-4a12-bfa4-9dbe564310e8","type":"name","label":"Name"},{"id":"910107df-b8a8-4541-879f-541cef9449e4","type":"email","label":"Email"},{"id":"3b317ed9-d327-4fe2-b92e-67efede67e6d","type":"phone","label":"Phone"},{"id":"c6fae2f0-c335-452b-aa03-2cc066163d71","type":"textarea","label":"Please give us details of how we can help and the properties in question"},{"id":"34c27d9f-b3d1-4a6d-b720-24000e9fa468","type":"checkbox","label":"Privacy Policy"}];
function crmWrapper(id) {
var w = form.querySelector('[data-field-id="' + id + '"]');
if (!w) { var el = form.querySelector('[name="' + id + '"], [name="' + id + '[]"]'); if (el) w = el.closest('.crm-field, .crm-half'); }
return w;
}
function crmFilled(fld) {
// The [name^="id["] arm catches composite fields. A name renders as id[first] /
// id[last] and an address as id[street] / id[city] / …, none of which match
// the two exact-name selectors – so els came back empty, the !els.length guard
// below returned true, and the field counted as filled. With novalidate on the
// form the browser's own required check is off too, so a required Name field
// could be left completely blank and both Next and Submit went through.
var els = form.querySelectorAll('[name="' + fld.id + '"], [name="' + fld.id + '[]"], [name^="' + fld.id + '["]');
if (!els.length) return true;
// Decide on what is actually RENDERED, not the declared type. A `product`
// field is choices (radio/checkbox) for a priced list but a single amount
// box for a user-defined price — and testing that box for .checked, which
// a text input never has, meant a required product field could never be
// satisfied. An invoice or "Request For Payment" form was unsubmittable:
// the payer typed an amount, hit Submit, and got "Please select at least
// one option." under the box, every time.
var checkable = Array.prototype.filter.call(els, function (el) {
return el.type === 'checkbox' || el.type === 'radio';
});
if (checkable.length) { return checkable.some(function (el) { return el.checked; }); }
if (['checkbox','radio','consent'].indexOf(fld.type) !== -1) { return false; }
// Test the sub-inputs the renderer actually marked required – a name field puts
// `required` on both first and last, an address field on none of its six – and
// fall back to the first input when nothing is marked, which is the existing
// single-input behaviour unchanged.
var reqEls = Array.prototype.filter.call(els, function (el) { return el.hasAttribute('required'); });
// Repeaters name their sub-inputs '[][]’, so the prefix arm above
// collects EVERY rendered row. Demanding all of them be filled means one blank
// extra row – added by mistake, or rendered by settings.minRows – blocks Next and
// Submit with a generic message on the wrapper. Only the first row is required.
var firstRow = form.querySelector(‘[data-field-id=”‘ + fld.id + ‘”] .crm-repeater-row’);
if (firstRow) {
reqEls = Array.prototype.filter.call(reqEls, function (el) { return firstRow.contains(el); });
}
var toTest = reqEls.length ? reqEls : [els[0]];
return Array.prototype.every.call(toTest, function (el) { return (el.value || ”).trim() !== ”; });
}
function crmFirstInvalid(pageIdx) {
for (var i = 0; i < crmRequired.length; i++) {
var fld = crmRequired[i]; var w = crmWrapper(fld.id);
if (!w) continue;
if (w.style.display === 'none') continue;
if (pageIdx != null) { var pd = w.closest('[data-page]'); if (!pd || parseInt(pd.getAttribute('data-page')) !== pageIdx) continue; }
if (!crmFilled(fld)) return fld;
}
return null;
}
// Shows the error in a red box UNDER the field, matching the form's own
// .crm-message error styling, and scrolls to it.
function crmMarkError(w, text) {
if (!w) return;
var e = w.querySelector('.crm-inline-error');
if (!e) { e = document.createElement('div'); e.className = 'crm-inline-error'; w.appendChild(e); }
e.style.cssText = 'background:#fee2e2;color:#991b1b;padding:.55rem .75rem;border-radius:4px;margin-top:.4rem;font-size:.9rem';
e.textContent = text || 'Please answer this before continuing.';
}
function crmClearError(w) { if (!w) return; var e = w.querySelector('.crm-inline-error'); if (e) e.parentNode.removeChild(e); }
function crmReportInvalid(fld) {
var w = crmWrapper(fld.id);
// Match the message to what the visitor is actually looking at — an amount
// box should not be told to "select an option".
var els = form.querySelectorAll('[name="' + fld.id + '"], [name="' + fld.id + '[]"]');
var hasChoices = Array.prototype.some.call(els, function (el) {
return el.type === 'checkbox' || el.type === 'radio';
});
var t;
if (fld.type === 'product' && !hasChoices) { t = 'Please enter an amount.'; }
else if (['checkbox','product'].indexOf(fld.type) !== -1) { t = 'Please select at least one option.'; }
else if (fld.type === 'radio') { t = 'Please choose an option.'; }
else { t = 'Please fill this in.'; }
crmMarkError(w, t);
if (w && w.scrollIntoView) w.scrollIntoView({ behavior: 'smooth', block: 'center' });
}
form.addEventListener('change', function(e){ var w = e.target && e.target.closest ? e.target.closest('.crm-field, .crm-half, [data-field-id]') : null; if (w) crmClearError(w); });
form.addEventListener('input', function(e){ var w = e.target && e.target.closest ? e.target.closest('.crm-field, .crm-half, [data-field-id]') : null; if (w) crmClearError(w); });
// ── Multi-page navigation ────────────────────────────────────────────
// ── Submit ────────────────────────────────────────────────────────────
var submitBtn = form.querySelector('button[type=submit]');
var btnText = submitBtn ? submitBtn.textContent : 'Submit';
var crmApiUrl = "https://crm-api.property118.com";
function collectFormData() {
var data = {};
for (var j = 0; j < form.elements.length; j++) {
var el = form.elements[j];
if (!el.name) continue;
if (el.type === 'file') continue; // handled by uploadFiles()
if (el.type === 'radio' && !el.checked) continue;
if (el.type === 'checkbox') {
if (!el.checked) continue;
var k = el.name.replace('[]','');
data[k] = data[k] ? data[k].concat([el.value]) : [el.value];
} else {
data[el.name] = el.value;
}
}
// Repeater fields: sub-inputs are named "[][]”.
// Group those flat keys into an array of row objects under the repeater
// id. Plain fields, checkbox “[]” arrays and single-bracket composites
// (name[first], address[city]) don’t match the double-bracket pattern, so
// ordinary submissions are unchanged.
var _repRe = /^(.+?)[(d+)][(.+)]$/;
var _repIds = {};
Object.keys( data ).forEach( function ( key ) {
var m = key.match( _repRe );
if ( ! m ) { return; }
var rid = m[1], row = parseInt( m[2], 10 ), sub = m[3];
_repIds[ rid ] = true;
if ( ! Array.isArray( data[ rid ] ) ) { data[ rid ] = []; }
if ( ! data[ rid ][ row ] || typeof data[ rid ][ row ] !== ‘object’ ) { data[ rid ][ row ] = {}; }
data[ rid ][ row ][ sub ] = data[ key ];
delete data[ key ];
} );
Object.keys( _repIds ).forEach( function ( rid ) {
if ( Array.isArray( data[ rid ] ) ) {
data[ rid ] = data[ rid ].filter( function ( r ) { return r && typeof r === ‘object'; } );
}
} );
// GF auto-substituted {user_agent} / {referer} on hidden fields
// at render time. We do the equivalent right before submit so
// fields whose default value carries these placeholders
// resolve to the browser’s actual values rather than being
// stored as literal “{user_agent}” / “{referer}” strings.
// The last ARTICLE the visitor read (set client-side on post views by
// P118_Article_Views). Used to attribute the enquiry to the article
// even after navigating away or with a stripped/absent referer.
var lastPost = ”;
try {
var lpm = document.cookie.match(/(?:^|;s*)p118_last_post=([^;]+)/);
if (lpm) lastPost = decodeURIComponent(lpm[1]);
} catch (e) {}
var subs = {
‘{user_agent}': navigator.userAgent || ”,
// Prefer the last article read; fall back to the (lossy) HTTP referer.
‘{referer}': lastPost || document.referrer || ”,
‘{last_post}': lastPost || ”,
‘{embed_url}': window.location.href || ”,
};
for (var name in data) {
if (!data.hasOwnProperty(name)) continue;
var v = data[name];
if (typeof v !== ‘string’) continue;
for (var tag in subs) {
if (v.indexOf(tag) !== -1) v = v.split(tag).join(subs[tag]);
}
data[name] = v;
}
// Agent/BDM attribution — read LIVE so it works even on a fully cached
// page (the browser always sees the real URL + cookie). URL ?ataid=/?cid=
// first, then the 30-day agent_id/cid cookies set by atat-tracking.php.
var _qp = new URLSearchParams(window.location.search);
var _ataid = _qp.get(‘ataid’) || (document.cookie.match(/(?:^|;s*)agent_id=([^;]+)/) || [])[1] || ”;
var _cid = _qp.get(‘cid’) || (document.cookie.match(/(?:^|;s*)cid=([^;]+)/) || [])[1] || ”;
if (_ataid) data.agent_id = decodeURIComponent(_ataid);
if (_cid) data.bdm_id = decodeURIComponent(_cid);
// Which page the form was actually on. Read live for the same reason
// as the attribution above: on a cached page the server has no idea
// which URL it is being served as, but the browser always does.
data._sourceUrl = window.location.href;
// …and what sent them to it. Read live for the same reason: a cached
// page cannot know either, but the browser does. Blank when they
// typed the address, used a bookmark, or came from an email client —
// which is the honest answer, not a gap to be filled in server-side.
data._referrerUrl = document.referrer || ”;
// This browser’s progress through a multi-page form is now sent.
if (typeof progVisit !== ‘undefined’ && progVisit) data._visitId = progVisit;
return data;
}
function uploadFiles(data) {
var fileInputs = form.querySelectorAll(‘input[type=file][data-crm-file-field]’);
var uploads = [];
fileInputs.forEach(function(el) {
if (!el.files || !el.files[0]) return;
var fd = new FormData();
fd.append(‘file’, el.files[0]);
var fieldName = el.name;
uploads.push(
fetch(crmApiUrl + ‘/public/forms/’ + “08ceeaae-4809-444e-ba0f-88da5836c463″ + ‘/upload’, { method: ‘POST’, body: fd })
.then(function(r) {
if (!r.ok) throw new Error(‘File upload failed (‘ + r.status + ‘)’);
return r.json();
})
.then(function(res) {
if (res.path) data[fieldName] = res.path;
else throw new Error(res.error || ‘File upload failed’);
})
);
});
return Promise.all(uploads).then(function() { return data; });
}
function submitFormData(data) {
var body = new FormData();
body.append(‘action’, ‘p118_crm_submit’);
body.append(‘form_id’, “08ceeaae-4809-444e-ba0f-88da5836c463″);
body.append(‘data’, JSON.stringify(data));
// Embed-page context for GF-style merge tags ({embed_url},
// {embed_post:post_title}, {embed_post:ID}). Captured PHP-side
// at render time, then echoed to JS so the submit fetch can
// forward to V2 as request headers.
body.append(‘embed_url’, “”);
body.append(‘embed_post_id’, “0”);
body.append(‘embed_post_title’, “”);
return fetch(“https://www.property118.com/wp-admin/admin-ajax.php”, { method: ‘POST’, body: body, credentials: ‘same-origin’ })
.then(function(r){ return r.json(); })
.then(function(res){
var p = res.data || res;
if (p && p.success) {
if (typeof progDone === ‘function’) progDone();
if (p.confirmationType === ‘form’ && p.nextFormId) {
return swapInNextForm(p.nextFormId, p.prefill || {});
}
if (p.confirmationType === ‘redirect’ && p.confirmationRedirectUrl) {
window.location.href = p.confirmationRedirectUrl;
} else {
form.style.display = ‘none';
msg.className = ‘crm-message success';
// Sent: the progress line says so, not “Step 6 of 6″.
var doneText = wrap.querySelector(‘.crm-progress-text’);
if (doneText) doneText.textContent = ‘Completed';
var doneFill = wrap.querySelector(‘.crm-progress-fill’);
if (doneFill) doneFill.style.width = ‘100%';
msg.innerHTML = p.confirmationMessage || ‘Thank you for your submission.';
// Carry the calculator’s own results across. A calculator form
// renders its figures into [data-iht-results] as the visitor
// types; hiding the form hid those too, so the completion
// screen went blank and the visitor lost what they had just
// worked out. Nothing happens on forms without that element.
var resultsEl = form.querySelector(‘[data-iht-results]’);
if (resultsEl && resultsEl.innerHTML.trim()) {
var carried = document.createElement(‘div’);
carried.className = ‘crm-message-results';
carried.innerHTML = resultsEl.innerHTML;
msg.appendChild(carried);
}
// Download link for a generated report, present only when the
// API filed the PDF before responding. Built through the DOM
// rather than concatenated into innerHTML so the URL cannot
// inject markup.
if (p.reportDownloadUrl) {
var dlWrap = document.createElement(‘p’);
dlWrap.className = ‘crm-report-download';
var dl = document.createElement(‘a’);
dl.className = ‘crm-report-button';
// Building through the DOM stops markup injection but not a
// javascript: URL, which would run in this origin the moment
// the submitter clicks the button.
dl.href = /^https?:///i.test(String(p.reportDownloadUrl)) ? p.reportDownloadUrl : ‘#';
dl.target = ‘_blank';
dl.rel = ‘noopener noreferrer';
dl.textContent = ‘Download your report (PDF)';
dlWrap.appendChild(dl);
msg.appendChild(dlWrap);
}
msg.style.display = ‘block';
if (msg.scrollIntoView) {
msg.scrollIntoView({ behavior: ‘smooth’, block: ‘start’ });
}
}
} else {
throw new Error((p && p.error) || ‘Submission failed.’);
}
});
}
// Replace this whole form widget with another form, rendered server-side
// with the carried-over values seeded in. Inline injected via
// innerHTML won’t run, so we re-create each script node to execute it
// (this is what wires up the new form’s submit / conditional logic).
function swapInNextForm(nextFormId, prefill) {
var rbody = new FormData();
rbody.append(‘action’, ‘p118_crm_render_form’);
rbody.append(‘form_id’, nextFormId);
rbody.append(‘prefill’, JSON.stringify(prefill || {}));
return fetch(“https://www.property118.com/wp-admin/admin-ajax.php”, { method: ‘POST’, body: rbody, credentials: ‘same-origin’ })
.then(function(r){ return r.json(); })
.then(function(res2){
var pd = res2.data || res2;
if (!pd || !pd.html) { throw new Error((pd && pd.error) || ‘Could not load the next form.’); }
var frag = document.createElement(‘div’);
frag.innerHTML = pd.html;
var parent = wrap.parentNode;
var nodes = [];
while (frag.firstChild) {
var node = frag.firstChild;
parent.insertBefore(node, wrap);
nodes.push(node);
}
parent.removeChild(wrap);
function reexec(old) {
var s = document.createElement(‘script’);
for (var a = 0; a < old.attributes.length; a++) {
s.setAttribute(old.attributes[a].name, old.attributes[a].value);
}
if (!old.src) { s.textContent = old.textContent; }
old.parentNode.replaceChild(s, old);
}
nodes.forEach(function(n){
if (n.tagName === 'SCRIPT') { reexec(n); }
else if (n.querySelectorAll) {
var scripts = n.querySelectorAll('script');
for (var k = 0; k < scripts.length; k++) { reexec(scripts[k]); }
}
});
var first = nodes[0];
try { if (first && first.scrollIntoView) first.scrollIntoView({ behavior: 'smooth', block: 'start' }); } catch (e) {}
});
}
form.addEventListener('submit', function(e){
e.preventDefault();
// Validate required fields before submitting. Next only guards the pages
// before it, so the final page (and single-page forms) are checked here;
// jump to the first page that has a problem.
var vbad0 = crmFirstInvalid(null);
if (vbad0) { crmReportInvalid(vbad0); return; }
var data = collectFormData();
if (submitBtn) { submitBtn.disabled = true; submitBtn.textContent = 'Processing…'; }
msg.style.display = 'none';
// Standard form (no payment)
uploadFiles(data)
.then(function(d) { return submitFormData(d); })
.catch(function(err){
resetTurnstile();
if (submitBtn) { submitBtn.disabled = false; submitBtn.textContent = btnText; }
msg.className = 'crm-message error';
msg.textContent = err.message;
msg.style.display = 'block';
});
});
// ── Repeater fields (add / remove rows) ──────────────────────────
form.querySelectorAll( '.crm-repeater' ).forEach( function ( rep ) {
var rowsWrap = rep.querySelector( '.crm-repeater-rows' );
var tpl = rep.querySelector( '.crm-repeater-template' );
var addBtn = rep.querySelector( '.crm-repeater-add' );
if ( addBtn && tpl && rowsWrap ) {
addBtn.addEventListener( 'click', function () {
var idx = parseInt( rep.getAttribute( 'data-next-index' ) || '1', 10 );
var tmp = document.createElement( 'div' );
tmp.innerHTML = tpl.innerHTML.split( '__ROW__' ).join( idx );
var row = tmp.firstElementChild;
if ( ! row ) { return; }
row.setAttribute( 'data-row', idx );
rowsWrap.appendChild( row );
rep.setAttribute( 'data-next-index', idx + 1 );
rep.dispatchEvent( new CustomEvent( 'crm-repeater-change', { bubbles: true } ) );
} );
}
if ( rowsWrap ) {
rowsWrap.addEventListener( 'click', function ( e ) {
var btn = e.target.closest ? e.target.closest( '.crm-repeater-remove' ) : null;
if ( ! btn ) { return; }
if ( rowsWrap.querySelectorAll( '.crm-repeater-row' ).length <= 1 ) { return; }
var r = btn.closest( '.crm-repeater-row' );
if ( r ) { r.remove(); }
rep.dispatchEvent( new CustomEvent( 'crm-repeater-change', { bubbles: true } ) );
} );
}
} );
// ── Save as you go ───────────────────────────────────────────────────
// A multi-page form keeps its answers in this browser on every change and
// every Next, so closing the page loses nothing: reopen it and it carries
// on from the same page. Each Next also tells the CRM which page was
// reached — only the page number, never the answers — so the form's
// Entries page can show where people give up. A client a chase link
// names is counted against them; anyone else against a random id this
// browser keeps. All of it is best-effort: the form works without it.
})();
The post Busy landlords need more than a buyer — They need a team that delivers appeared first on Property118.
View Full Article: Busy landlords need more than a buyer — They need a team that delivers
Joint tenancy or room-by-room? Student landlords need to look again
Property118
Joint tenancy or room-by-room? Student landlords need to look again
Five students rent a house together. Four are happy, the rent is being paid and they want to stay. The fifth decides to leave and gives notice.
Under a joint periodic tenancy, that notice can end the tenancy for all five.
That isn’t a new principle of landlord and tenant law. One joint tenant has long been able to end a periodic joint tenancy without the agreement of the others. What has changed is its importance to student landlords now that assured student tenancies are periodic rather than fixed term. Current guidance confirms that a valid notice from one joint tenant ends the periodic tenancy for all of them.
Under the old student model, a group might sign a 12-month fixed term. If one student wanted to leave after six months, moving out did not by itself end their liability. In practice, that gave the group a strong incentive to find an acceptable replacement.
Now one student can give notice and bring the whole joint tenancy to an end.
So, should student landlords abandon joint tenancies and let each room separately? There is an obvious attraction.
If five students have five individual tenancies and one gives notice, the other four tenancies continue. The landlord has one room to fill rather than having to deal with the end of the tenancy for the entire house.
But that does not make room-by-room letting an automatic answer.
A joint tenancy is administratively simple. There is one agreement covering the household and the students have chosen the people they want to live with.
Individual tenancies mean managing each letting separately. If someone leaves halfway through the academic year, the landlord may have to find a replacement prepared to move into an established household of strangers.
There is also the question of the mortgage and insurance.
Before changing the way a property is let, landlords should check that the proposed arrangement remains within the terms of their mortgage and insurance and whether either provider needs to be told about the change. It is better to establish that before altering the letting model than assume that five individual agreements will be treated in exactly the same way as one joint agreement.
Joint tenancies still have advantages. Separate agreements remove one particular risk, but bring a different management model with them.
The real change is that landlords can no longer choose between the two simply because “that’s how I’ve always let my student houses”.
For anyone planning their 2027 student lets, the question is now a practical one: which risk would you rather manage?
The risk that one student’s notice ends the joint tenancy, or the additional work and complications that come with letting room by room?
That decision needs to be made property by property, not by changing every tenancy agreement in the portfolio because one option initially looks safer.
Peter Littlewood has worked with landlords for many years through iHowz Landlord Association and now delivers landlord and agent training through B-Informed, including on the Renters’ Rights Act, student lettings and HMO management.
The post Joint tenancy or room-by-room? Student landlords need to look again appeared first on Property118.
View Full Article: Joint tenancy or room-by-room? Student landlords need to look again
The invisible cage keeping landlords from the life they worked for
Property118
The invisible cage keeping landlords from the life they worked for
For nearly four decades, I helped landlords build their wealth, while most of my time is now spent helping them work out how to enjoy it. Behind the questions about selling properties and paying tax lies a much bigger question about whether they can give themselves permission to live differently and put a practical plan in place to make that possible.
There are two very different pictures I want to put in front of you this Sunday, both involving people who have worked hard, built wealth and reached a point in life where they would like more freedom. Their expectations about what they can do next are very different.
In one picture are landlords who feel they will remain in the rental business until the day they die. They would like to travel, spend more time with their families and shed some responsibility, yet every thought of doing so leads to another unanswered question, until staying exactly where they are feels like the only realistic choice.
In the other are friends I have made during more than 11 years of living abroad, many of whom have achieved financial and location independence. They can choose where to live, how to spend their time and how much of it to share with the people they love, having made a transition that the first group still struggles to imagine.
One friend bought a yacht and has the financial means to help his children buy their own homes and make it possible for them to sail around the Mediterranean with him without needing to work. He can share his wealth, enjoy their company and see the difference it makes while he is here to experience it.
Among those friends who have made the transition, the refrain is the same: they should have done it sooner. That stays with me, because so much of my working life now involves conversations with people who cannot yet see how to make a similar change.
The work that has changed
For nearly four decades, I have helped landlords build and optimise their rental property businesses. Over the last two years, around 90% of my time has been spent helping them dismantle those businesses, protect and enjoy their wealth, reduce risk and prepare a legacy their children actually want to inherit.
The direction of this change has come from the landlords themselves. They are arriving with questions about selling, retirement and succession because those are the things they now want help with.
They want to know which properties to sell first and why, understand the Capital Gains Tax position, establish what will remain after mortgages and costs, and work out where to park the money afterwards. They also want to know what could replace the rental income and whether they can afford to stop doing so much.
They also want examples of how other landlords have reduced their risks and responsibilities, organised their finances and decided what to keep. They are interested in how much time those landlords now spend with their families and what an ordinary week looks like after making the transition.
I think those questions belong together, because a calculation of sale proceeds has much more meaning when you know what you want those proceeds to make possible. An appealing picture of retirement becomes useful when you understand how you could afford it.
These are the conversations our team of four Property118 consultants is here to help with, and I am one of that team. My three colleagues are every bit as capable of helping you make sense of your position and the choices ahead.
How the invisible cage takes shape
The cage is usually a collection of questions that have never been brought together and properly answered. The tax might be substantial and the borrowing complicated, while the income feels essential, the alternatives are unfamiliar and the family has never discussed any of it.
Each concern sends you back to the business you know, where there is a repair to approve, a mortgage to review or an email that needs answering. Those things feel immediate and understandable, while working out what you want from the next 20 years feels harder to fit into the diary.
Another year passes as you deal with everything that needs doing. The life you hoped the business would eventually provide stays on the other side of the bars while those familiar responsibilities continue to occupy your time.
Familiarity can make a demanding situation feel safer than an unfamiliar alternative, especially when you know what a leaking roof involves. You may have much less confidence about managing a substantial sum outside property or deciding how much you can spend in retirement, which makes the hesitation understandable.
There may also be pride involved because you built this business through your own judgement and effort. Selling part of it can feel strangely uncomfortable when you are accustomed to measuring progress through what you acquire and improve, even if doing so would serve a purpose you value.
Tax, debt and income requirements deserve serious attention when assessing what is affordable. Establishing that something is unaffordable gives you a clearer basis for a decision than living for years with an untested assumption that it must be.
What freedom would look like for you
The yacht is one person’s version of the life he wants, while your ambitions may be entirely different. Perhaps you would like to spend several weeks visiting children overseas, or take the grandchildren away while they are still young enough to think a holiday with you is an adventure.
You might want a winter somewhere warm, time to learn a language or the freedom to accept an invitation without first thinking about the next property problem. You may simply want to spend more unhurried time with your partner, after years in which the business has occupied so much of your attention.
Try picturing an ordinary Tuesday, including where you would wake up, what you would do after breakfast, who you would see and what you would be pleased no longer to have to deal with. A satisfying retirement has to work on ordinary days as well as during the memorable holidays.
Financial independence can give you the ability to choose how much work you do, while location independence can give you more choice about where you do it. You might still enjoy projects, helping other people or keeping an interest in property, with the attraction being greater control over your commitments.
There is something particularly appealing about being able to help your family while you can share in the result. A contribution towards a home, a family holiday or more time together has a human value that never appears in a portfolio valuation and deserves a place in the planning.
Imagine being able to extend a visit because you are enjoying it, or to spend a weekday with a grandchild without mentally rearranging everything else. Those are modest freedoms, but they can change the texture of a life. The opportunity is to decide which experiences matter to you and give them proper consideration alongside the financial figures.
The conversation many families have never had
What still amazes me is how many landlords have never had a proper conversation with their families about what they want. They have worked for years with their partner and children in mind, yet much of the intended future rests on assumptions.
A partner may want less responsibility, while an adult child may be proud of what you have achieved and still have no desire to become a landlord. Another may be interested if the business is organised in a way they can manage, and each of those preferences deserves to be heard.
It can be difficult for children to say any of this when they worry that expressing a preference for something simpler will sound ungrateful. They may assume that you would be hurt if they sold the properties, while you assume that their silence means they are happy with your plans.
Begin by asking what they would actually welcome and give them room to answer honestly. You could explore whether they want to run the business, would prefer assets they could divide and manage independently, or would welcome help now that could make a greater difference to their lives.
Your own future also deserves discussion, including how your partner would like the next few years to look and whether you are both still enjoying the business. It is worth establishing how much you consider enough, particularly if you are continuing towards a target that neither of you has ever defined.
You may discover that your family would be delighted to see you enjoy more of what you have earned, or that they do want to continue the business. Either answer gives you useful information on which to build a plan, based on a conversation about their wishes.
Could you take over your best friend’s property business
Imagine your best friend owns a rental property business of a similar size to yours. Over the years, you have discussed tenants, mortgages, repairs and the frustrations of being a landlord, so you have a reasonable idea of what they own, although you have never needed to understand the detail.
One day, they tell you they have been diagnosed with a terminal illness and have been told they have less than a year to live. They ask whether you would help get everything organised for their family, but as the conversation continues, you realise they are already too ill to do much themselves and would need you to take responsibility for almost everything.
You would naturally want to help, but where would you begin? Before you could make sensible decisions, you would need to establish what they own, how the borrowing is arranged, what income the properties produce, where the records are kept and what their family would actually want to happen to the business.
Even with your experience, how comfortable would you feel deciding which properties should be retained, whether any should be sold and who could take over the management? You would also have to fit this around your own business and family, knowing that your friend was relying on you and that the time available might be shorter than anyone hoped.
Now imagine the same responsibility falling to your children after your death. They may have none of your experience, no interest in becoming landlords and very little understanding of the business you have spent years building, yet they would be trying to make sense of it while grieving for you.
If you would struggle to take over your best friend’s property business while they were still alive, how well have you prepared your loved ones to take over yours when you are gone?
You would also discover how much of your friend’s knowledge had never needed to be written down. An expensive repair they were expecting, the reason for retaining a particular property or the history behind a tenant’s circumstances could all affect decisions that somebody else was now being asked to make.
The family would need to know where accessible cash could be found and what had to be paid while the estate was being dealt with. Where inheritance tax is payable, the normal payment deadline is the end of the sixth month after death, and a payment is usually needed before probate can be granted.
Tax attributable to qualifying property can be paid in ten annual instalments, with the first due at that same deadline. Interest generally applies to the outstanding tax on ordinary rental property, and selling the property brings the remaining tax attributable to it into payment, so the family would still need a workable funding plan.
A lender’s requirements will depend on the borrowing and circumstances, while the tax position will depend on the estate. Assuming the family can sort everything out later leaves them to discover the answers at a difficult time.
The darker side of the invisible cage is that, if you never examine how to leave it, the unresolved decisions may eventually pass to someone else. The people you most wanted to protect could inherit a collection of responsibilities they were never prepared to take on.
The basics that keep being postponed
I also encounter landlords with no Will, no Lasting Powers of Attorney and no life insurance. Important decisions about who should receive their wealth, who could act for them during their lifetime and how money might be available when needed have remained on the list of things to sort out.
A Will addresses what should happen after death, while a power of attorney deals with decisions during your lifetime. In England and Wales, Lasting Powers of Attorney can appoint people to help with or make specified decisions, including if you lose capacity, with different arrangements applying in Scotland and Northern Ireland. This authority ends on death, so the arrangements for administering your estate need separate attention.
Without a valid Will, the applicable intestacy rules determine entitlement. Even where a Will exists, it needs to be considered alongside the assets, ownership arrangements and wishes it is intended to address. A document written years ago deserves attention when life or the business has changed.
Life insurance is a separate discussion about whether suitable cover could help meet a need for money, taking account of cost, eligibility, ownership and purpose. The useful starting point is to identify what your family would need and what resources would be available, then obtain appropriate advice.
These matters remain relevant if you intend to keep every property. You can make the business easier for someone else to understand and improve the arrangements around it while continuing to enjoy running it yourself.
Turning property wealth into usable choices
A portfolio valuation and the balance of equity provide only part of the information needed to establish what you could spend after a sale. Borrowing, transaction costs and tax all need to be considered, together with the ownership arrangements.
Start with the income the business actually provides, bearing in mind that your household lives on what remains after costs and tax. Gross rent is a useful operating figure, while repairs, management, finance and irregular expenditure all matter when assessing how dependable that income is.
Then look at the equity committed to producing that income and consider how the property’s current return compares with the capital tied up in it. A property that has risen substantially in value may still be worth retaining, with the work involved and the risks you are accepting forming part of that assessment.
Your time belongs in that discussion because, even where an agent handles the day-to-day management, you may still carry the financial decisions and ultimate responsibility. If those decisions occupy more of your thoughts than you want, that is a relevant cost to you.
The rest of your finances matter too, because pensions, savings, other investments, your home and financial commitments can change the picture considerably. The amount you want to spend, the help you hope to give your family and the reserves you want to retain also need to be considered.
Once those things are set out together, keeping the business, reducing it gradually or making a more complete exit can be examined against the same objectives. You remain the person deciding which outcome you want, with the comparison helping you assess the choices available.
When the tax bill becomes the strongest bar
Capital Gains Tax can loom so large in someone’s mind that the conversation stops before the figure has been calculated properly. A rough estimate becomes a reason to keep everything indefinitely, without comparing what would remain after selling with the cost and benefit of continuing.
The amount needs to be established using the right information, including examination of the gain, relevant costs and available reliefs for personally owned property. If a company owns the property, Corporation Tax on a chargeable gain may apply instead, with separate questions about taking money out of the company.
That work is needed to arrive at a reliable picture of the money available under each realistic option. The timing of liabilities and reporting obligations needs attention as well as the amount.
You might decide that a sale is worthwhile after allowing for tax, prefer a phased approach that better suits your needs, or retain particular assets because the figures and family plans support doing so. The appropriate choice depends on what that examination establishes about your finances and the outcome you want.
Tax needs to be considered alongside the life you could afford after paying it and the income, risks and responsibilities you would retain by continuing. The objective is to understand the consequences well enough to choose with confidence.
Choosing what to sell and how
It is tempting to begin with whichever property has caused the latest problem. That may turn out to be the right choice, but it is worth looking beyond the most recent frustration. Another property could be producing a weaker return, facing substantial expenditure or releasing more useful capital on sale.
The order needs to account for income, borrowing, tax, condition, marketability and your timetable. Selling an easy property first might make progress possible; it could also leave you with a more demanding collection of assets. What remains after each step matters just as much as what has been sold.
Tenants belong in the plan, with their homes, the legal position and the practical sale route needing careful consideration. A sale with tenants in place may be an option in some circumstances, but the price, likely buyers and transaction terms need to be understood.
Property118 has published an account of Shirley McLean selling four properties to another landlord. In that account, published by Landlord Sales Agency, she described accepting a price compromise to avoid the uncertainty and potential carrying costs of a prolonged series of sales, while keeping her tenants in place.
Another account from the same agency described Shauna selling 23 properties and retaining ten. These are individual sale experiences, rather than a formula for anyone else’s price or timetable. They illustrate how different a decision to reduce a portfolio can look in practice.
For your own plan, give thought to the endpoint and, if the intention is to keep a few properties, decide what would make them suitable for the life you want. Otherwise, a gradual exit can become an extended process with no clear point at which the desired freedom actually arrives.
A useful plan can describe the stages, what the first sales would achieve, how the remaining business would operate and when you would reassess the income and your appetite for continuing. Breaking the work into stages can make a large change easier to examine, with opportunities to review the details as the plan develops.
Where the money goes afterwards
For someone who has spent decades buying property, a substantial amount of cash can feel unfamiliar. The bricks and mortar were tangible and the rent arrived regularly, whereas selling raises a new set of decisions about security, access and income.
Money needed for tax and near-term spending should be considered separately from money intended to support later years. Where to hold sale proceeds while considering your options is a different question from how to organise a long-term retirement plan.
Even temporary arrangements deserve thought, with access, the account holder and applicable protection all needing attention. FSCS deposit protection depends on eligibility and banking authorisation; different brand names can share one banking licence, so a large balance merits a deliberate arrangement.
For the longer term, the discussion needs to consider income requirements, inflation, access to capital, risk and how long the money may need to support you. Existing pensions and investments belong in that picture, with appropriate regulated financial advice helping you assess the choices against your circumstances.
Planning this alongside the sales and understanding what could happen to the proceeds helps answer the fear that selling means stepping into the unknown. The arrangements should make sense to you, including their costs, limitations and risks.
The part that never appears in the accounts
I want to hear more from landlords about life after the transition, including how the first few months felt and whether they missed the business. The sale itself is only one part of the story, alongside adjusting to a different pattern of income and a diary with fewer obligations.
Most of all, I would like to know what they have done with the time and how much more often they see their families. I would also be interested in whether they have taken the trip they kept postponing, are enjoying a smaller business or have discovered interests they had little room for before.
Those accounts deserve to include the adjustments as well as the pleasures, because a business can provide purpose, routine and a sense of achievement. Planning for retirement involves thinking about what will fill the space it leaves, alongside the financial arrangements.
My friends’ experiences make the possibilities feel real to me, because their freedom gives them choices about family, travel and how they spend their days. The life they enjoy helps explain why making the transition matters to them.
For readers without children, the same questions about enjoyment and responsibility still apply. Your priorities may involve a partner, friends, other relatives or causes you care about. The future should reflect your wishes, including who you would want to benefit and who could help carry them out.
You may also read this while still building enthusiastically. Understanding your eventual destination can help you decide what to acquire, what responsibilities to accept and how to organise the business now. The question of what the wealth is for has value long before retirement.
A Sunday worth setting aside
If you recognise yourself in any of this, give the subject some uninterrupted time and begin with a blank page describing the life you would like over the next few years. Be specific enough that somebody else could understand what more freedom means to you, whether that is three months abroad, two afternoons a week with grandchildren or simply fewer financial decisions.
Write down what you would like to stop doing as well, because those responsibilities can be easier to identify than an ideal retirement. It is also worth considering what you would still enjoy keeping, because the right outcome may include some continuing involvement.
Have the family conversation while those thoughts are fresh, sharing this article if it helps explain why you are asking. Listen to what the people closest to you would welcome and where their wishes differ from what you assumed, leaving room for a second conversation if they need time to think.
Next, document the financial position by gathering the property details, ownership information, realistic value estimates, borrowing, rents and costs, together with the rest of your assets and commitments. Identify estimates clearly and record what you do not yet know, so the information provides a useful starting picture of your position.
Finally, note the arrangements that already exist, including where the Will is kept, whether relevant powers of attorney are in place and what insurance is held. Recording who understands the business and where its records can be found makes the gaps visible enough to discuss sensibly.
Preparation takes effort, and if assembling the information feels difficult with your own knowledge available, consider what it might be like for someone else to reconstruct it without you. The preparation has value before any property is sold because it helps make your affairs easier to understand.
A consultation with the Property118 team
A £400 Property118 consultation gives you dedicated time with one of our four consultants to discuss where you are now, what you want from life and the questions that need resolving. The information you prepare helps your consultant make that conversation specific to you.
I am proud to recommend each of my three colleagues and have every confidence in their ability to help you examine your choices. Whichever of us you speak to, you should feel able to talk openly about your ambitions, ask the questions that have been holding you back and explore what needs to happen next.
The consultation is a starting point, with detailed analysis, legal or tax work and regulated financial advice potentially needed afterwards, depending on your circumstances and the direction you choose. Understanding what further work is required is part of moving from a broad ambition towards an informed plan.
Come prepared to think as well as to provide figures, and be candid about what worries you, which responsibilities you want to shed and what you would like your wealth to make possible. If you are unsure what you want, identifying that uncertainty is a useful beginning.
When I think about my friend sailing with his children, I think about the time they can share while he is there to enjoy it. The imagined conversation with a seriously ill friend asks us to consider how much harder decisions can become when that time is running out.
Before you put this article aside, consider whether you would feel comfortable handing your own property business to that friend tomorrow, with only the information and arrangements you currently have in place. If the answer is no, think about what would need to change before you could reasonably expect your loved ones to manage it without you.
Set aside time to prepare and begin the conversation with your family. Give the life you worked for a chance to become more than something you hope to enjoy one day.
BOOK YOUR £400 CONSULTATION TODAY
The post The invisible cage keeping landlords from the life they worked for appeared first on Property118.
View Full Article: The invisible cage keeping landlords from the life they worked for
Categories
- Landlords (19)
- Real Estate (9)
- Renewables & Green Issues (1)
- Rental Property Investment (1)
- Tenants (21)
- Uncategorized (12,989)
Archives
- October 2026 (15)
- September 2026 (57)
- August 2026 (61)
- July 2026 (63)
- June 2026 (70)
- May 2026 (70)
- April 2026 (78)
- March 2026 (72)
- February 2026 (55)
- January 2026 (52)
- December 2025 (62)
- August 2025 (51)
- July 2025 (51)
- June 2025 (49)
- May 2025 (50)
- April 2025 (48)
- March 2025 (54)
- February 2025 (51)
- January 2025 (52)
- December 2024 (55)
- November 2024 (64)
- October 2024 (82)
- September 2024 (69)
- August 2024 (55)
- July 2024 (64)
- June 2024 (54)
- May 2024 (73)
- April 2024 (59)
- March 2024 (49)
- February 2024 (57)
- January 2024 (58)
- December 2023 (56)
- November 2023 (59)
- October 2023 (67)
- September 2023 (136)
- August 2023 (131)
- July 2023 (129)
- June 2023 (128)
- May 2023 (140)
- April 2023 (121)
- March 2023 (168)
- February 2023 (155)
- January 2023 (152)
- December 2022 (136)
- November 2022 (158)
- October 2022 (146)
- September 2022 (148)
- August 2022 (169)
- July 2022 (124)
- June 2022 (124)
- May 2022 (130)
- April 2022 (116)
- March 2022 (155)
- February 2022 (124)
- January 2022 (120)
- December 2021 (117)
- November 2021 (139)
- October 2021 (130)
- September 2021 (138)
- August 2021 (110)
- July 2021 (110)
- June 2021 (60)
- May 2021 (127)
- April 2021 (122)
- March 2021 (156)
- February 2021 (154)
- January 2021 (133)
- December 2020 (126)
- November 2020 (159)
- October 2020 (169)
- September 2020 (181)
- August 2020 (147)
- July 2020 (172)
- June 2020 (158)
- May 2020 (177)
- April 2020 (188)
- March 2020 (234)
- February 2020 (212)
- January 2020 (164)
- December 2019 (107)
- November 2019 (131)
- October 2019 (145)
- September 2019 (123)
- August 2019 (112)
- July 2019 (93)
- June 2019 (82)
- May 2019 (94)
- April 2019 (88)
- March 2019 (78)
- February 2019 (77)
- January 2019 (71)
- December 2018 (37)
- November 2018 (85)
- October 2018 (108)
- September 2018 (110)
- August 2018 (135)
- July 2018 (140)
- June 2018 (118)
- May 2018 (113)
- April 2018 (64)
- March 2018 (96)
- February 2018 (82)
- January 2018 (92)
- December 2017 (62)
- November 2017 (100)
- October 2017 (105)
- September 2017 (97)
- August 2017 (101)
- July 2017 (104)
- June 2017 (155)
- May 2017 (135)
- April 2017 (113)
- March 2017 (138)
- February 2017 (150)
- January 2017 (127)
- December 2016 (90)
- November 2016 (135)
- October 2016 (149)
- September 2016 (135)
- August 2016 (48)
- July 2016 (52)
- June 2016 (54)
- May 2016 (52)
- April 2016 (24)
- October 2014 (8)
- April 2012 (2)
- December 2011 (2)
- November 2011 (10)
- October 2011 (9)
- September 2011 (9)
- August 2011 (3)
Calendar
Recent Posts
- RESULTS of the Property118 Landlord Sentiment Survey: Q3 2026
- Government launches Awaab’s Law consultation for private rented sector
- Government fails to explain how landlord privacy will be protected under PRS Database
- Clearsprings’ asylum accommodation profits: are landlords getting a fair deal?
- Housing benefit changes will help thousands claims government
