Giving Up Equity Can Feel Like a Risk. Our Repeat Landlords Tell a Different Story.
 admin


Property118
Giving Up Equity Can Feel Like a Risk. Our Repeat Landlords Tell a Different Story.
When landlords first speak to us about selling, one of the biggest questions is understandably price.
Landlord Sales Agency doesn’t promise every seller the highest possible theoretical value for their property. Instead, we agree the amount they are happy to receive and use the equity above that figure to create a sale: finding the right buyer, solving problems with tenants, keeping transactions moving and covering many of the costs that would otherwise come out of the landlord’s pocket.
For someone who has spent years building equity, agreeing to accept less than the full vacant-possession value can understandably feel like a big decision.
But there is one thing that perhaps says more about whether landlords think it is worthwhile than anything we could say ourselves. They come back. Time and time again.
Many of the landlords we work with are experienced property investors who have owned rental properties for years, benefited from substantial capital growth and are now choosing to release some or all of that equity on their own terms.
They know what their properties are worth. They also know what their time is worth, what an empty property costs and how quickly a seemingly straightforward sale can become anything but straightforward.
One Landlord. Seven Properties. Plenty Of Different Problems.
One Manchester landlord first came to us in 2021 when he was beginning to sell off part of a long-held portfolio.
His first property had a tenant who had already found somewhere else to live. Rather than wait until it was empty before starting the sales process, we contacted the tenants and by working with them instead of around them, we were able to market the property immediately. We found a cash buyer who was happy to secure the sale with a non-refundable deposit and coordinated completion around the tenant’s move.
We completed in 64 days, he received his agreed £115,000 and the property was only empty for 2 weeks so he collected rent for the rest of the period.
Our sellers walk away with 85 – 90 % of the property’s vacant possession value but giving up equity on paper didn’t necessarily mean giving up money in the bank.
On paper, accepting £115,000 against an estimated £130,000 open-market value might look like giving up £15,000 in equity. But properties don’t usually sell for their full asking price.
If a conventional sale achieved around 95% of asking price, that £130,000 becomes £123,500. Take off around £5,000 in agency and legal costs, plus £3,300–£4,950 in lost rent and an estimated £1,200–£1,800 in basic costs if the property stood empty for six to nine months, and the seller could actually have ended up with LESS left over than he received from us.
Even if he received 100% of the asking price, the amount left in the bank after all fees and costs are calculated would be in the region of £118,000–£120,000.
That’s not a lot more for a HUGE difference in time and risk.
The seller obviously thought the trade-off was good value. Since that first property, we have now dealt with six more of his properties – and they certainly haven’t all been as straightforward as the first.
We’ve sold properties with tenants remaining in situ and properties where tenants were preparing to leave. We’ve worked around tenants who were difficult to contact or reluctant to provide access, found replacement buyers when sales fell through and negotiated solutions to survey problems rather than allowing them to derail transactions.
During the course of the sales, we’ve acted as mediators to settle disputes and used our contacts to find solutions to stop sales collapsing. We’ve chased councils and helped tenants move to negate the need for bailiffs. We’ve tracked down missing paperwork, arranged builders, surveyors and inspectors to satisfy concerns and resolve issues.
These are the types of problems that cause sales to collapse when they’re discovered too late or not resolved quickly enough.
With high street sales, these sorts of problems are usually left to the seller or their solicitor to solve – when you sell through Landlord Sales agency, we take all that off your shoulders. We manage the whole process from listing to completion and make it our responsibility to solve any problem at every stage.
Our Manchester seller is not an isolated example. We have repeat clients all over the country and their business accounts for a significant percentage of our sales.
Experienced Landlords Understand the Difference
Although we can certainly help ALL seller find solution to any issue they might have whether that is in relation to the property, their tenants, timing or cash flow, the majority of landlords who come back to us are not distressed sellers and they haven’t run out of options.
Most have owned property for decades, they’ve made good returns, built substantial equity and they have simply reached the point in their life and their business where they want to access some of their wealth tied into their properties without the process of releasing it to become another difficult job to deal with.
Some sell one property and retain the rest. Others gradually reduce their portfolios over several years. Some use the released equity elsewhere.
We Don’t Expect You to Take Our Word for It
Every company says its service is good. Repeat business is proof it’s the best.
A landlord who uses us once has seen the numbers. They’ve seen what they received, what we received and exactly what we did to get the property sold.
When that same landlord comes back with a second, third or seventh property, we think that’s a considerably more useful endorsement than anything we could put in an advert.
It doesn’t mean accepting less than vacant-possession value will be right for every landlord or every property. It means there is another way to look at the decision.
Rather than asking “How much equity am I giving up?” ask “What is that equity buying me?”
If it buys a buyer, keeps the rent coming in for most of the sales process, helps a tenant move without a lengthy possession battle, solves problems as they arise and gets the equity you do want released into your bank account sooner, it may prove to be money very well used.
Find Out What Your Options Look Like
If you’re considering selling one property, part of a portfolio or exiting completely, talk to us before you talk to your tenant or start down the route of obtaining vacant possession.
Once you start down the possession-for-sale route, changing your mind can have serious consequences, including restrictions on re-letting, substantial fines and potentially a Rent Repayment Order.
There’s no obligation to proceed with our service and no false promises to win your business – just straight-talking, honest opinion based on recent sales of similar properties in the same areas as those you want to sell.
We’ll look at the property, the tenancy, what you want to achieve, then tell you what we believe we can do to help you leave the PRS on your terms.
If you’re happy with the amount you’ll receive, we’ll take care of the hard work from there – including working with your tenants, finding the right buyer and solving the problems that stand between you and completion.
No pressure to sell. Just the opportunity to see whether putting a little of your equity to work could make releasing the rest considerably easier.
Contact us today and your property sale could be complete before Xmas.
(function(){var el=document.getElementById(“ts-607776b5-3f7b-431c-b5cc-fc304603fee3″);if(!el)return;var b=document.body,h=document.documentElement;var dark=b.classList.contains(“dark-mode”)||b.classList.contains(“dark”)||b.classList.contains(“night-mode”)||h.classList.contains(“dark”);if(!dark){var bg=window.getComputedStyle(b).backgroundColor,m=bg.match(/d+/g);if(m)dark=(m[0]*0.299+m[1]*0.587+m[2]*0.114)<128;}el.setAttribute("data-theme",dark?"dark":"light");if(window.turnstile&&el.childElementCount===0){try{window.turnstile.render(el,{sitekey:el.getAttribute("data-sitekey"),theme:el.getAttribute("data-theme")});}catch(e){}}})();
(function(){
var uid = “crm-form-ba09a29b”;
var form = document.getElementById(uid + ‘-form’);
var wrap = document.getElementById(uid);
var msg = wrap.querySelector(‘.crm-message’);
var totalPages = 1;
var curPage = 0;
// ── Conditional logic ────────────────────────────────────────────────
var condMap = {};
function getFieldValue(fieldId) {
var els = form.querySelectorAll(‘[name=”‘ + fieldId + ‘”], [name=”‘ + fieldId + ‘[]”]’);
if (!els.length) return ”;
var first = els[0];
if (first.type === ‘checkbox’ || first.type === ‘radio’) {
var checked = [];
els.forEach(function(el){ if (el.checked) checked.push(el.value); });
return checked.join(‘,’);
}
return first.value;
}
function evalRule(rule) {
var val = getFieldValue(rule.fieldId);
var cmp = rule.value;
switch (rule.operator) {
case ‘is': return val === cmp;
case ‘isnot': return val !== cmp;
case ‘greaterthan': return parseFloat(val) > parseFloat(cmp);
case ‘lessthan': return parseFloat(val) < parseFloat(cmp);
case 'contains': return val.indexOf(cmp) !== -1;
case 'startswith': return val.indexOf(cmp) === 0;
case 'endswith': return val.slice(-cmp.length) === cmp;
default: return false; // fail closed — mirror the CRM shared matcher
}
}
function applyConditionals() {
Object.keys(condMap).forEach(function(fieldId) {
var cond = condMap[fieldId];
var rules = cond.rules || [];
var match = cond.logicType === 'any'
? rules.some(evalRule)
: rules.every(evalRule);
var show = cond.actionType === 'show' ? match : !match;
var wrapper = form.querySelector('[data-field-id="' + fieldId + '"]');
if (!wrapper) {
var el = form.querySelector('[name="' + fieldId + '"], [name="' + fieldId + '[]"]');
if (el) wrapper = el.closest('.crm-field, .crm-half');
}
if (wrapper) wrapper.style.display = show ? '' : 'none';
});
}
form.addEventListener('change', applyConditionals);
form.addEventListener('input', applyConditionals);
applyConditionals();
// ── Required-field validation (Next + Submit) ────────────────────────
// Validate from the form's field config (id + type), NOT the [required]
// HTML attribute: a checkbox group can't carry a meaningful `required`
// (native means "tick every box"), so attribute checks skip it — which is
// why empty checkbox questions slipped past Next straight to submit.
var crmRequired = [{"id":"c364951b-ecb0-4a12-bfa4-9dbe564310e8","type":"name","label":"Name"},{"id":"910107df-b8a8-4541-879f-541cef9449e4","type":"email","label":"Email"},{"id":"3b317ed9-d327-4fe2-b92e-67efede67e6d","type":"phone","label":"Phone"},{"id":"c6fae2f0-c335-452b-aa03-2cc066163d71","type":"textarea","label":"Please give us details of how we can help and the properties in question"},{"id":"34c27d9f-b3d1-4a6d-b720-24000e9fa468","type":"checkbox","label":"Privacy Policy"}];
function crmWrapper(id) {
var w = form.querySelector('[data-field-id="' + id + '"]');
if (!w) { var el = form.querySelector('[name="' + id + '"], [name="' + id + '[]"]'); if (el) w = el.closest('.crm-field, .crm-half'); }
return w;
}
function crmFilled(fld) {
// The [name^="id["] arm catches composite fields. A name renders as id[first] /
// id[last] and an address as id[street] / id[city] / …, none of which match
// the two exact-name selectors – so els came back empty, the !els.length guard
// below returned true, and the field counted as filled. With novalidate on the
// form the browser's own required check is off too, so a required Name field
// could be left completely blank and both Next and Submit went through.
var els = form.querySelectorAll('[name="' + fld.id + '"], [name="' + fld.id + '[]"], [name^="' + fld.id + '["]');
if (!els.length) return true;
// Decide on what is actually RENDERED, not the declared type. A `product`
// field is choices (radio/checkbox) for a priced list but a single amount
// box for a user-defined price — and testing that box for .checked, which
// a text input never has, meant a required product field could never be
// satisfied. An invoice or "Request For Payment" form was unsubmittable:
// the payer typed an amount, hit Submit, and got "Please select at least
// one option." under the box, every time.
var checkable = Array.prototype.filter.call(els, function (el) {
return el.type === 'checkbox' || el.type === 'radio';
});
if (checkable.length) { return checkable.some(function (el) { return el.checked; }); }
if (['checkbox','radio','consent'].indexOf(fld.type) !== -1) { return false; }
// Test the sub-inputs the renderer actually marked required – a name field puts
// `required` on both first and last, an address field on none of its six – and
// fall back to the first input when nothing is marked, which is the existing
// single-input behaviour unchanged.
var reqEls = Array.prototype.filter.call(els, function (el) { return el.hasAttribute('required'); });
// Repeaters name their sub-inputs '[][]’, so the prefix arm above
// collects EVERY rendered row. Demanding all of them be filled means one blank
// extra row – added by mistake, or rendered by settings.minRows – blocks Next and
// Submit with a generic message on the wrapper. Only the first row is required.
var firstRow = form.querySelector(‘[data-field-id=”‘ + fld.id + ‘”] .crm-repeater-row’);
if (firstRow) {
reqEls = Array.prototype.filter.call(reqEls, function (el) { return firstRow.contains(el); });
}
var toTest = reqEls.length ? reqEls : [els[0]];
return Array.prototype.every.call(toTest, function (el) { return (el.value || ”).trim() !== ”; });
}
function crmFirstInvalid(pageIdx) {
for (var i = 0; i < crmRequired.length; i++) {
var fld = crmRequired[i]; var w = crmWrapper(fld.id);
if (!w) continue;
if (w.style.display === 'none') continue;
if (pageIdx != null) { var pd = w.closest('[data-page]'); if (!pd || parseInt(pd.getAttribute('data-page')) !== pageIdx) continue; }
if (!crmFilled(fld)) return fld;
}
return null;
}
// Shows the error in a red box UNDER the field, matching the form's own
// .crm-message error styling, and scrolls to it.
function crmMarkError(w, text) {
if (!w) return;
var e = w.querySelector('.crm-inline-error');
if (!e) { e = document.createElement('div'); e.className = 'crm-inline-error'; w.appendChild(e); }
e.style.cssText = 'background:#fee2e2;color:#991b1b;padding:.55rem .75rem;border-radius:4px;margin-top:.4rem;font-size:.9rem';
e.textContent = text || 'Please answer this before continuing.';
}
function crmClearError(w) { if (!w) return; var e = w.querySelector('.crm-inline-error'); if (e) e.parentNode.removeChild(e); }
function crmReportInvalid(fld) {
var w = crmWrapper(fld.id);
// Match the message to what the visitor is actually looking at — an amount
// box should not be told to "select an option".
var els = form.querySelectorAll('[name="' + fld.id + '"], [name="' + fld.id + '[]"]');
var hasChoices = Array.prototype.some.call(els, function (el) {
return el.type === 'checkbox' || el.type === 'radio';
});
var t;
if (fld.type === 'product' && !hasChoices) { t = 'Please enter an amount.'; }
else if (['checkbox','product'].indexOf(fld.type) !== -1) { t = 'Please select at least one option.'; }
else if (fld.type === 'radio') { t = 'Please choose an option.'; }
else { t = 'Please fill this in.'; }
crmMarkError(w, t);
if (w && w.scrollIntoView) w.scrollIntoView({ behavior: 'smooth', block: 'center' });
}
form.addEventListener('change', function(e){ var w = e.target && e.target.closest ? e.target.closest('.crm-field, .crm-half, [data-field-id]') : null; if (w) crmClearError(w); });
form.addEventListener('input', function(e){ var w = e.target && e.target.closest ? e.target.closest('.crm-field, .crm-half, [data-field-id]') : null; if (w) crmClearError(w); });
// ── Multi-page navigation ────────────────────────────────────────────
// ── Submit ────────────────────────────────────────────────────────────
var submitBtn = form.querySelector('button[type=submit]');
var btnText = submitBtn ? submitBtn.textContent : 'Submit';
var crmApiUrl = "https://crm-api.property118.com";
function collectFormData() {
var data = {};
for (var j = 0; j < form.elements.length; j++) {
var el = form.elements[j];
if (!el.name) continue;
if (el.type === 'file') continue; // handled by uploadFiles()
if (el.type === 'radio' && !el.checked) continue;
if (el.type === 'checkbox') {
if (!el.checked) continue;
var k = el.name.replace('[]','');
data[k] = data[k] ? data[k].concat([el.value]) : [el.value];
} else {
data[el.name] = el.value;
}
}
// Repeater fields: sub-inputs are named "[][]”.
// Group those flat keys into an array of row objects under the repeater
// id. Plain fields, checkbox “[]” arrays and single-bracket composites
// (name[first], address[city]) don’t match the double-bracket pattern, so
// ordinary submissions are unchanged.
var _repRe = /^(.+?)[(d+)][(.+)]$/;
var _repIds = {};
Object.keys( data ).forEach( function ( key ) {
var m = key.match( _repRe );
if ( ! m ) { return; }
var rid = m[1], row = parseInt( m[2], 10 ), sub = m[3];
_repIds[ rid ] = true;
if ( ! Array.isArray( data[ rid ] ) ) { data[ rid ] = []; }
if ( ! data[ rid ][ row ] || typeof data[ rid ][ row ] !== ‘object’ ) { data[ rid ][ row ] = {}; }
data[ rid ][ row ][ sub ] = data[ key ];
delete data[ key ];
} );
Object.keys( _repIds ).forEach( function ( rid ) {
if ( Array.isArray( data[ rid ] ) ) {
data[ rid ] = data[ rid ].filter( function ( r ) { return r && typeof r === ‘object'; } );
}
} );
// GF auto-substituted {user_agent} / {referer} on hidden fields
// at render time. We do the equivalent right before submit so
// fields whose default value carries these placeholders
// resolve to the browser’s actual values rather than being
// stored as literal “{user_agent}” / “{referer}” strings.
// The last ARTICLE the visitor read (set client-side on post views by
// P118_Article_Views). Used to attribute the enquiry to the article
// even after navigating away or with a stripped/absent referer.
var lastPost = ”;
try {
var lpm = document.cookie.match(/(?:^|;s*)p118_last_post=([^;]+)/);
if (lpm) lastPost = decodeURIComponent(lpm[1]);
} catch (e) {}
var subs = {
‘{user_agent}': navigator.userAgent || ”,
// Prefer the last article read; fall back to the (lossy) HTTP referer.
‘{referer}': lastPost || document.referrer || ”,
‘{last_post}': lastPost || ”,
‘{embed_url}': window.location.href || ”,
};
for (var name in data) {
if (!data.hasOwnProperty(name)) continue;
var v = data[name];
if (typeof v !== ‘string’) continue;
for (var tag in subs) {
if (v.indexOf(tag) !== -1) v = v.split(tag).join(subs[tag]);
}
data[name] = v;
}
// Agent/BDM attribution — read LIVE so it works even on a fully cached
// page (the browser always sees the real URL + cookie). URL ?ataid=/?cid=
// first, then the 30-day agent_id/cid cookies set by atat-tracking.php.
var _qp = new URLSearchParams(window.location.search);
var _ataid = _qp.get(‘ataid’) || (document.cookie.match(/(?:^|;s*)agent_id=([^;]+)/) || [])[1] || ”;
var _cid = _qp.get(‘cid’) || (document.cookie.match(/(?:^|;s*)cid=([^;]+)/) || [])[1] || ”;
if (_ataid) data.agent_id = decodeURIComponent(_ataid);
if (_cid) data.bdm_id = decodeURIComponent(_cid);
// Which page the form was actually on. Read live for the same reason
// as the attribution above: on a cached page the server has no idea
// which URL it is being served as, but the browser always does.
data._sourceUrl = window.location.href;
return data;
}
function uploadFiles(data) {
var fileInputs = form.querySelectorAll(‘input[type=file][data-crm-file-field]’);
var uploads = [];
fileInputs.forEach(function(el) {
if (!el.files || !el.files[0]) return;
var fd = new FormData();
fd.append(‘file’, el.files[0]);
var fieldName = el.name;
uploads.push(
fetch(crmApiUrl + ‘/public/forms/’ + “08ceeaae-4809-444e-ba0f-88da5836c463″ + ‘/upload’, { method: ‘POST’, body: fd })
.then(function(r) {
if (!r.ok) throw new Error(‘File upload failed (‘ + r.status + ‘)’);
return r.json();
})
.then(function(res) {
if (res.path) data[fieldName] = res.path;
else throw new Error(res.error || ‘File upload failed’);
})
);
});
return Promise.all(uploads).then(function() { return data; });
}
function submitFormData(data) {
var body = new FormData();
body.append(‘action’, ‘p118_crm_submit’);
body.append(‘form_id’, “08ceeaae-4809-444e-ba0f-88da5836c463″);
body.append(‘data’, JSON.stringify(data));
// Embed-page context for GF-style merge tags ({embed_url},
// {embed_post:post_title}, {embed_post:ID}). Captured PHP-side
// at render time, then echoed to JS so the submit fetch can
// forward to V2 as request headers.
body.append(‘embed_url’, “”);
body.append(‘embed_post_id’, “0”);
body.append(‘embed_post_title’, “”);
return fetch(“https://www.property118.com/wp-admin/admin-ajax.php”, { method: ‘POST’, body: body, credentials: ‘same-origin’ })
.then(function(r){ return r.json(); })
.then(function(res){
var p = res.data || res;
if (p && p.success) {
if (p.confirmationType === ‘form’ && p.nextFormId) {
return swapInNextForm(p.nextFormId, p.prefill || {});
}
if (p.confirmationType === ‘redirect’ && p.confirmationRedirectUrl) {
window.location.href = p.confirmationRedirectUrl;
} else {
form.style.display = ‘none';
msg.className = ‘crm-message success';
msg.innerHTML = p.confirmationMessage || ‘Thank you for your submission.';
// Carry the calculator’s own results across. A calculator form
// renders its figures into [data-iht-results] as the visitor
// types; hiding the form hid those too, so the completion
// screen went blank and the visitor lost what they had just
// worked out. Nothing happens on forms without that element.
var resultsEl = form.querySelector(‘[data-iht-results]’);
if (resultsEl && resultsEl.innerHTML.trim()) {
var carried = document.createElement(‘div’);
carried.className = ‘crm-message-results';
carried.innerHTML = resultsEl.innerHTML;
msg.appendChild(carried);
}
// Download link for a generated report, present only when the
// API filed the PDF before responding. Built through the DOM
// rather than concatenated into innerHTML so the URL cannot
// inject markup.
if (p.reportDownloadUrl) {
var dlWrap = document.createElement(‘p’);
dlWrap.className = ‘crm-report-download';
var dl = document.createElement(‘a’);
dl.className = ‘crm-report-button';
// Building through the DOM stops markup injection but not a
// javascript: URL, which would run in this origin the moment
// the submitter clicks the button.
dl.href = /^https?:///i.test(String(p.reportDownloadUrl)) ? p.reportDownloadUrl : ‘#';
dl.target = ‘_blank';
dl.rel = ‘noopener noreferrer';
dl.textContent = ‘Download your report (PDF)';
dlWrap.appendChild(dl);
msg.appendChild(dlWrap);
}
msg.style.display = ‘block';
if (msg.scrollIntoView) {
msg.scrollIntoView({ behavior: ‘smooth’, block: ‘start’ });
}
}
} else {
throw new Error((p && p.error) || ‘Submission failed.’);
}
});
}
// Replace this whole form widget with another form, rendered server-side
// with the carried-over values seeded in. Inline injected via
// innerHTML won’t run, so we re-create each script node to execute it
// (this is what wires up the new form’s submit / conditional logic).
function swapInNextForm(nextFormId, prefill) {
var rbody = new FormData();
rbody.append(‘action’, ‘p118_crm_render_form’);
rbody.append(‘form_id’, nextFormId);
rbody.append(‘prefill’, JSON.stringify(prefill || {}));
return fetch(“https://www.property118.com/wp-admin/admin-ajax.php”, { method: ‘POST’, body: rbody, credentials: ‘same-origin’ })
.then(function(r){ return r.json(); })
.then(function(res2){
var pd = res2.data || res2;
if (!pd || !pd.html) { throw new Error((pd && pd.error) || ‘Could not load the next form.’); }
var frag = document.createElement(‘div’);
frag.innerHTML = pd.html;
var parent = wrap.parentNode;
var nodes = [];
while (frag.firstChild) {
var node = frag.firstChild;
parent.insertBefore(node, wrap);
nodes.push(node);
}
parent.removeChild(wrap);
function reexec(old) {
var s = document.createElement(‘script’);
for (var a = 0; a < old.attributes.length; a++) {
s.setAttribute(old.attributes[a].name, old.attributes[a].value);
}
if (!old.src) { s.textContent = old.textContent; }
old.parentNode.replaceChild(s, old);
}
nodes.forEach(function(n){
if (n.tagName === 'SCRIPT') { reexec(n); }
else if (n.querySelectorAll) {
var scripts = n.querySelectorAll('script');
for (var k = 0; k < scripts.length; k++) { reexec(scripts[k]); }
}
});
var first = nodes[0];
try { if (first && first.scrollIntoView) first.scrollIntoView({ behavior: 'smooth', block: 'start' }); } catch (e) {}
});
}
form.addEventListener('submit', function(e){
e.preventDefault();
// Validate required fields before submitting. Next only guards the pages
// before it, so the final page (and single-page forms) are checked here;
// jump to the first page that has a problem.
var vbad0 = crmFirstInvalid(null);
if (vbad0) { crmReportInvalid(vbad0); return; }
var data = collectFormData();
if (submitBtn) { submitBtn.disabled = true; submitBtn.textContent = 'Processing…'; }
msg.style.display = 'none';
// Standard form (no payment)
uploadFiles(data)
.then(function(d) { return submitFormData(d); })
.catch(function(err){
resetTurnstile();
if (submitBtn) { submitBtn.disabled = false; submitBtn.textContent = btnText; }
msg.className = 'crm-message error';
msg.textContent = err.message;
msg.style.display = 'block';
});
});
// ── Repeater fields (add / remove rows) ──────────────────────────
form.querySelectorAll( '.crm-repeater' ).forEach( function ( rep ) {
var rowsWrap = rep.querySelector( '.crm-repeater-rows' );
var tpl = rep.querySelector( '.crm-repeater-template' );
var addBtn = rep.querySelector( '.crm-repeater-add' );
if ( addBtn && tpl && rowsWrap ) {
addBtn.addEventListener( 'click', function () {
var idx = parseInt( rep.getAttribute( 'data-next-index' ) || '1', 10 );
var tmp = document.createElement( 'div' );
tmp.innerHTML = tpl.innerHTML.split( '__ROW__' ).join( idx );
var row = tmp.firstElementChild;
if ( ! row ) { return; }
row.setAttribute( 'data-row', idx );
rowsWrap.appendChild( row );
rep.setAttribute( 'data-next-index', idx + 1 );
rep.dispatchEvent( new CustomEvent( 'crm-repeater-change', { bubbles: true } ) );
} );
}
if ( rowsWrap ) {
rowsWrap.addEventListener( 'click', function ( e ) {
var btn = e.target.closest ? e.target.closest( '.crm-repeater-remove' ) : null;
if ( ! btn ) { return; }
if ( rowsWrap.querySelectorAll( '.crm-repeater-row' ).length <= 1 ) { return; }
var r = btn.closest( '.crm-repeater-row' );
if ( r ) { r.remove(); }
rep.dispatchEvent( new CustomEvent( 'crm-repeater-change', { bubbles: true } ) );
} );
}
} );
})();
The post Giving Up Equity Can Feel Like a Risk. Our Repeat Landlords Tell a Different Story. appeared first on Property118.
View Full Article: Giving Up Equity Can Feel Like a Risk. Our Repeat Landlords Tell a Different Story.
HMO planning refusals have doubled – where are tenants supposed to live
Property118
HMO planning refusals have doubled – where are tenants supposed to live
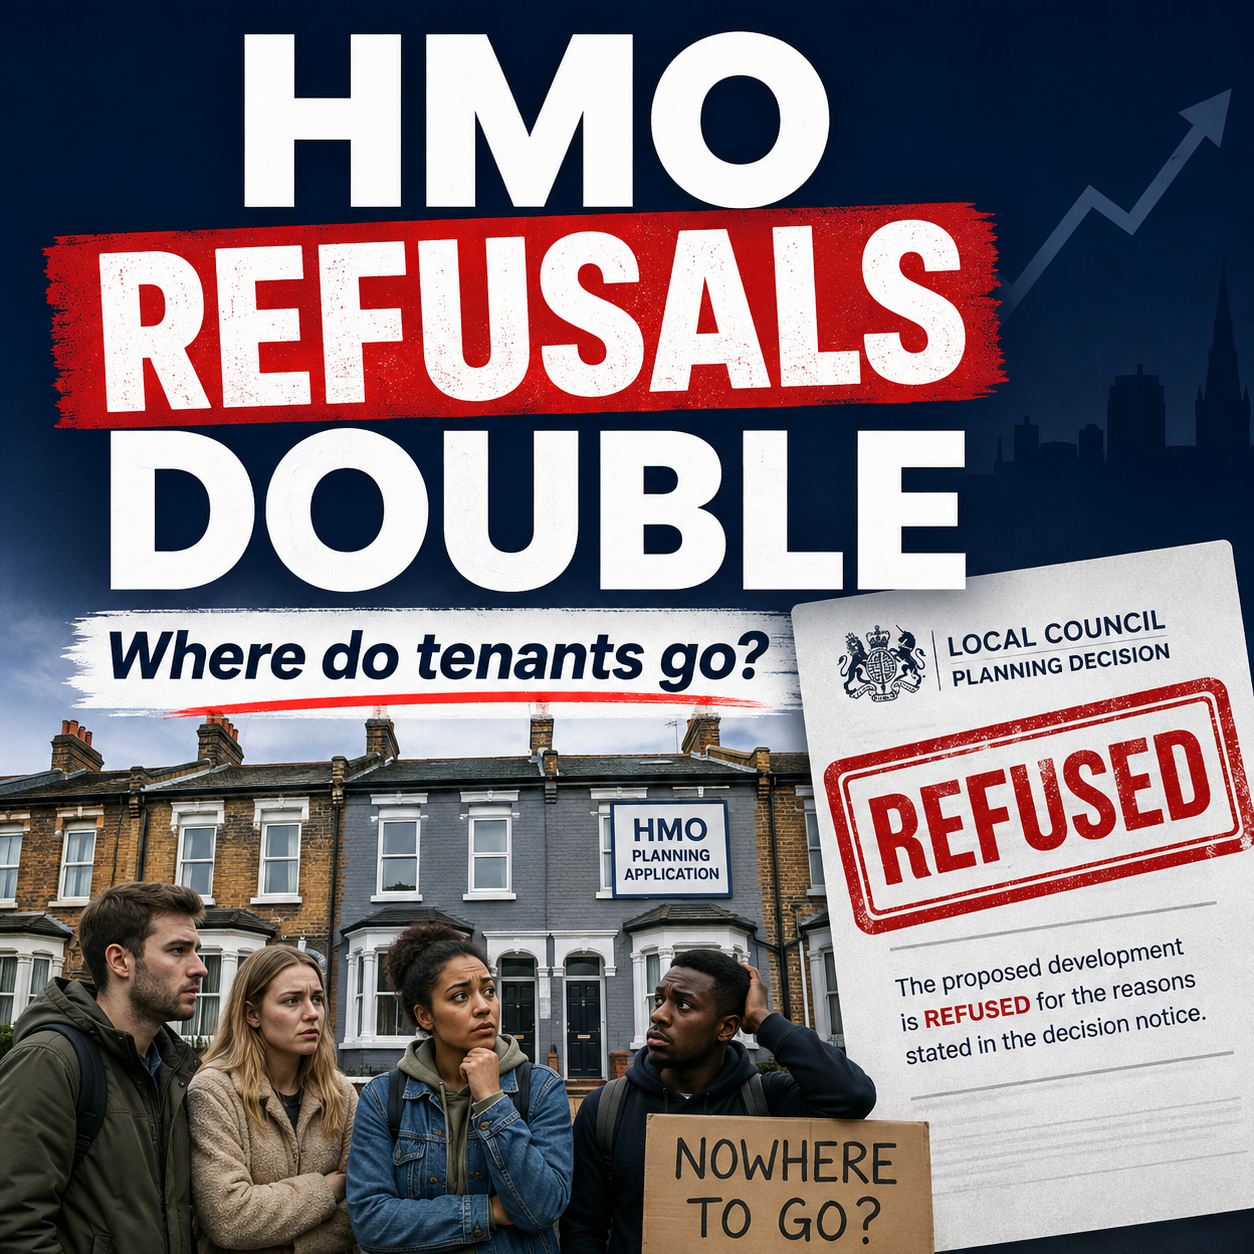
Councils refused 1,203 HMO planning applications in 2025. In 2021, the figure was 590.
There is an important caveat. The number of applications being decided also increased sharply, from 1,848 to 3,454 across the same 144 English councils. Therefore, councils have not suddenly become twice as likely to refuse an HMO application. The approval rate fell from 68.1% to 65.2%.
Even so, the practical result is that 613 more HMO applications were refused in 2025 than four years earlier.
Those refusals did not make the people looking for affordable rooms disappear. They merely prevented more of those rooms from being provided legally.
That is the part of the story councils rarely seem willing to confront.
An HMO is somebody’s home
HMO has become one of those phrases that immediately sets off alarm bells in local council meetings.
We hear about parking, bins, noise, overcrowding and the loss of family homes. Some of those concerns will be perfectly legitimate. Badly designed HMOs should not be approved and badly managed HMOs should not be allowed to continue operating.
However, not every HMO is a cramped house run by a rogue landlord.
A well-designed and properly managed HMO can provide decent accommodation for people who cannot afford, or do not want, an entire flat to themselves. That includes students, young professionals, key workers, people relocating for work, couples separating and those simply trying to get back on their feet.
For many of them, the realistic choice is not between an HMO room and a spacious one-bedroom flat.
It is between an HMO room, an unaffordable flat, a long commute, somebody’s sofa or whatever informal arrangement they can find.
Councils can refuse the planning application, but they cannot regulate that demand out of existence.
Article 4 is changing the commercial calculation
In many parts of England, the conversion of a normal C3 dwelling into a small C4 HMO for three to six unrelated occupiers can take place under permitted development rights.
An Article 4 Direction removes that right within the area covered. The landlord must then make a full planning application and take their chances against the council’s local HMO policies.
That does not amount to an outright ban, at least not on paper.
In practice, some councils impose concentration limits that make it extremely difficult to secure permission once an arbitrary percentage has already been reached within a street or prescribed radius.
Apparently, a well-designed HMO providing six good-quality rooms can be acceptable on one side of an invisible line but unacceptable on the other because a council spreadsheet says there are already too many.
The tenants who might have occupied those rooms still need somewhere to live, of course, but that does not appear to feature prominently in the calculation.
Article 4 Directions were supposed to allow councils to deal with evidenced local problems. Increasingly, we are seeing them applied across very large areas, sometimes covering an entire town or borough.
That may be administratively convenient, but convenience is not the same as good housing policy.
If the problem is concentrated within a handful of streets, target those streets. Do not make the creation of lawful shared housing more difficult everywhere and then express surprise when rents rise or people end up in less suitable accommodation.
Landlords cannot afford to buy first and investigate later
From a landlord’s perspective, this has made planning due diligence a fundamental part of the commercial appraisal.
It is no longer enough to find a large house, calculate the room rents, obtain a refurbishment quotation and assume the numbers work.
Before exchanging contracts, the buyer needs to know whether the property is already within an Article 4 area, whether a new direction has been proposed and what the council’s local HMO policies actually say.
They also need to establish the property’s current lawful planning use.
This is particularly important where a property is being sold as an existing HMO. A licence is not the same as planning permission, and the fact that tenants have occupied the property for several years does not automatically mean the owner can prove its lawful use when challenged.
As I explained in When is an HMO not an HMO?, the issue often emerges when the landlord tries to sell or refinance.
The buyer’s solicitor asks for evidence of lawful HMO use. The lender asks the same question. Suddenly, everybody discovers that the licence, council tax records and old letting adverts do not necessarily provide the certainty they expected.
A landlord who can demonstrate that the property was already being used lawfully as a C4 HMO before an Article 4 Direction took effect may be in a very different position from somebody trying to create a new HMO today.
That distinction can affect the property’s value, mortgageability and saleability.
Restrictions may increase the value of existing lawful HMOs
There is an obvious commercial consequence whenever councils restrict new supply.
Existing lawful HMOs may become more valuable because competitors cannot easily create more of them. Demand for rooms continues, but the planning system limits the number of new rooms that can be brought to market.
That can create scarcity value, but only where the property’s planning and licensing position is clean and capable of being evidenced.
An established HMO with a clear planning history, proper licensing, sensible management records and evidence of continuous use may become an increasingly valuable asset.
An HMO bought on assumptions, with missing records and no certainty over lawful use, could become an expensive problem.
That is why landlords should not regard planning as something for the solicitor to look at shortly before completion. It should be investigated before the purchase price is agreed, because the planning position directly affects what the property can earn and what it may eventually be worth.
Refuse the bad HMOs, not the people who need them
Nobody is suggesting that councils should approve every HMO application.
Conversions that create dangerous layouts, inadequate facilities, unacceptable overcrowding or genuine harm to neighbours should be rejected. Rogue landlords should also face robust enforcement.
However, that is not an argument for treating shared housing itself as the problem.
Britain has a shortage of affordable homes. Self-contained rents are beyond the reach of a growing number of people, social housing waiting lists are enormous and councils are already spending extraordinary sums on temporary accommodation.
Against that background, making professionally managed shared housing more difficult to provide looks less like joined-up policy and more like one department passing the problem to another.
A planning committee can vote against an HMO. It cannot vote away the tenant who would have lived there.
Reject the bad conversions. Prosecute the rogues. But stop pretending that refusing lawful HMO accommodation amounts to solving a housing problem.
The tenants still need somewhere to live.
Where exactly do councils expect them to go?
Are HMO applications being refused in your area despite obvious demand for affordable rooms? Has Article 4 affected the value, purchase or refinancing of one of your properties? Please share your experiences in the comments below.
The post HMO planning refusals have doubled – where are tenants supposed to live appeared first on Property118.
View Full Article: HMO planning refusals have doubled – where are tenants supposed to live
Letting agent enforcement must improve – safeagent
Property118
Letting agent enforcement must improve – safeagent
The UK’s largest not-for-profit accreditation scheme for lettings and management agents is calling for tougher enforcement after one firm was accused of failing to return deposits to more than 100 tenants.
Safeagent made the demand after the allegations were reported by BBC News and it acknowledged the workload facing trading standards officers responsible for enforcing housing legislation.
It added that many authorities successfully pursue reported compliance failures, particularly where an agent may not belong to a client money protection or redress scheme.
Tenants placed at risk
The chief executive of safeagent, Isobel Thomson, said: “As an organisation, we have experienced instances of authorities pitching responsibility from one to the other, as appears to have happened in this case, where issues are raised regarding letting agent compliance.
“The end result is that no action is taken and consumers are placed at risk.”
She added: “We have experienced authorities failing to respond to repeated communications about agents displaying the safeagent logo, for example, as they cannot see the bigger picture of what that means for consumers i.e. that the firm is not part of a CMP Scheme or very likely a redress scheme either.
“It is not a vanity project about the use of our logo but a genuine aim of ensuring consumers are protected.”
Compliance checks questioned
Safeagent said reports of unprotected deposits should have prompted checks on whether the firm met other basic requirements, including membership of a client money protection scheme.
It also points to the National Trading Standards Property Agent Checker, which allows searches to be made for an agent’s compliance status.
The organisation also questioned whether the number of consumer reports should have led to an escalation to the National Trading Standards Letting Agency Team.
It also asked what action the national team had taken.
Budget cuts restrict enforcement
One trading standards authority told safeagent that significant budget cuts had reduced its capacity and forced it to prioritise action against set criteria.
It said misuse of logos alone no longer met its threshold, with its focus shifted towards vulnerable consumers who had been specifically targeted.
The number of complaints and detriment were also considered, while intelligence would be recorded and passed to the national letting agency team.
Safeagent is now calling on the government to ensure authorities understand the purpose of enforcement, saying a lack of joined-up action did not serve consumers well.
The post Letting agent enforcement must improve – safeagent appeared first on Property118.
View Full Article: Letting agent enforcement must improve – safeagent
L&G’s reported two-year licensing gap: could tenants really reclaim £15m?
Property118
L&G’s reported two-year licensing gap: could tenants really reclaim £15m?
A letter from Lewisham Council says the licensing application for one tenant’s home was submitted 744 days after the council’s selective licensing scheme began. Reports suggest another 314 applications connected with the same Legal & General development remain pending.
That is the striking fact behind claims that L&G could be facing a rent repayment and civil penalty exposure running beyond £15 million. However, there is an important distinction between a frightening calculation and an actual bill.
At present, I can find no published tribunal application, Rent Repayment Order, civil penalty notice or finding that L&G has committed an offence. What we appear to have is a potentially serious licensing failure, hundreds of tenants who may have grounds to bring individual claims and some extremely speculative arithmetic.
What appears to have happened?
Lewisham Council’s selective licensing scheme came into force on 1 July 2024. Applications opened on 20 May 2024 and landlords were offered an early-bird discount, so this was not a scheme introduced without warning.
A council letter dated 10 August 2026, subsequently published by the Lewisham Letter, told a tenant at the Bale & Anchor development that the licensing application for their home had been made on 15 July 2026. The council said the landlord should have held a licence from 1 July 2024 and invited the tenant to consider applying for a Rent Repayment Order.
That is a gap of 744 days.
Inside Housing Living has reported that 315 properties operated by L&G had licensing applications pending. It also reported that Lewisham Council had been unable to identify an application for the development as recently as 27 March 2026.
L&G’s response was that managing agent Urbanbubble had delegated responsibility for licensing and had been engaging with the council since 2024. It said applications had now been made for all relevant properties and remained pending. Urbanbubble did not provide a comment to Inside Housing.
A licensing delay or an application delay?
This distinction matters. Calling this a dispute about “licensing delays” risks giving landlords the wrong impression.
Under section 95 of the Housing Act 2004, a landlord has a defence once a valid licensing application has been duly made. In other words, a landlord is not ordinarily committing an offence simply because the council takes months to process the application.
The critical allegation here is that valid applications were not submitted until July 2026, nearly two years after the scheme began. If that is correct, blaming the length of the council’s processing queue would miss the point.
There may still be facts that have not entered the public domain. For example, L&G or Urbanbubble might produce evidence of earlier applications, incorrect council guidance, failed payment attempts or technical problems with the application system. Those details could make an enormous difference. On the currently published facts, however, the concern is not that licences took too long to issue. It is that the applications may have been made too late.
Where does the £15 million figure come from?
One tenant reportedly pays £1,820 a month. Multiplying that rent by 12 months and approximately 300 flats produces £6.55 million. Using all 315 reported applications would produce £6.88 million.
A further £9 million has apparently been added by multiplying 300 properties by the former maximum civil penalty of £30,000. Combining those two figures creates the eye-catching claim that the total exposure could exceed £15 million.
What the £15 million figure assumes
- Approximately 300 qualifying and occupied tenancies;
- every tenant bringing a claim;
- each claim being made within the applicable time limit;
- the correct L&G entity being the immediate landlord;
- no successful reasonable-excuse defence;
- the tribunal awarding 100% of the relevant rent; and
- Lewisham imposing the maximum civil penalty on every property.
None of that has happened. Rent Repayment Orders are made following individual applications to the First-tier Tribunal. They are not a class action and an award is not automatically equal to 12 months’ rent. The tribunal considers the landlord’s conduct, the tenant’s conduct, the landlord’s financial circumstances and other relevant factors.
Civil penalties are a separate enforcement tool available to the council. They are not rent repaid to tenants and should not be presented as part of a single “rent repayment bill”. The maximum civil penalty increased from £30,000 to £40,000 from 1 May 2026 for relevant offences committed under the new provisions, although the correct cap for conduct spanning that date would require case-specific legal analysis.
The £15 million figure is therefore not an amount L&G has been ordered to pay. It is a combination of hypothetical tenant awards and hypothetical maximum council penalties.
Could the Renters’ Rights Act increase the claims?
There is a further complication that deserves more attention than the headline arithmetic. Changes introduced from 1 May 2026 increased the potential Rent Repayment Order period from 12 months to 24 months.
Government guidance on the transition indicates that the old rules continue to apply to the part of an ongoing offence committed before 1 May 2026, with the new rules applying to the later period.
For a tenant who had occupied throughout the alleged licensing failure, that could create a potential claim period covering up to 12 months under the old rules, plus the period between 1 May and the date on which a valid application was made. If 15 July 2026 was the application date, the alleged offence would normally have ended on 14 July because the application day itself is protected.
That does not mean every tenant can recover that entire amount. Occupancy dates, rent paid, benefits received, the identity of the contractual landlord and the tribunal’s assessment would all affect the result. There also appears to be no reported appellate decision dealing with this precise transitional calculation, so it would be unwise to present any aggregate number as settled.
Can a corporate landlord blame its managing agent?
This may become the most important issue for other landlords. L&G says Urbanbubble had delegated responsibility for obtaining the licences. However, appointing a managing agent does not automatically give a landlord a reasonable-excuse defence.
In Aytan v Moore [2022] UKUT 27 (LC), the Upper Tribunal explained that a landlord relying on an agent would need to establish the scope of the agent’s contractual responsibility, that reliance was reasonable and why the landlord could not reasonably have kept itself informed.
An even closer comparison can be found in LDC (Ferry Lane) GP3 Ltd v Garro [2024] UKUT 40 (LC). That case involved a large institutional landlord within the Unite group and an additional licensing scheme affecting 221 HMOs. The Upper Tribunal rejected the landlord’s reasonable-excuse argument and made the practical point that a substantial professional landlord should have systems capable of identifying licensing requirements.
Six tenants in that case received just over £23,000 between them, based on 50% of the relevant net rent. That alone demonstrates why multiplying every tenancy by 100% of the maximum possible award is not a reliable forecast. It also shows that sophisticated corporate ownership does not lower the compliance standard. If anything, the tribunal may expect stronger systems and oversight.
How many L&G properties are actually involved?
The numbers being reported also need untangling. Developer Watkin Jones says the two L&G build-to-rent blocks at Bale & Anchor contain 322 homes: 138 completed in 2023 and a further 184 completed in March 2024.
Some references describe the wider development as containing 365 homes. That number includes a separate block of 43 affordable homes sold to the CBRE UK Affordable Housing Fund. It should not automatically be included in calculations concerning L&G.
We are therefore left with 322 L&G homes, 315 reportedly pending applications and no public explanation for the seven-property difference. Nor do we know how many of the 315 homes were occupied throughout the relevant periods or which company appears as landlord on each tenancy agreement.
That last point could prove critical because a Rent Repayment Order is generally pursued against the tenant’s immediate landlord, not simply whichever corporate brand appears above the development.
The real lesson for landlords
Whether the eventual exposure is £500,000, £5 million or nothing at all, this story has already exposed a compliance weakness that affects landlords of every size.
Delegating licensing to an agent is perfectly reasonable. Delegating it and never checking whether the application, supporting documents and fee were actually received is something else entirely.
A landlord’s compliance record should identify every property, every applicable licensing scheme, the application deadline, submission confirmation, payment receipt, licence conditions and renewal date. Someone within the landlord’s own organisation should verify that evidence rather than relying on an email saying the matter is “in hand”.
If a business with more than £4 billion invested in build-to-rent and over 10,000 apartments can reportedly find itself facing questions over hundreds of licence applications, smaller landlords should not assume this is merely a corporate embarrassment with no relevance to them.
The £15 million headline may be premature, but the underlying question is entirely legitimate: who was checking that the applications had actually been made?
What do you think? Should appointing a professional managing agent protect a landlord where licensing applications are submitted late, or should the landlord always be expected to verify that the job has been completed? Please share your views in the comments below.
The post L&G’s reported two-year licensing gap: could tenants really reclaim £15m? appeared first on Property118.
View Full Article: L&G’s reported two-year licensing gap: could tenants really reclaim £15m?
Why selling with tenants puts landlords in a stronger position
Property118
Why selling with tenants puts landlords in a stronger position
An empty property can put pressure on you to accept the next offer. A tenanted property keeps earning while you find the right buyer, and that buyer could even be your tenant with our help to make it possible.
Traditionally, many landlords wanting to sell have rushed out to get vacant possession, tidy the property up and put it on the open market in pursuit of the highest possible price.
But with landlords using Section 8 to sell potentially facing 12 months or more with an empty property after gaining vacant possession, and others looking for a faster alternative to waiting for possession proceedings, a growing number are deciding that squeezing every last pound from a property isn’t necessarily the same as achieving the best outcome.
That can remove months of uncertainty, the possibility of court delays and the risk that repairs, refurbishment or other unexpected costs start eating into the extra money you hoped vacant possession would produce.
While they make up a much smaller percentage of property buyers, Hamptons recently reported investors account for over 14% of all transactions in July – a key indicator that owner occupiers are more hesitant in the current market.
Many are looking for turnkey opportunities – keenly priced properties with established tenancies they can simply take over, so they collect rent from the start. Sellers who evict their tenants and speculate to accumulate may find they have made their properties less attractive to the most prolific buyers.
Perhaps though most importantly in a buyers’ market, a tenanted property can allow you to sell from a position of strength.
You’re not standing over an empty property watching another month’s costs disappear from your bank account while a buyer chips away at the price.
The property is still doing its job. Rent is still coming in and you can decide whether an offer is good enough. You’re not under the same pressure to sell quickly if the alternative is running empty property draining your cash flow for 12 months+
That choice strengthens your position as a seller.
Of course, as Rightmove and Zoopla have recently reported, sellers who do not want a sale to drag on for months or years must be realistic about the price and data from Hamptons saying 56% of investor offers were at least 10% below the asking price, support that message.
However, when you consider Zoopla recently reported that the average discount across all sales is 3.5%, the difference in price for a faster sale with significantly fewer costs and less risks is more like 6.5%
Offset that against the advantages of keeping tenants in place and collecting rent through the majority of the sales process as well as the costs you save – on redecorating, replacing worn fixtures and fittings, running empty property with council tax, insurance, utilities, security and mortgage payments coming out every month with no rent coming in – and it’s easy to see why so many landlords are choosing to relinquish some of the equity they have built up in their properties for a fast sale.
Anyone who invests in stocks and shares knows the danger of waiting for the “perfect moment” to sell. Once you’ve decided an investment no longer fits your plans, focusing on what it was once worth can keep you holding on long after you’ve decided you’d rather be out. And it can lead to much bigger losses down the line.
If an investment has increased several times over in value, the difference between extracting every last percentage point and having the money safely in the bank can become much less important.
We sell properties for 85 – 90% of their open market value. Where possible, we sell without disturbing tenants and use the equity to attract chain-free investors who can complete 56 days but, where necessary, we also use it to help tenants so that they are happy to surrender possession rather than be chased through the courts. We take our fee from it, pay the solicitors of your choice from our list of approved, independent panel solicitors and it covers all other costs like EPC certificates, listing materials etc so there are no other costs on top of that.
Of course, there’s nothing stopping sellers negotiating with buyers and tenants themselves to secure a faster sale and voluntary surrender. But that’s not all we do.
- We have a database of 30,000+ active buyers (in addition to the buyers we find advertising on Rightmove, Zoopla and through local agents) including owner-occupiers, incoming landlords, private investors and conglomerate corporations
- We collect all the information buyers and their solicitors need before they can legally complete on a transfer of landlord so your solicitors don’t have to and nothing is left to chance before a sale is agreed
- We check compliance and correct any oversight before it becomes a problem
- We secure buyers and in doing so, we cut the rate of landlord sales that fail from 51% (according to Hamptons data) to less than 5%
- We have teams of experts at our disposal to react to any issue uncovered in the process and oversee every stage from listing to completion to ensure everyone involved completes their task efficiently and the process is moved to the next stage with minimum delay
In short, finding a buyer is just the start of what we do. A huge part of the value we offer seller is in what we do after a sale is agreed to, make sure it is completed efficiently and on time.
Take a property worth £250,000. Accepting £225,000 might initially feel like giving up £25,000 of hard-earned equity.
But £25,000 isn’t necessarily the true difference between the two options. Pursuing the full vacant-possession value can mean paying for possession, lost rent, council tax, insurance, utilities, preparing the property for sale, estate agency and legal fees. Over a sale taking 10 months or more, those costs can easily reach £15,000–£20,000.
Suddenly, the difference between what ultimately reaches your bank account can be much smaller than the difference between the two headline prices – and you’re comparing two very different levels of service, risk and involvement.
With Landlord Sales Agency, you agree the amount you’re happy to receive. We then use our experience, buyer network and different routes to market to achieve more, taking our costs from the difference. In return, we manage the tenants, buyers, compliance, solicitors and sales progression and solve the problems that might otherwise delay or derail the sale.
For landlords who have already done well from a property that may no longer be right for their portfolio, equity they can use can be worth considerably more than a little extra equity tied up in a property they no longer want.
That is particularly true if an older property is approaching a period when maintenance, energy-efficiency improvements or changing compliance requirements will demand further investment.
Doing nothing isn’t necessarily the cost-free option. The question is whether the next £10,000, £20,000 or £30,000 is best invested in that property – or whether the equity already sitting in it could work harder somewhere else.
That’s really what selling from a position of strength means: not being dependent on one buyer, one route to market or one outcome.
You have choices – and because the property is still generating rent, you have the time and income to choose the one that works best for you.
Don’t wait until an empty property, rising costs or a deadline takes those choices away. Contact Landlord Sales Agency while you’re still in a position to choose how, when and to whom you sell.
(function(){var el=document.getElementById(“ts-607776b5-3f7b-431c-b5cc-fc304603fee3″);if(!el)return;var b=document.body,h=document.documentElement;var dark=b.classList.contains(“dark-mode”)||b.classList.contains(“dark”)||b.classList.contains(“night-mode”)||h.classList.contains(“dark”);if(!dark){var bg=window.getComputedStyle(b).backgroundColor,m=bg.match(/d+/g);if(m)dark=(m[0]*0.299+m[1]*0.587+m[2]*0.114)<128;}el.setAttribute("data-theme",dark?"dark":"light");if(window.turnstile&&el.childElementCount===0){try{window.turnstile.render(el,{sitekey:el.getAttribute("data-sitekey"),theme:el.getAttribute("data-theme")});}catch(e){}}})();
(function(){
var uid = “crm-form-ba09a29b”;
var form = document.getElementById(uid + ‘-form’);
var wrap = document.getElementById(uid);
var msg = wrap.querySelector(‘.crm-message’);
var totalPages = 1;
var curPage = 0;
// ── Conditional logic ────────────────────────────────────────────────
var condMap = {};
function getFieldValue(fieldId) {
var els = form.querySelectorAll(‘[name=”‘ + fieldId + ‘”], [name=”‘ + fieldId + ‘[]”]’);
if (!els.length) return ”;
var first = els[0];
if (first.type === ‘checkbox’ || first.type === ‘radio’) {
var checked = [];
els.forEach(function(el){ if (el.checked) checked.push(el.value); });
return checked.join(‘,’);
}
return first.value;
}
function evalRule(rule) {
var val = getFieldValue(rule.fieldId);
var cmp = rule.value;
switch (rule.operator) {
case ‘is': return val === cmp;
case ‘isnot': return val !== cmp;
case ‘greaterthan': return parseFloat(val) > parseFloat(cmp);
case ‘lessthan': return parseFloat(val) < parseFloat(cmp);
case 'contains': return val.indexOf(cmp) !== -1;
case 'startswith': return val.indexOf(cmp) === 0;
case 'endswith': return val.slice(-cmp.length) === cmp;
default: return false; // fail closed — mirror the CRM shared matcher
}
}
function applyConditionals() {
Object.keys(condMap).forEach(function(fieldId) {
var cond = condMap[fieldId];
var rules = cond.rules || [];
var match = cond.logicType === 'any'
? rules.some(evalRule)
: rules.every(evalRule);
var show = cond.actionType === 'show' ? match : !match;
var wrapper = form.querySelector('[data-field-id="' + fieldId + '"]');
if (!wrapper) {
var el = form.querySelector('[name="' + fieldId + '"], [name="' + fieldId + '[]"]');
if (el) wrapper = el.closest('.crm-field, .crm-half');
}
if (wrapper) wrapper.style.display = show ? '' : 'none';
});
}
form.addEventListener('change', applyConditionals);
form.addEventListener('input', applyConditionals);
applyConditionals();
// ── Required-field validation (Next + Submit) ────────────────────────
// Validate from the form's field config (id + type), NOT the [required]
// HTML attribute: a checkbox group can't carry a meaningful `required`
// (native means "tick every box"), so attribute checks skip it — which is
// why empty checkbox questions slipped past Next straight to submit.
var crmRequired = [{"id":"c364951b-ecb0-4a12-bfa4-9dbe564310e8","type":"name","label":"Name"},{"id":"910107df-b8a8-4541-879f-541cef9449e4","type":"email","label":"Email"},{"id":"3b317ed9-d327-4fe2-b92e-67efede67e6d","type":"phone","label":"Phone"},{"id":"c6fae2f0-c335-452b-aa03-2cc066163d71","type":"textarea","label":"Please give us details of how we can help and the properties in question"},{"id":"34c27d9f-b3d1-4a6d-b720-24000e9fa468","type":"checkbox","label":"Privacy Policy"}];
function crmWrapper(id) {
var w = form.querySelector('[data-field-id="' + id + '"]');
if (!w) { var el = form.querySelector('[name="' + id + '"], [name="' + id + '[]"]'); if (el) w = el.closest('.crm-field, .crm-half'); }
return w;
}
function crmFilled(fld) {
// The [name^="id["] arm catches composite fields. A name renders as id[first] /
// id[last] and an address as id[street] / id[city] / …, none of which match
// the two exact-name selectors – so els came back empty, the !els.length guard
// below returned true, and the field counted as filled. With novalidate on the
// form the browser's own required check is off too, so a required Name field
// could be left completely blank and both Next and Submit went through.
var els = form.querySelectorAll('[name="' + fld.id + '"], [name="' + fld.id + '[]"], [name^="' + fld.id + '["]');
if (!els.length) return true;
// Decide on what is actually RENDERED, not the declared type. A `product`
// field is choices (radio/checkbox) for a priced list but a single amount
// box for a user-defined price — and testing that box for .checked, which
// a text input never has, meant a required product field could never be
// satisfied. An invoice or "Request For Payment" form was unsubmittable:
// the payer typed an amount, hit Submit, and got "Please select at least
// one option." under the box, every time.
var checkable = Array.prototype.filter.call(els, function (el) {
return el.type === 'checkbox' || el.type === 'radio';
});
if (checkable.length) { return checkable.some(function (el) { return el.checked; }); }
if (['checkbox','radio','consent'].indexOf(fld.type) !== -1) { return false; }
// Test the sub-inputs the renderer actually marked required – a name field puts
// `required` on both first and last, an address field on none of its six – and
// fall back to the first input when nothing is marked, which is the existing
// single-input behaviour unchanged.
var reqEls = Array.prototype.filter.call(els, function (el) { return el.hasAttribute('required'); });
// Repeaters name their sub-inputs '[][]’, so the prefix arm above
// collects EVERY rendered row. Demanding all of them be filled means one blank
// extra row – added by mistake, or rendered by settings.minRows – blocks Next and
// Submit with a generic message on the wrapper. Only the first row is required.
var firstRow = form.querySelector(‘[data-field-id=”‘ + fld.id + ‘”] .crm-repeater-row’);
if (firstRow) {
reqEls = Array.prototype.filter.call(reqEls, function (el) { return firstRow.contains(el); });
}
var toTest = reqEls.length ? reqEls : [els[0]];
return Array.prototype.every.call(toTest, function (el) { return (el.value || ”).trim() !== ”; });
}
function crmFirstInvalid(pageIdx) {
for (var i = 0; i < crmRequired.length; i++) {
var fld = crmRequired[i]; var w = crmWrapper(fld.id);
if (!w) continue;
if (w.style.display === 'none') continue;
if (pageIdx != null) { var pd = w.closest('[data-page]'); if (!pd || parseInt(pd.getAttribute('data-page')) !== pageIdx) continue; }
if (!crmFilled(fld)) return fld;
}
return null;
}
// Shows the error in a red box UNDER the field, matching the form's own
// .crm-message error styling, and scrolls to it.
function crmMarkError(w, text) {
if (!w) return;
var e = w.querySelector('.crm-inline-error');
if (!e) { e = document.createElement('div'); e.className = 'crm-inline-error'; w.appendChild(e); }
e.style.cssText = 'background:#fee2e2;color:#991b1b;padding:.55rem .75rem;border-radius:4px;margin-top:.4rem;font-size:.9rem';
e.textContent = text || 'Please answer this before continuing.';
}
function crmClearError(w) { if (!w) return; var e = w.querySelector('.crm-inline-error'); if (e) e.parentNode.removeChild(e); }
function crmReportInvalid(fld) {
var w = crmWrapper(fld.id);
// Match the message to what the visitor is actually looking at — an amount
// box should not be told to "select an option".
var els = form.querySelectorAll('[name="' + fld.id + '"], [name="' + fld.id + '[]"]');
var hasChoices = Array.prototype.some.call(els, function (el) {
return el.type === 'checkbox' || el.type === 'radio';
});
var t;
if (fld.type === 'product' && !hasChoices) { t = 'Please enter an amount.'; }
else if (['checkbox','product'].indexOf(fld.type) !== -1) { t = 'Please select at least one option.'; }
else if (fld.type === 'radio') { t = 'Please choose an option.'; }
else { t = 'Please fill this in.'; }
crmMarkError(w, t);
if (w && w.scrollIntoView) w.scrollIntoView({ behavior: 'smooth', block: 'center' });
}
form.addEventListener('change', function(e){ var w = e.target && e.target.closest ? e.target.closest('.crm-field, .crm-half, [data-field-id]') : null; if (w) crmClearError(w); });
form.addEventListener('input', function(e){ var w = e.target && e.target.closest ? e.target.closest('.crm-field, .crm-half, [data-field-id]') : null; if (w) crmClearError(w); });
// ── Multi-page navigation ────────────────────────────────────────────
// ── Submit ────────────────────────────────────────────────────────────
var submitBtn = form.querySelector('button[type=submit]');
var btnText = submitBtn ? submitBtn.textContent : 'Submit';
var crmApiUrl = "https://crm-api.property118.com";
function collectFormData() {
var data = {};
for (var j = 0; j < form.elements.length; j++) {
var el = form.elements[j];
if (!el.name) continue;
if (el.type === 'file') continue; // handled by uploadFiles()
if (el.type === 'radio' && !el.checked) continue;
if (el.type === 'checkbox') {
if (!el.checked) continue;
var k = el.name.replace('[]','');
data[k] = data[k] ? data[k].concat([el.value]) : [el.value];
} else {
data[el.name] = el.value;
}
}
// Repeater fields: sub-inputs are named "[][]”.
// Group those flat keys into an array of row objects under the repeater
// id. Plain fields, checkbox “[]” arrays and single-bracket composites
// (name[first], address[city]) don’t match the double-bracket pattern, so
// ordinary submissions are unchanged.
var _repRe = /^(.+?)[(d+)][(.+)]$/;
var _repIds = {};
Object.keys( data ).forEach( function ( key ) {
var m = key.match( _repRe );
if ( ! m ) { return; }
var rid = m[1], row = parseInt( m[2], 10 ), sub = m[3];
_repIds[ rid ] = true;
if ( ! Array.isArray( data[ rid ] ) ) { data[ rid ] = []; }
if ( ! data[ rid ][ row ] || typeof data[ rid ][ row ] !== ‘object’ ) { data[ rid ][ row ] = {}; }
data[ rid ][ row ][ sub ] = data[ key ];
delete data[ key ];
} );
Object.keys( _repIds ).forEach( function ( rid ) {
if ( Array.isArray( data[ rid ] ) ) {
data[ rid ] = data[ rid ].filter( function ( r ) { return r && typeof r === ‘object'; } );
}
} );
// GF auto-substituted {user_agent} / {referer} on hidden fields
// at render time. We do the equivalent right before submit so
// fields whose default value carries these placeholders
// resolve to the browser’s actual values rather than being
// stored as literal “{user_agent}” / “{referer}” strings.
// The last ARTICLE the visitor read (set client-side on post views by
// P118_Article_Views). Used to attribute the enquiry to the article
// even after navigating away or with a stripped/absent referer.
var lastPost = ”;
try {
var lpm = document.cookie.match(/(?:^|;s*)p118_last_post=([^;]+)/);
if (lpm) lastPost = decodeURIComponent(lpm[1]);
} catch (e) {}
var subs = {
‘{user_agent}': navigator.userAgent || ”,
// Prefer the last article read; fall back to the (lossy) HTTP referer.
‘{referer}': lastPost || document.referrer || ”,
‘{last_post}': lastPost || ”,
‘{embed_url}': window.location.href || ”,
};
for (var name in data) {
if (!data.hasOwnProperty(name)) continue;
var v = data[name];
if (typeof v !== ‘string’) continue;
for (var tag in subs) {
if (v.indexOf(tag) !== -1) v = v.split(tag).join(subs[tag]);
}
data[name] = v;
}
// Agent/BDM attribution — read LIVE so it works even on a fully cached
// page (the browser always sees the real URL + cookie). URL ?ataid=/?cid=
// first, then the 30-day agent_id/cid cookies set by atat-tracking.php.
var _qp = new URLSearchParams(window.location.search);
var _ataid = _qp.get(‘ataid’) || (document.cookie.match(/(?:^|;s*)agent_id=([^;]+)/) || [])[1] || ”;
var _cid = _qp.get(‘cid’) || (document.cookie.match(/(?:^|;s*)cid=([^;]+)/) || [])[1] || ”;
if (_ataid) data.agent_id = decodeURIComponent(_ataid);
if (_cid) data.bdm_id = decodeURIComponent(_cid);
// Which page the form was actually on. Read live for the same reason
// as the attribution above: on a cached page the server has no idea
// which URL it is being served as, but the browser always does.
data._sourceUrl = window.location.href;
return data;
}
function uploadFiles(data) {
var fileInputs = form.querySelectorAll(‘input[type=file][data-crm-file-field]’);
var uploads = [];
fileInputs.forEach(function(el) {
if (!el.files || !el.files[0]) return;
var fd = new FormData();
fd.append(‘file’, el.files[0]);
var fieldName = el.name;
uploads.push(
fetch(crmApiUrl + ‘/public/forms/’ + “08ceeaae-4809-444e-ba0f-88da5836c463″ + ‘/upload’, { method: ‘POST’, body: fd })
.then(function(r) {
if (!r.ok) throw new Error(‘File upload failed (‘ + r.status + ‘)’);
return r.json();
})
.then(function(res) {
if (res.path) data[fieldName] = res.path;
else throw new Error(res.error || ‘File upload failed’);
})
);
});
return Promise.all(uploads).then(function() { return data; });
}
function submitFormData(data) {
var body = new FormData();
body.append(‘action’, ‘p118_crm_submit’);
body.append(‘form_id’, “08ceeaae-4809-444e-ba0f-88da5836c463″);
body.append(‘data’, JSON.stringify(data));
// Embed-page context for GF-style merge tags ({embed_url},
// {embed_post:post_title}, {embed_post:ID}). Captured PHP-side
// at render time, then echoed to JS so the submit fetch can
// forward to V2 as request headers.
body.append(‘embed_url’, “”);
body.append(‘embed_post_id’, “0”);
body.append(‘embed_post_title’, “”);
return fetch(“https://www.property118.com/wp-admin/admin-ajax.php”, { method: ‘POST’, body: body, credentials: ‘same-origin’ })
.then(function(r){ return r.json(); })
.then(function(res){
var p = res.data || res;
if (p && p.success) {
if (p.confirmationType === ‘form’ && p.nextFormId) {
return swapInNextForm(p.nextFormId, p.prefill || {});
}
if (p.confirmationType === ‘redirect’ && p.confirmationRedirectUrl) {
window.location.href = p.confirmationRedirectUrl;
} else {
form.style.display = ‘none';
msg.className = ‘crm-message success';
msg.innerHTML = p.confirmationMessage || ‘Thank you for your submission.';
// Carry the calculator’s own results across. A calculator form
// renders its figures into [data-iht-results] as the visitor
// types; hiding the form hid those too, so the completion
// screen went blank and the visitor lost what they had just
// worked out. Nothing happens on forms without that element.
var resultsEl = form.querySelector(‘[data-iht-results]’);
if (resultsEl && resultsEl.innerHTML.trim()) {
var carried = document.createElement(‘div’);
carried.className = ‘crm-message-results';
carried.innerHTML = resultsEl.innerHTML;
msg.appendChild(carried);
}
// Download link for a generated report, present only when the
// API filed the PDF before responding. Built through the DOM
// rather than concatenated into innerHTML so the URL cannot
// inject markup.
if (p.reportDownloadUrl) {
var dlWrap = document.createElement(‘p’);
dlWrap.className = ‘crm-report-download';
var dl = document.createElement(‘a’);
dl.className = ‘crm-report-button';
// Building through the DOM stops markup injection but not a
// javascript: URL, which would run in this origin the moment
// the submitter clicks the button.
dl.href = /^https?:///i.test(String(p.reportDownloadUrl)) ? p.reportDownloadUrl : ‘#';
dl.target = ‘_blank';
dl.rel = ‘noopener noreferrer';
dl.textContent = ‘Download your report (PDF)';
dlWrap.appendChild(dl);
msg.appendChild(dlWrap);
}
msg.style.display = ‘block';
if (msg.scrollIntoView) {
msg.scrollIntoView({ behavior: ‘smooth’, block: ‘start’ });
}
}
} else {
throw new Error((p && p.error) || ‘Submission failed.’);
}
});
}
// Replace this whole form widget with another form, rendered server-side
// with the carried-over values seeded in. Inline injected via
// innerHTML won’t run, so we re-create each script node to execute it
// (this is what wires up the new form’s submit / conditional logic).
function swapInNextForm(nextFormId, prefill) {
var rbody = new FormData();
rbody.append(‘action’, ‘p118_crm_render_form’);
rbody.append(‘form_id’, nextFormId);
rbody.append(‘prefill’, JSON.stringify(prefill || {}));
return fetch(“https://www.property118.com/wp-admin/admin-ajax.php”, { method: ‘POST’, body: rbody, credentials: ‘same-origin’ })
.then(function(r){ return r.json(); })
.then(function(res2){
var pd = res2.data || res2;
if (!pd || !pd.html) { throw new Error((pd && pd.error) || ‘Could not load the next form.’); }
var frag = document.createElement(‘div’);
frag.innerHTML = pd.html;
var parent = wrap.parentNode;
var nodes = [];
while (frag.firstChild) {
var node = frag.firstChild;
parent.insertBefore(node, wrap);
nodes.push(node);
}
parent.removeChild(wrap);
function reexec(old) {
var s = document.createElement(‘script’);
for (var a = 0; a < old.attributes.length; a++) {
s.setAttribute(old.attributes[a].name, old.attributes[a].value);
}
if (!old.src) { s.textContent = old.textContent; }
old.parentNode.replaceChild(s, old);
}
nodes.forEach(function(n){
if (n.tagName === 'SCRIPT') { reexec(n); }
else if (n.querySelectorAll) {
var scripts = n.querySelectorAll('script');
for (var k = 0; k < scripts.length; k++) { reexec(scripts[k]); }
}
});
var first = nodes[0];
try { if (first && first.scrollIntoView) first.scrollIntoView({ behavior: 'smooth', block: 'start' }); } catch (e) {}
});
}
form.addEventListener('submit', function(e){
e.preventDefault();
// Validate required fields before submitting. Next only guards the pages
// before it, so the final page (and single-page forms) are checked here;
// jump to the first page that has a problem.
var vbad0 = crmFirstInvalid(null);
if (vbad0) { crmReportInvalid(vbad0); return; }
var data = collectFormData();
if (submitBtn) { submitBtn.disabled = true; submitBtn.textContent = 'Processing…'; }
msg.style.display = 'none';
// Standard form (no payment)
uploadFiles(data)
.then(function(d) { return submitFormData(d); })
.catch(function(err){
resetTurnstile();
if (submitBtn) { submitBtn.disabled = false; submitBtn.textContent = btnText; }
msg.className = 'crm-message error';
msg.textContent = err.message;
msg.style.display = 'block';
});
});
// ── Repeater fields (add / remove rows) ──────────────────────────
form.querySelectorAll( '.crm-repeater' ).forEach( function ( rep ) {
var rowsWrap = rep.querySelector( '.crm-repeater-rows' );
var tpl = rep.querySelector( '.crm-repeater-template' );
var addBtn = rep.querySelector( '.crm-repeater-add' );
if ( addBtn && tpl && rowsWrap ) {
addBtn.addEventListener( 'click', function () {
var idx = parseInt( rep.getAttribute( 'data-next-index' ) || '1', 10 );
var tmp = document.createElement( 'div' );
tmp.innerHTML = tpl.innerHTML.split( '__ROW__' ).join( idx );
var row = tmp.firstElementChild;
if ( ! row ) { return; }
row.setAttribute( 'data-row', idx );
rowsWrap.appendChild( row );
rep.setAttribute( 'data-next-index', idx + 1 );
rep.dispatchEvent( new CustomEvent( 'crm-repeater-change', { bubbles: true } ) );
} );
}
if ( rowsWrap ) {
rowsWrap.addEventListener( 'click', function ( e ) {
var btn = e.target.closest ? e.target.closest( '.crm-repeater-remove' ) : null;
if ( ! btn ) { return; }
if ( rowsWrap.querySelectorAll( '.crm-repeater-row' ).length <= 1 ) { return; }
var r = btn.closest( '.crm-repeater-row' );
if ( r ) { r.remove(); }
rep.dispatchEvent( new CustomEvent( 'crm-repeater-change', { bubbles: true } ) );
} );
}
} );
})();
The post Why selling with tenants puts landlords in a stronger position appeared first on Property118.
View Full Article: Why selling with tenants puts landlords in a stronger position
MPs demand Angela Rayner U-turns on rent controls
Property118
MPs demand Angela Rayner U-turns on rent controls
MPs have written to the housing secretary Angela Rayner, urging her to reconsider the government’s refusal to introduce rent controls in England.
It comes as research commissioned by the Joseph Rowntree Foundation and undertaken by the Autonomy Institute models three rent control ideas from next year.
They are: a CPI-linked cap, a nominal freeze and a moderate system limiting rises during tenancies to CPI and increases between tenancies to CPI plus 2%.
The estimates annual savings for each tenancy by 2031 of £1,418 under a freeze, £701 with moderate controls and £130 through a CPI-linked limit.
However, news of the MPs’ letter comes a day after the Institute for Fiscal Studies found that rent controls will reduce the number of homes to rent.
MPs press Ms Rayner
The letter from 26 MPs says: “On average rent now takes 36% of a renter’s salary, rising to almost half of their pay in some areas just to keep a roof over their heads.
“With so much of people’s income going on housing, it is little wonder that a third of renters are living in poverty.”
The letter added: “The impacts don’t stop at the front door either, when rent take up such a large chunk of a pay packet you aren’t able to spend in local cafés, restaurants or shops.
“These extortionate rents are the elephant in the room when we talk about the cost of living.”
Landlord tax trade-off
Each proposed route for rent controls is paired with two tax reforms: restoring full mortgage-interest deductions by reversing Section 24 and applying National Insurance contributions to landlord property income.
Without a policy change, the model projects that the proportion of tenancies involving loss-making landlords would rise from about 10% in 2024 to 17.05% by 2031, mainly because of higher mortgage costs.
With the proposed measures, that figure would be 12.48% under a CPI cap, 14.16% with moderate controls and 15.33% following a nominal freeze.
Mean post-tax rent return on equity, excluding capital gains, is projected at 2% without reform, compared with 1.81%, 1.68% and 1.52% respectively under the three alternatives.
Government rejects controls
Ms Rayner said last month that the government was not planning to impose rent controls and pointed to protections introduced through the Renters’ Rights Act.
She also said controls had not ‘necessarily brought rents down’ elsewhere in the UK, including Scotland.
Dr Will Stronge, chief executive at the Autonomy Institute, told The Mirror: “Rent controls have often been dismissed as unworkable, but our modelling shows that a modern, well-calibrated cap paired with fair treatment of landlord costs can improve affordability for tenants without triggering the kind of landlord exodus that would leave renters worse off.”
An MHCLG spokesman said: “We have no plans to introduce rent controls.”
The post MPs demand Angela Rayner U-turns on rent controls appeared first on Property118.
View Full Article: MPs demand Angela Rayner U-turns on rent controls
Could your tenant become your buyer? How a direct sale can work for both sides
Property118
Could your tenant become your buyer? How a direct sale can work for both sides
Savills reported that 254,000 previously let homes were listed for sale in Great Britain in the twelve months to the end of March 2026, just under 700 former rentals a day and around 28 per cent above the level two years earlier. Almost all went to an estate agent. Very few of those landlords are likely to have begun by asking the person already living in the property whether they wanted to buy it.
What the vacant possession route can cost
If you want vacant possession you need Ground 1A: four months’ notice that cannot expire within the first twelve months of the tenancy, so the earliest you can serve is the end of month eight.
The restricted period will then apply. Under section 16M of the Housing Act 1988, inserted by the Renters’ Rights Act 2025, it begins on the day the notice is served and ends twelve months after the date stated in the notice as the earliest on which possession proceedings may begin.
Since that date must be at least four months after service, the minimum lock-out is sixteen months from the day of service, and it applies whether or not the tenancy continues. During it you must not re-let, grant a licence to occupy for money, or market for letting. Breach is an offence under section 16J, carrying civil penalties of up to £40,000, and a rent repayment order of up to twenty four months’ rent.
The period is fixed in length and anchored to the date you put in the notice, so serving later does not shorten it. Serve on 1 January with a possession date of 3 May and the restriction ends the following 2 May, whether you issue proceedings in May or in October. And a notice cannot be withdrawn. So it is important to explain this to the tenant if you decide to go down that route so that they’re not spooked into cutting all ties with you, whether renting or buying.
Hidden costs
Once a property stops being available for letting because you have decided to sell, its running costs stop being tax deductible. If it is your only let property the business ceases altogether. If you hold a portfolio the business continues, but expenditure on a property withdrawn from letting no longer meets the wholly and exclusively test, so insurance, service charge, ground rent, standing charges and mortgage interest on that property can fall out of relief, including the twenty per cent finance cost reducer.
These costs are not allowable against the gain either, because they are not capital.
Then council tax. Most councils charge the full rate on an empty property from day one. Under section 11B of the Local Government Finance Act 1992 a 100 per cent premium can apply once a dwelling has been unoccupied and substantially unfurnished for a year, and under section 11C a separate premium can apply to a furnished dwelling with no resident. Both have a 12-month exception where the property is actively marketed for sale, available once per dwelling per owner, which will cover a straightforward disposal but not a sixteen month restricted period.
Sell to your tenant and none of it arises. You won’t need possession, or the costs that come with it, if all goes according to plan. The rent runs to completion day, and the property is never empty.
The discount
The first stumbling block is that the tenant might not have a deposit, or a sufficient one.
A concessionary purchase, or vendor gifted deposit, is where you sell below open market value and the lender treats the discount as gifted equity in place of some or all of the buyer’s deposit.
This is now mainstream lending. Criteria Brain data reported in March 2026 put it at 42 of 74 lenders accepting a concessionary purchase where the seller is the landlord and the applicants are the tenants. Halifax requires a minimum 10 per cent discount; TSB pairs a 5 per cent deposit with a 5 per cent discount; Aldermore takes a minimum of 5 per cent, up to 25 per cent on landlord-to-tenant sales, with a twelve month occupation requirement. Some lenders calculate loan to value against the open market valuation, which is what makes a no-cash-deposit purchase possible. Others cap the loan at the discounted price. If they do, this will not work if the tenant does not have a deposit. Ask your tenant to find a specialist broker, and/or give them three researched options.
The discount will usually exceed what you save in transaction costs, so you should only go into this with full understanding. Take a property worth £280,000 let at £1,300 a month. A 5 per cent discount is £14,000. Against that you save an agent’s fee of around £4,000, perhaps three months of void at £3,900, council tax and standing charges on an empty property, and other miscellaneous costs, say, £10,000. On these figures, you are down roughly £4,000 before tax.
Then apply the tax, which differs by seller. At the higher CGT rate of 24 per cent for 2026/27 the concession nets down to about £10,640. At the basic rate of 18 per cent it costs £11,480, although the gain is added to your income to set the band, so most sellers of a property this size get to 24 per cent on most of it anyway. Remember, you have to report and pay within 60 days of completion.
If the property sits in a company the gain falls into the corporation tax computation. No annual exempt amount, and no 60 day return; the tax is due nine months and a day after the year end. The rate is 19 per cent up to £50,000 of profits and 25 per cent above £250,000, with marginal relief between the two. At 25 per cent, the £14,000 concession costs the company £10,500.
On those figures a 5 per cent concession is close to cost-neutral for most sellers, and buys certainty, speed and complete removal of restricted period risk. At 10 per cent it costs real money. That, however, is a commercial decision.
What your tenant is walking into
Do it properly, and don’t string your tenant along.
Separate legal representation is mandatory. You will sign an equity gift and solvency declaration, and the lender will require Insolvency Act indemnity insurance, since a sale at an undervalue by a seller who later becomes insolvent is capable of challenge.
The discount must be a genuine gift, not a loan, and cannot carry conditions. Your tenant will likely have to qualify on income like any other borrower, and if they are a first-time buyer the stamp duty position matters: the nil rate band has been £300,000 since 1 April 2025, with relief tapering between £300,000 and £500,000 and lost entirely above £500,000, so a discount bringing the price under £300,000 can remove their bill altogether.
Say at the outset that the sale depends on a mortgage offer, agree a date by which they must have one, and be clear about what happens if they cannot get one. A tenant told the truth who cannot proceed remains a tenant for as long as they can. A tenant led on for six months will probably not stay one for much longer than two months after that realisation sets in.
Where to start
Get a proper open market valuation before naming a figure, because the whole structure depends on the discount being realistic.
Good luck!
Patricia Ogunfeibo is a non-practising solicitor and non-practising Chartered Tax Adviser. She has been a landlord since 1986 and is the founder of tenant2owner, a platform built to aid smooth transitioning from renting to homeownership for renters in England.
General information, not advice on any particular transaction. Lender criteria and tax treatment change; take advice on your own facts.
The post Could your tenant become your buyer? How a direct sale can work for both sides appeared first on Property118.
View Full Article: Could your tenant become your buyer? How a direct sale can work for both sides
Beneficial ownership changes: if the lender’s charge is intact, what exactly is the problem?
Property118
Beneficial ownership changes: if the lender’s charge is intact, what exactly is the problem?
Mortgage brokers told us that many lenders still become nervous at the mention of trusts or beneficial ownership, even where legal title and the registered charge remain untouched. The legal position is not nearly as mysterious as the market response. The harder question is why some lenders appear to treat an ordinary commercial restructuring as though their security has vanished.
When I asked mortgage brokers which lenders genuinely understand transfers of beneficial interest, I expected to receive a list of names. What came back was more revealing. The market still appears to become uncomfortable as soon as somebody mentions a trust, a declaration of trust or beneficial ownership.
Legal and beneficial ownership are routinely separated for perfectly ordinary commercial and family reasons. These include court orders in divorce proceedings, bank of Mum and Dad contributions protected by a declaration of trust, succession planning, changing ownership proportions between family members, restructuring a partnership and incorporating a property business. The decisions are client-led and often concern liability, protection of capital, continuity and the commercially appropriate time to refinance. Any tax consequences have to be dealt with properly, but they are not necessarily what drove the decision.
Two different issues are repeatedly being rolled into one. The first is what has happened to the lender’s registered security. The second is whether the mortgage contract required the lender’s consent. They are both important, but they are not the same question.
What HM Land Registry actually records
HM Land Registry Practice Guide 24 could hardly be clearer about the basic legal distinction. It says that the essence of a trust of land is the separation of the formal title, or legal estate, from the underlying beneficial interest. It also confirms that the register records ownership of the legal estate, not the beneficial interests.
Practice Guide 19 also explains that a restriction entered later in the proprietorship register will not affect a charge that was registered before it.
That supports a narrow but important conclusion. A later change in beneficial ownership does not, simply by existing, remove the lender’s registered charge, alter its priority or make the property disappear from the lender’s security.
What mortgage brokers are seeing
Bob Singh, founder of Chess Mortgages, put the practical problem bluntly: “Any arrangement other than a simple sole or joint ownership spooks most lenders.”
His experience is that references to trusts or transfers of beneficial interest often lead mainstream lenders to point to restrictive clauses in their mortgage terms. Private banks tend to be more familiar with these structures and more willing to understand the commercial rationale.
Nouran Moustafa, Practice Principal and IFA at Roxton Wealth, identified the same misunderstanding from another direction: “Some lenders still hear ‘ownership has changed’ when what has actually changed is who benefits economically from the property.”
Her test for a sensible lender is practical. Has legal title changed? Has the registered charge been affected? Has anybody acquired occupation rights which could prejudice enforcement? Has the mortgage contract been breached? Those questions get to the real risk. Treating every beneficial-interest change as though the registered property has been transferred behind the lender’s back does not.
A patchwork of lender policies
My research did not uncover a coherent industry-wide rule. It uncovered different lenders making very different policy choices.
Aldermore’s published guidance covers individuals transferring several properties into their own limited company, while a YBS Commercial case study records £3.276 million of funding against 17 properties which two siblings wanted to move into a company.
Fleet says it will consider an individual selling to their own special-purpose company and treat the transaction as a purchase. SBI UK publishes another individual-to-company route with specific legal and underwriting controls. Coutts openly lends to trusts, special-purpose vehicles and limited companies, while Handelsbanken promotes bespoke property finance but publishes too little transaction-level detail for me to establish its position on these particular cases.
Other lenders take a more restrictive view. Coventry for Intermediaries, for example, will not accept a limited-company application to buy from one of the company’s directors, shareholders or persons with significant control.
That inconsistency is the point. Reuniting legal and beneficial ownership through new company finance is not a universal legal impossibility. Some lenders have designed products and processes for it, while others have decided not to. That is lender appetite and product design, not the disappearance of legal security.
Has the market become distorted?
Paragon provides one useful historical comparison. Its 2019 broker presentation described a 15-property portfolio moving into limited-company ownership on the same rates and terms, using a deed of covenant and an administration fee of £97.50 per property plus legal costs. The First-tier Tribunal judgment in our recent appeal also records actual Paragon mortgage novations completed with consent in 2021. By contrast, Paragon’s March 2024 transfer-of-equity form says that particular process cannot consider an individual-to-company borrower change. Those documents do not prove when, why or whether the earlier routes were withdrawn, but they do prove that a major specialist lender had previously found these transactions workable.
That brings me to the deliberately controversial question. Since 2023, landlord incorporation has been subjected to hostile public campaigning, extensive HMRC scrutiny and a far more visible compliance drive. From 6 April 2026, section 162 Incorporation Relief must be actively claimed, whereas it previously applied automatically when its conditions were met. HMRC says the change will provide better data and help it target compliance resources to tackle avoidance.
I cannot prove that this atmosphere caused any particular lender to change its policy, and I am not suggesting that HMRC controls mortgage underwriting. I am asking whether sustained controversy and official scrutiny have distorted the market by turning understandable caution into blanket refusal.
Market distortion does not require a conspiracy or a written instruction. It can happen when reputational anxiety quietly becomes credit policy. If that has happened here, landlords may be paying more, refinancing unnecessarily or being refused commercially sensible restructuring even though the lender’s underlying security has not deteriorated.
The company refinancing point deserves a proper answer
I have now raised a further point with several mortgage lenders and brokers. Suppose the beneficial ownership of a property has passed to a company while legal title and an existing personal mortgage remain in the individuals’ names. If the company subsequently obtains new finance at a commercially suitable time, completion can be structured to:
- redeem the existing personal mortgage and discharge its charge;
- transfer registered legal title to the company;
- complete the new company mortgage and grant the incoming lender a registered first legal charge; and
- align the borrower, legal owner, beneficial owner, rental income and mortgage payments within the same corporate structure.
In plain English, the new financing reunites legal and beneficial ownership at completion while giving the incoming lender precisely the borrower and security structure it has agreed to underwrite. The lender examples above demonstrate that this is not merely a theoretical possibility.
This does not retrospectively cure any earlier breach of mortgage conditions, nor does it bypass tax, insolvency, conveyancing, valuation, identity or underwriting requirements. The point is more straightforward. Consent during the life of the old personal mortgage and underwriting a new, fully aligned company mortgage are separate commercial decisions.
If the old loan is repaid, the old charge is discharged and the new lender receives a first legal charge over property registered to its company borrower, what remaining security problem is the lender being asked to solve?
Five questions lenders should answer
- Where legal title, the registered charge and occupation remain unchanged, what precise risk is created by a change in beneficial ownership?
- Which mortgage condition requires consent, and will the lender consider retrospective consent or another form of regularisation?
- Will the lender consider new company finance where the personal mortgage is redeemed, legal title transfers and the new first charge is registered simultaneously?
- Will it accept a related-party purchase from the company’s directors or shareholders, and what controls will apply?
- Has its policy changed during the past three years and, if so, when, why and in response to what evidence?
The central point is simple. A lender is entitled to enforce its contract and set its own lending policy. It should not need to pretend that a beneficial ownership change has erased a registered legal charge in order to do so.
The real question is whether lenders are assessing the property, the contract and their security, or whether the controversy surrounding landlord incorporation has been allowed to do their underwriting for them.
With thanks to Dominic at NewsPage for helping us source the mortgage broker comments used in this article.
Public lender criteria and documents checked on 25 August 2026. Lending policies and documents can change, and absence of a published rule should not be treated as consent.
This article provides general information, not legal, tax or mortgage advice. Borrowers should check the mortgage offer, deed and conditions applicable to their own loan and obtain written lender consent and professional guidance where required.
Why experience matters when incorporating a property business
I’m going to say this plainly: no other organisation has more practical experience of landlord incorporation than Property118.
That is a bold claim, but it is one we have earned the right to make. We have conducted thousands of consultations with landlords, helped hundreds to incorporate their property businesses and supported clients through HMRC compliance checks and Discovery Assessments.
We have also taken our own landlord incorporation model all the way through a 10-day First-tier Tribunal hearing against HMRC.
I am not aware of any other organisation that can match that experience.
Setting up a company is the easy bit
Some landlords think incorporation means setting up a limited company and transferring their properties into it.
I wish it were that simple.
A company can be formed online in a few minutes. The difficult part is working out whether transferring your existing property business into that company makes sense in the first place.
What happens to your mortgages? How will you take money from the company? Should your children become shareholders now or later? What happens if you die? Will you still be able to sell individual properties? Should the mortgages be refinanced immediately, or would that destroy good interest rates and trigger substantial fees?
Then there are the Capital Gains Tax and Stamp Duty Land Tax questions.
Getting just one of those things wrong can be extremely expensive.
Most landlords are trying to solve business problems
The landlords who come to Property118 are rarely looking for a tax scheme. Most have spent decades building their portfolios and are trying to work out what comes next.
Some want to reduce their personal exposure to business risks. Some want to bring their children into the business without immediately handing over everything they have worked for. Others are approaching retirement and want the property business to continue after they are no longer able to run it.
Many do not want to refinance 10, 20 or 30 properties on the same day simply because an adviser tells them that is how incorporation is normally done. They may have valuable mortgage rates, early repayment charges or lenders that will not offer an equivalent company mortgage.
Those are real commercial problems. Tax is important, but it is part of the picture rather than the whole picture.
That distinction matters because the right structure should follow the landlord’s objectives. The structure should not be chosen first and then dressed up with reasons afterwards.
Experience earned the hard way
Property118’s incorporation work has probably been examined more closely than any other landlord incorporation model in the country.
HMRC allocated Scheme Reference Numbers to two arrangements connected with our work. Critics called us scheme promoters, cowboys, grifters, clowns and considerably worse. Some expected us to disappear and leave our clients to deal with the consequences.
We did not.
We stopped taking on new incorporation consultancy while the dispute was being resolved. We supported clients through HMRC enquiries, instructed leading counsel and appealed against HMRC’s decisions.
The hearing lasted 10 days and involved thousands of pages of evidence. On 31 July 2026, the Tribunal allowed the appeals and cancelled HMRC’s Scheme Reference Numbers.
That does not mean the Tribunal decided that every landlord should incorporate or that every landlord automatically qualifies for every available tax relief. It did not. The case was about whether the arrangements had to be disclosed under the DOTAS rules.
What it does mean is that HMRC’s attempt to treat the arrangements as notifiable tax avoidance schemes failed after a full hearing.
There is a considerable difference between commenting about landlord incorporation from the sidelines and standing behind clients when HMRC comes knocking.
We have done the latter.
Why one professional is rarely enough
An accountant may understand the tax. A solicitor may understand the legal documents. A mortgage broker may understand the finance.
All three may be perfectly competent within their own areas, but that does not necessarily mean anybody is looking at the transaction as a whole.
A solicitor might insist that all legal titles must be transferred immediately. That could force the landlord to repay every existing mortgage. A broker might then arrange new company mortgages because that is what the solicitor has requested. The accountant might assume the refinancing has no effect on the available tax reliefs.
Each professional completes their own part of the job, but the landlord can still end up with a poor overall result.
Property118’s role is to bring the tax, legal, accounting, mortgage and commercial considerations together around what the client is actually trying to achieve.
That is where our experience is different.
Sometimes the right answer is not to incorporate
Having more experience does not mean recommending incorporation to everybody.
For some landlords, incorporation can improve business continuity, refinancing flexibility, succession planning and the ability to retain profits for future investment.
For others, the tax costs, mortgage position, intention to sell properties or need to withdraw most of the rental income can make incorporation unsuitable.
We regularly tell landlords not to incorporate when the figures or their plans do not justify it. A limited company is a tool, not a religion.
The purpose of a Property118 consultation is not to sell a predetermined structure. It is to understand what the landlord wants to achieve and then work out whether incorporation helps.
Begin with the right question
The wrong question is:
“How do I transfer my properties into a limited company?”
The right question is:
“What do I want my property business to achieve for me and my family, and is incorporation the best way to achieve it?”
Property118 has more experience of helping landlords answer that question than any other organisation.
We have not simply read about landlord incorporation or commented upon it. We have planned incorporations, coordinated their implementation, supported clients through HMRC investigations and defended our work before the Tribunal.
Isn’t that the sort of experience you want behind you?
BOOK YOUR CONSULTATION TODAY
Property118 has prepared two detailed guides explaining the new Section 162 claim process and the information landlords and their professional advisers should retain.
1) Understanding Section 162Incorporation Relief Applications
2) Section 162 Incorporation Relief Claims
Landlords considering incorporation can also book a Property118 consultation here to discuss their objectives and the professional workstreams that may need to be coordinated.
The post Beneficial ownership changes: if the lender’s charge is intact, what exactly is the problem? appeared first on Property118.
View Full Article: Beneficial ownership changes: if the lender’s charge is intact, what exactly is the problem?
A quarter of landlords report problem tenant possession concerns
Property118
A quarter of landlords report problem tenant possession concerns
One in four landlords say they have struggled to regain possession from problem tenants, according to a Goodlord snap poll of nearly 250 landlords.
The survey found 25% had faced possession challenges following the abolition of Section 21 ‘no-fault’ evictions under the Renters’ Rights Act on 1 May.
Landlords seeking possession must now use Section 8 and establish one of the defined grounds.
However, tenant referencing firm Goodlord found 39% had adopted more cautious tenant vetting, while 9% were investing more in tenant retention to reduce turnover.
Tenant checks tighten
The firm’s director of referencing, Nishma Parekh, said: “These findings point to a market were getting tenant selection right the first time is more critical than ever, given how much harder it has become to reverse a bad match once a tenancy begins.
“Our fraud report made it clear that landlords were already facing a costly problem before the Renters’ Rights Act came in.”
She added: “Now that possession is harder to secure when things go awry, the cost of signing the wrong tenants has only gone up.
“It’s little wonder thorough vetting has become the priority for landlords.”
Possession process takes longer
Separate Goodlord research estimated fraudulent tenancy applications are costing the private rented sector £4.1bn in financial losses every year.
Between July 2025 and June, 41 tenancy applications per 1,000 were flagged for suspected fraud.
Landlords using rent arrears grounds must wait four weeks after serving a Section 8 notice before proceedings can begin, twice the previous notice period.
Goodlord said court delays were extending that timeline further, with Section 8 claims still waiting to be heard.
Compliance costs increase
Half (50%) of landlords surveyed said the Act had increased their compliance burden.
A further 29% reported higher compliance and insurance costs.
Since 1 May, 23% said letting agent fees had increased and 10% reported longer void periods between tenancies.
Goodlord also surveyed 2,001 tenants, of whom 5% said they had been served or threatened with ‘Section 21-style’ evictions since the ban.
The firm said this indicated that most landlords were complying with the legislation and such cases remained rare.
The post A quarter of landlords report problem tenant possession concerns appeared first on Property118.
View Full Article: A quarter of landlords report problem tenant possession concerns
Rent controls cut home supply – Institute for Fiscal Studies
Property118
Rent controls cut home supply – Institute for Fiscal Studies
Rent controls are likely to reduce the supply of homes available to tenants and push some landlords to leave the market, according to research from the Institute for Fiscal Studies (IFS).
It says that private renters spent an average 28% of their household incomes on housing costs in 2024–25, compared with just over 11% across households generally.
The IFS says evidence from countries including Ireland, Germany and parts of the US, shows controls can lower costs for tenants already living in affected properties, but can also produce unintended consequences.
Its review found landlords became more likely to sell to owner-occupiers or convert properties to other uses where controls were introduced.
Supply falls under controls
IFS report authors Matthew Oulton and Tom Wernham write: “The evidence suggests that, unless UK housing markets differ substantially from those in the countries that have implemented them, rent controls would be a costly way to alleviate pressure on housing costs and support renters.
“Rent controls might partly achieve policymakers’ distributional aims by decreasing costs for some tenants and reducing tenants’ uncertainty over rents (at the expense of landlords).”
They added: “But the experience of other countries where controls have been introduced suggests other tenants would likely be made worse off by these controls, as more tenants struggle to find homes to meet their needs and the quality of rental homes declines.
“Lower-income and lower-wealth tenants with less scope to leave the private rented sector are likely to be particularly affected.”
Property quality can fall
The IFS says every study considered in a major 2024 evidence review found that rent controls reduced the supply of homes available to tenants, with some research also finding lower rates of housebuilding.
Evidence from New York found a 36% increase in ‘immediately hazardous’ building code violations following the introduction of controls.
The report says landlords facing restrictions on rent increases may respond by cutting renovation or maintenance spending where there are still plenty of prospective tenants.
Controls can also make it harder for households to move, with tenants potentially remaining in homes that no longer meet their needs because suitable alternatives are difficult to find.
Alternatives to rent controls
The IFS also points to Germany, where controls introduced in 2015 ultimately had no effect on average rents after about a year because of the way exemptions operated.
Research from Oslo also found that some landlords sought other forms of compensation, including extra services from tenants or deposits worth 10 or even 20 months of rent, requirements which largely disappeared after controls were removed.
The report argues that increasing the overall supply of housing through investment or planning reform would tackle the underlying pressure on housing costs more directly.
It also says tax and benefit policy could target financial help more closely at lower-income tenants rather than giving the largest benefit to people who already occupy rent-controlled homes.
The post Rent controls cut home supply – Institute for Fiscal Studies appeared first on Property118.
View Full Article: Rent controls cut home supply – Institute for Fiscal Studies
Categories
- Landlords (19)
- Real Estate (9)
- Renewables & Green Issues (1)
- Rental Property Investment (1)
- Tenants (21)
- Uncategorized (12,940)
Archives
- September 2026 (23)
- August 2026 (61)
- July 2026 (63)
- June 2026 (70)
- May 2026 (70)
- April 2026 (78)
- March 2026 (72)
- February 2026 (55)
- January 2026 (52)
- December 2025 (62)
- August 2025 (51)
- July 2025 (51)
- June 2025 (49)
- May 2025 (50)
- April 2025 (48)
- March 2025 (54)
- February 2025 (51)
- January 2025 (52)
- December 2024 (55)
- November 2024 (64)
- October 2024 (82)
- September 2024 (69)
- August 2024 (55)
- July 2024 (64)
- June 2024 (54)
- May 2024 (73)
- April 2024 (59)
- March 2024 (49)
- February 2024 (57)
- January 2024 (58)
- December 2023 (56)
- November 2023 (59)
- October 2023 (67)
- September 2023 (136)
- August 2023 (131)
- July 2023 (129)
- June 2023 (128)
- May 2023 (140)
- April 2023 (121)
- March 2023 (168)
- February 2023 (155)
- January 2023 (152)
- December 2022 (136)
- November 2022 (158)
- October 2022 (146)
- September 2022 (148)
- August 2022 (169)
- July 2022 (124)
- June 2022 (124)
- May 2022 (130)
- April 2022 (116)
- March 2022 (155)
- February 2022 (124)
- January 2022 (120)
- December 2021 (117)
- November 2021 (139)
- October 2021 (130)
- September 2021 (138)
- August 2021 (110)
- July 2021 (110)
- June 2021 (60)
- May 2021 (127)
- April 2021 (122)
- March 2021 (156)
- February 2021 (154)
- January 2021 (133)
- December 2020 (126)
- November 2020 (159)
- October 2020 (169)
- September 2020 (181)
- August 2020 (147)
- July 2020 (172)
- June 2020 (158)
- May 2020 (177)
- April 2020 (188)
- March 2020 (234)
- February 2020 (212)
- January 2020 (164)
- December 2019 (107)
- November 2019 (131)
- October 2019 (145)
- September 2019 (123)
- August 2019 (112)
- July 2019 (93)
- June 2019 (82)
- May 2019 (94)
- April 2019 (88)
- March 2019 (78)
- February 2019 (77)
- January 2019 (71)
- December 2018 (37)
- November 2018 (85)
- October 2018 (108)
- September 2018 (110)
- August 2018 (135)
- July 2018 (140)
- June 2018 (118)
- May 2018 (113)
- April 2018 (64)
- March 2018 (96)
- February 2018 (82)
- January 2018 (92)
- December 2017 (62)
- November 2017 (100)
- October 2017 (105)
- September 2017 (97)
- August 2017 (101)
- July 2017 (104)
- June 2017 (155)
- May 2017 (135)
- April 2017 (113)
- March 2017 (138)
- February 2017 (150)
- January 2017 (127)
- December 2016 (90)
- November 2016 (135)
- October 2016 (149)
- September 2016 (135)
- August 2016 (48)
- July 2016 (52)
- June 2016 (54)
- May 2016 (52)
- April 2016 (24)
- October 2014 (8)
- April 2012 (2)
- December 2011 (2)
- November 2011 (10)
- October 2011 (9)
- September 2011 (9)
- August 2011 (3)
Calendar
Recent Posts
- Could a new LLP tax judgment help landlords caught in HMRC’s Spotlight 63?
- Why the nonsense £65 landlord database tax is just the start
- One million landlords set to use tenant deposit alternatives
- Why September could be the month to rethink your property portfolio
- Rents look set to rise as tenant demand grows – RICS
