HMRC’s latest overreach: Since when did your own capital stop being yours?
 admin


Property118
HMRC’s latest overreach: Since when did your own capital stop being yours?
Suppose you invest £500,000 of your own money into a property business. The money is used to acquire and improve rental properties which remain in the business, continue to generate taxable rental income and, after several years, are worth considerably more than the amount you originally invested.
You may eventually decide that you no longer want the whole £500,000 of your personal capital tied up in those properties. You therefore arrange a £300,000 commercial mortgage, secured against them, and withdraw £300,000 of the capital you originally introduced. You might use that money to buy another home, help your children, fund your retirement, pay for a holiday or simply return it to the savings account from which it originally came.
HMRC’s recently rewritten guidance appears to suggest that the tax treatment of the mortgage interest may depend upon what you subsequently do with the capital returned to you. I struggle to understand why that should be relevant. It is your capital, you introduced it into the business and you have not withdrawn more than you invested. The properties remain in the business and still require £500,000 of funding, except that £300,000 is now being provided by a commercial lender rather than by you personally.
Why should HMRC have any interest in what you decide to do with your own money after it has been returned to you?
HMRC has quietly rewritten its guidance
On 1 July 2026, HMRC amended several pages of its Business Income Manual dealing with borrowing, business funding and the withdrawal of capital from unincorporated businesses. The pages affected included BIM45690, “Funding the business”, and BIM45700, “Withdrawal of capital from a business”.
These pages apply to trades and property businesses operated by individuals and partnerships. They do not directly apply to companies, which are subject to the separate corporation tax loan relationship rules.
HMRC described the amendments as providing clearer context for its examples and removing unnecessary numerical calculations. That description makes the changes sound like routine housekeeping, although the practical effect appears to be considerably more significant.
The new wording in BIM45700 states:
“Simply exchanging existing capital for loan finance does not on its own satisfy the wholly and exclusively test.”
HMRC now says interest is allowable where the borrowing is used for business expenditure or to acquire assets used in the business. The rewritten BIM45690 then provides an example in which a business owner uses personal money to acquire an office, trading stock and a van. Two years later, she borrows exactly the same amount, withdraws the capital she originally introduced and spends it on a private holiday. HMRC concludes that the interest is not allowable because the borrowing facilitated a personal withdrawal.
That is where I believe HMRC has overreached. The office is still being used by the business, the stock was acquired for the purposes of the business and the van remains a business asset. The proprietor has not withdrawn more than she originally invested. The only substantive change is that a bank has replaced the proprietor as the source of finance.
HMRC nevertheless appears to be saying that the commercial purpose of the loan is somehow transformed because the proprietor spends her returned capital on a holiday. That conclusion seems to confuse the purpose for which the borrowing is required by the business with the proprietor’s subsequent use of capital that already belonged to her.
It is not necessarily the bank’s money that pays for the holiday
The framing of HMRC’s example encourages the reader to believe that the business owner has borrowed money to pay for a holiday. That description makes the transaction sound objectionable, but it does not necessarily reflect what has happened commercially.
The proprietor previously invested her own money in the business and that capital funded the office, stock and van. When the business later borrowed the same amount, the loan replaced part of the proprietor’s capital as the source of business finance. The proprietor then received her original capital back and used it for a private purpose.
The holiday was purchased using capital that already belonged to the proprietor. The business borrowing was performing the commercial function of financing assets which remained within the business.
That is fundamentally different from a proprietor who has invested £100,000, withdrawn the entire £100,000 and then borrowed a further £50,000 through the business to pay private bills. In that second example, the proprietor may be using business borrowing to finance drawings exceeding the capital and profits available for withdrawal. Restricting the interest in those circumstances may be entirely appropriate.
HMRC’s replacement-capital example does not describe that situation. The proprietor introduced sufficient capital, used it to acquire genuine business assets and subsequently withdrew no more than the amount originally invested.
The rewritten guidance appears to have removed the important distinction between borrowing to finance new private expenditure and borrowing to replace personal capital already committed to a continuing business. Those are not commercially equivalent transactions and should not automatically produce the same tax treatment.
HMRC’s former guidance recognised that distinction
Before July 2026, BIM45700 expressly recognised that a proprietor could withdraw profits and capital introduced into a business, even where substitute finance then had to be provided through interest-bearing borrowing.
The former guidance stated:
“The interest payable on the loans is an allowable deduction.”
The reasoning was that the replacement borrowing provided working capital for the business. Relief could be restricted where the proprietor’s capital account became overdrawn, but the guidance did not treat every personal use of returned capital as proof that the borrowing itself had a private purpose.
This was not an obscure interpretation hidden on a forgotten page of HMRC’s website. The Office of Tax Simplification reproduced the guidance in its 2022 review of residential property income and said that HMRC appeared to accept interest on borrowing used to allow a business owner to withdraw capital, provided the capital account did not become overdrawn.
The OTS also reproduced an HMRC example involving a landlord who refinanced a London property and used the capital withdrawn to purchase a home in Rotterdam. The interest was treated as allowable in full because the borrowing financed the rental property up to the value at which it had been introduced into the property business. The fact that the landlord used the money withdrawn to purchase a private residence did not destroy the business purpose of the borrowing.
HMRC’s new BIM45700 contains a remarkably similar example. A landlord increases the mortgage on a London rental property and uses the additional funds to buy a private residence in Paris. HMRC now says that the interest on the additional borrowing is not allowable.
The former example involved Rotterdam and the replacement involves Paris. The destination is largely irrelevant, but HMRC’s answer has changed completely.
What changed in the law?
That is the question HMRC now needs to answer.
Parliament makes tax law, the courts interpret that law and HMRC publishes guidance explaining how it believes the legislation should be applied. HMRC’s manuals are not legislation and rewriting a webpage cannot, by itself, create a new tax rule.
The relevant statutory test remains section 34 of the Income Tax (Trading and Other Income) Act 2005. Broadly, expenditure is not deductible unless it is incurred wholly and exclusively for the purposes of the trade or property business. The legislation also permits an identifiable business proportion of expenditure incurred for more than one purpose.
We are not aware of any recent amendment to section 34 which says that replacement borrowing ceases to finance a business asset merely because the proprietor uses the capital returned to them for a personal purpose. HMRC’s update record does not identify a new Act of Parliament, statutory instrument or binding court judgment behind the change. It describes the amendments only as providing clearer context and removing unnecessary calculations.
HMRC may have identified legislation or judicial authority which it believes overturns the previous interpretation. If so, it should publish that authority and explain its reasoning. If nothing relevant has changed in the law, the uncomfortable conclusion is that HMRC has attempted to change the practical tax outcome by altering its own interpretation.
That is more than clarification.
HMRC’s position appears difficult to reconcile with case law
HMRC’s current guidance continues to quote the decision in Scorer v Olin Energy Systems Ltd. The Special Commissioners explained that the purpose of a loan cannot necessarily be determined merely by examining the immediate use of the money. It is a question of fact which must be decided by considering all the available evidence.
That principle is highly relevant to replacement borrowing. Imagine that a landlord pays £250,000 in cash for a rental property and, five years later, raises a £150,000 mortgage against it. Looking only at the movement of money through the bank account might suggest that the mortgage advance was paid to the landlord personally. Looking at the transaction as a whole produces a different commercial analysis.
The landlord’s property business required £250,000 of funding. Before the refinance, all £250,000 was supplied by the landlord. Afterwards, £100,000 continued to be supplied by the landlord and £150,000 was provided by the mortgage lender. The borrowing was therefore financing the same continuing property-business asset, even though the proprietor had received part of their original capital back.
The purpose of the mortgage should not be determined solely by asking whether the landlord subsequently bought another rental property, purchased a private home, helped a family member or booked a world cruise. Those decisions concern the use of capital after it has been returned to its owner. They do not necessarily determine the commercial function performed by the borrowing within the property business.
Silk v Fletcher does not give HMRC a blank cheque
HMRC’s revised guidance also places greater emphasis on Silk v Fletcher. That case concerned a business with an overdrawn capital account where the proprietor’s drawings had exceeded business profits over a prolonged period.
HMRC’s own summary says that an overdrawn capital account may support the conclusion that borrowing funded private drawings, unless the taxpayer can demonstrate otherwise. It also emphasises that the underlying facts must be examined carefully.
There is nothing particularly surprising or controversial about that principle. Where a proprietor continually withdraws more than the profits and capital available to them, some of the business borrowing may, as a matter of fact, be financing personal expenditure.
The example now being used by HMRC is materially different. The proprietor introduced personal capital to acquire genuine business assets, later borrowed no more than the amount previously introduced and withdrew no more than their own capital. The capital account is not overdrawn.
Using Silk v Fletcher to challenge excess drawings is one thing. Using it to suggest that a proprietor cannot replace genuine capital simply because they wish to use the returned money privately is quite another.
The BRRR strategy could become an HMRC trap
The change has obvious implications for landlords using the BRRR strategy: Buy, Refurbish, Rent, Refinance and Repeat.
Suppose an investor buys a neglected property at auction for £160,000 and spends £40,000 refurbishing it. The property cannot initially be mortgaged, so the investor uses £200,000 of personal savings. Once the work has been completed and the property is let, the investor refinances it with a £150,000 buy-to-let mortgage.
The property business still owns the same asset and the property continues to generate taxable rental income. The investor remains exposed to the commercial risks associated with owning it and still has £50,000 of personal capital tied up in the project. The remaining £150,000 of the funding is now being provided by a lender.
HMRC may accept the interest if the investor uses all £150,000 released by the refinance to purchase another rental property. The position becomes much less clear if the investor uses £100,000 for the next project and £50,000 to help a child buy a home. Would only two-thirds of the interest qualify? Would the answer change if the whole £150,000 remained in a savings account for six months while the investor searched for the next suitable property?
Further uncertainty arises if an intended purchase falls through and the investor uses some of the capital privately while looking for another opportunity, or if the investor simply decides not to repeat the strategy and wants their original capital back.
The underlying rental property and its mortgage remain exactly the same in each of these examples. HMRC’s rewritten approach nevertheless appears capable of making the tax treatment depend upon what the investor does with capital which was already theirs.
That could turn an ordinary commercial refinancing into a tax trap. It may also make it difficult for investors and their advisers to determine the correct tax treatment until long after the borrowing has taken place.
For individual residential landlords, qualifying finance costs are generally dealt with through the basic-rate tax reduction rather than being deducted in full from rental income. That existing restriction is separate from the more fundamental question of whether HMRC accepts that the borrowing qualifies as property-business finance at all.
Property flips may be caught as well
The same problem could affect property traders and developers.
A property trader might purchase a house for £180,000, spend £70,000 refurbishing it and place it on the market for £325,000. The trader initially uses £250,000 of personal capital because the auction requires a quick completion and arranging finance would cause delay, increase costs or place the purchase at risk.
While the property is being marketed, the trader raises £150,000 against it. The property remains trading stock and the trader remains personally exposed to the commercial risks associated with the development, including whether the property will sell, how long the sale will take and whether the expected price will be achieved.
The loan has replaced part of the £250,000 which the trader committed to the project. There is no obvious commercial reason why the trader should be forced to leave the full £250,000 invested until the sale completes, particularly when the property is capable of supporting commercial borrowing.
It is equally difficult to see why the tax treatment of the interest should depend upon whether the trader uses the released capital to begin another development, repay their home mortgage or enjoy some of the proceeds of years of successful trading. The business asset is still present, the trader’s remaining capital is still exposed to risk and the loan is secured against and commercially supported by an asset held for the purposes of the trade.
HMRC’s apparent position could therefore penalise a trader who sensibly uses personal capital to reduce financing costs during the early and most uncertain stages of a project.
HMRC may be encouraging businesses to borrow unnecessarily
One of the most absurd practical consequences of HMRC’s interpretation is that it could encourage business owners to borrow from the outset, even where commercial borrowing is unnecessary.
Consider two landlords purchasing identical properties for £300,000. The first contributes £100,000 and takes out a £200,000 mortgage on completion. Subject to the normal restrictions, the mortgage interest clearly relates to acquiring the rental property.
The second landlord pays the whole £300,000 from personal savings and arranges the same £200,000 mortgage a year later, withdrawing £200,000 of the capital originally invested. At that point, the property, mortgage, rental income and amount of personal capital remaining in the business are identical in both cases.
HMRC’s new approach appears capable of producing a different tax result solely because one landlord borrowed on the acquisition date while the other waited for a year. The second landlord might have avoided interest charges, arrangement fees and other finance costs during that initial period, but could now be penalised for having used personal capital first.
A cautious adviser may therefore feel obliged to recommend that the next investor arranges finance at the time of acquisition, even where personal capital is readily available and borrowing serves no immediate commercial purpose. That could result in unnecessary interest, bridging charges, arrangement fees, valuation costs and legal expenses.
Tax policy should not encourage business owners to incur debt earlier than commercially necessary merely to preserve the tax treatment of future interest.
This reaches far beyond landlords
HMRC’s guidance applies to unincorporated trades as well as property businesses. The same principle could affect a farmer who purchases machinery using personal savings and later refinances it, a shopkeeper who personally funds the acquisition of stock before arranging an overdraft, or a manufacturer who buys equipment with personal capital and subsequently introduces commercial borrowing.
It could equally affect a professional partnership whose partners fund an expansion before refinancing, a hotelier who uses personal savings to refurbish the premises and later raises a secured loan, or any sole trader who temporarily commits personal capital to a business and subsequently wants some of it returned.
HMRC’s own guidance uses the example of a manufacturer of plastic dinosaur toys who raises finance against a factory and buys a Spanish holiday home. The choice of examples is revealing. By focusing on holidays, foreign homes and private cars, HMRC makes the proprietors’ spending appear frivolous and invites the reader to view the transaction with suspicion.
That framing distracts from the real question, which is whether the proprietor had sufficient capital available to withdraw. Where the proprietor has not withdrawn more than the capital and profits genuinely available to them, HMRC must explain the lawful basis for treating their subsequent personal expenditure as though it automatically determines the purpose of the borrowing.
The underlying principle should not change according to whether the proprietor uses the returned capital to purchase a holiday home, fund cancer treatment, support a child or provide for their retirement. It remains their money.
Some unfortunate taxpayer may now have to take this to Tribunal
HMRC may eventually provide an explanation which resolves these concerns. It may confirm that genuine replacement borrowing can still qualify where the facts demonstrate that it finances a continuing business, even if the proprietor uses the capital returned to them for a personal purpose.
The rewritten examples currently point in the opposite direction. That creates a real possibility that HMRC will challenge an interest claim, issue additional assessments and leave an ordinary business owner with an appalling choice.
The taxpayer can accept HMRC’s interpretation and pay tax which they do not believe is legally due, or they can spend years corresponding with HMRC, instruct professional advisers, endure the stress and disruption of an enquiry and potentially incur tens of thousands of pounds taking the dispute to the First-tier Tribunal.
Even a taxpayer who eventually succeeds may never recover all their professional costs, management time or peace of mind. Many taxpayers cannot afford to challenge HMRC at all, which is how questionable interpretations risk becoming established in practice without a court ever deciding whether they are legally correct.
Some unfortunate taxpayer may eventually have to take this all the way to Tribunal simply to re-establish a principle which HMRC’s own guidance had recognised for years. Taxpayers should not be required to fund test cases every time HMRC quietly changes its interpretation of legislation which Parliament has not changed.
HMRC needs to answer one straightforward question
Property118 has published an Open Letter to HMRC asking what changed in the law behind BIM45690 and BIM45700.
We have asked HMRC to identify the legislation or judicial authority which supports its revised interpretation. We have also asked whether external borrowing can still replace personal capital genuinely committed to a business, why borrowing after an acquisition should be treated differently from borrowing arranged on the acquisition date and whether the proprietor’s subsequent use of returned capital is now regarded as decisive.
HMRC also needs to explain how the revised interpretation is reconciled with Scorer v Olin, what relevance Silk v Fletcher has where the capital account is not overdrawn, whether the change will be applied to historic refinancing arrangements and why a potentially substantive change was described merely as providing clearer context.
These questions matter to landlords using BRRR, property traders undertaking flips, auction buyers, farmers, partnerships and thousands of other business owners who may initially use personal capital and refinance later.
HMRC is perfectly entitled to correct its manuals where it believes they do not accurately reflect the law. What it should not be entitled to do is change the practical tax outcome without clearly explaining the legal basis for doing so.
Until HMRC provides that explanation, I regard this as another example of HMRC appearing to overreach beyond what Parliament legislated and beyond what the relevant case law principles appear to support.
Please read and share our Open Letter to HMRC. The wider it is shared among landlords, accountants, tax advisers, property developers and other business owners, the more difficult it will be for a potentially fundamental change to pass unnoticed.
This article expresses the author’s opinion on HMRC’s revised published guidance. HMRC’s manuals do not have the force of law, and the treatment of interest depends upon the legislation and the particular facts. Individual landlords’ residential finance costs are also subject to the separate statutory restrictions commonly known as Section 24. Professional tax advice should be obtained before entering into or reporting a refinancing transaction.
The post HMRC’s latest overreach: Since when did your own capital stop being yours? appeared first on Property118.
View Full Article: HMRC’s latest overreach: Since when did your own capital stop being yours?
Efficiency You Can Measure, What Greening a Website Taught Us About Energy Standards
Property118
Efficiency You Can Measure, What Greening a Website Taught Us About Energy Standards
Efficiency You Can Measure: What Greening a Website Taught Us About Energy Standards
By Dave Fuller, Managing and Technical Director, Accent Design Group Ltd
For more than fifteen years, we at Accent Design have built and maintained the Property118 website. We created the brand, developed the site and the internal software that runs behind it, and we look after it every day. Over that time one principle has held firm: efficiency is not a one-off project, it is a habit. That thinking recently led us to move Property118 onto a fully sustainable, renewable-powered host, and to start measuring the site’s energy use and page weight in earnest.
What follows is an honest account of what we did, what the numbers now show, and why it matters to you as a landlord far beyond the technicalities of web hosting. Because the discipline behind a lean, efficient website is precisely the discipline the law is now asking you to apply to your properties.
Why a website has an energy footprint at all
It is easy to think of a website as weightless. It is not. Every page a visitor loads has to be stored, served and transmitted, and all of that draws electricity, from the data centre through the network to the device in your hand. A heavier page, one bloated with oversized images, unnecessary code and sluggish scripts, uses more energy every single time it loads. Multiply that across tens of thousands of visits and the footprint becomes real.
We wrote about this in more detail in our article The Environmental Cost of Digital, but the short version is this: a faster website is almost always a greener website, and a greener website is almost always a faster one. The two goals pull in the same direction, which is rare and worth taking advantage of.
What we actually did, and what the numbers show
The first move was to migrate Property118 to a host running entirely on sustainable energy. The second was to keep reducing the download weight of the site so that each page does more with less.
We do not ask you to take the results on trust. Two independent tools tell the story.
On performance, GTmetrix (tested 18 July 2026) awards the Property118 homepage an overall Grade A, with a Performance score of 96% and a Structure score of 95%. The Core Web Vitals, the measures Google uses to judge real-world experience, are strong across the board: a Largest Contentful Paint of 1.4 seconds, a Total Blocking Time of just 25 milliseconds, and a Cumulative Layout Shift of 0, meaning the page stays put as it loads rather than jumping around under your finger.
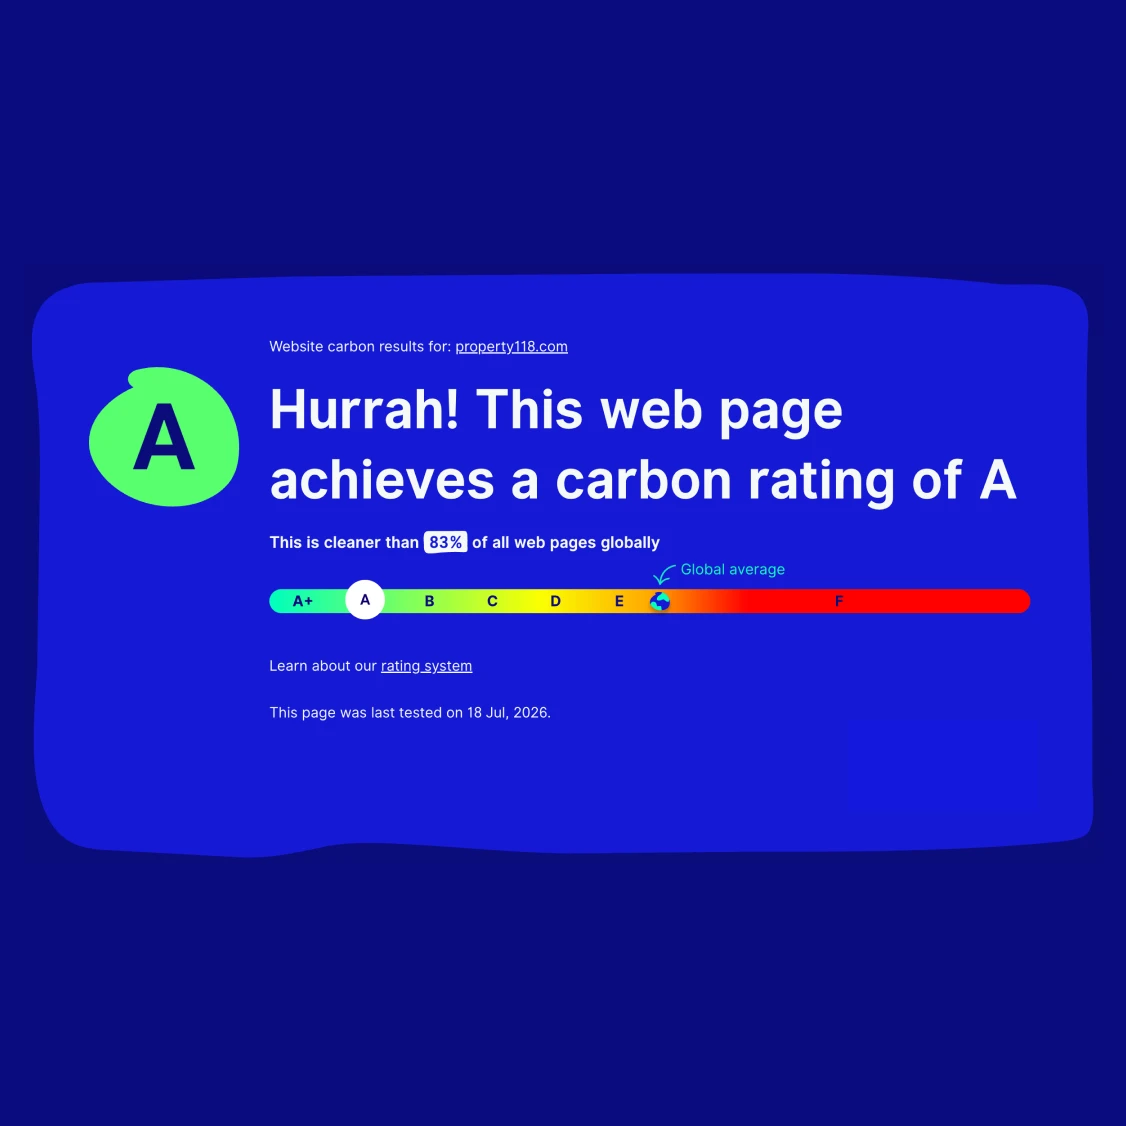
On sustainability, the Website Carbon Calculator (tested 18 July 2026) gives the site a carbon rating of A, confirms it is running on sustainable energy, and rates it cleaner than 83% of all web pages tested globally. Each visit produces only 0.07g of CO2. That is the payoff from the hosting move and the weight reduction working together.
These are genuinely good results, and I am pleased with them. But I want to be straight with you: this is not finished. Cleaner than 83% still leaves the very top tier ahead of us. That 0.07g per visit can be pushed lower with further weight savings, and we have more improvements already planned as part of the ongoing maintenance and support work we do on the site. You can read more about our wider approach on our Digital Sustainability page. Efficiency, digital or otherwise, is a direction of travel, not a destination.
Which brings us to your properties
If that last sentence rings a bell, it should. It is the exact position the law now takes on the energy efficiency of rental homes, through the Minimum Energy Efficiency Standards, or MEES.
The parallel is close. We audited the site, found the waste, cut it, switched to a cleaner supplier, and we keep measuring. A landlord looking at a property faces the same sequence: assess the current performance, identify what is dragging it down, make the improvements that pay off, and stay ahead of a standard that keeps rising. In both cases the reward is lower running costs, a better experience for the people using it, and an asset that holds its value.
Where MEES stands today
Here is the current position, drawn from the government’s own landlord guidance, which is the source worth checking before you act on anything.
The live legal minimum is EPC band E. Since 1 April 2020, landlords have not been permitted to let or continue to let a property covered by the MEES Regulations if its EPC rating is below E, unless a valid exemption is registered. If you hold a property sitting at F or G, it needs improving to at least E, or a registered exemption, before it can be lawfully let.
The bigger issue is the direction of travel. The government has committed to a long-term aim for as many privately rented homes as possible to reach EPC band C or equivalent by 2030. Following its 2026 consultation, the government is still working through the detailed policy design, so the precise mechanics, dates and cost arrangements are being finalised rather than fully settled in law. That is an important distinction, and it is why I would not treat any single secondary source as gospel. Check the GOV.UK guidance directly, and take professional advice on your particular properties.
What is not in doubt is the trajectory. The floor is rising from E towards C, and the assessment methodology itself is being reformed to look beyond simple running costs at things like fabric performance. Planning early, while the timeline still gives you room, is far cheaper than scrambling at a deadline.
A practical takeaway
You do not need to be a surveyor to start thinking like one. The same four steps that took our website from ordinary to Grade A apply to a property:
First, measure honestly. Get a current EPC. Ratings shift over time and the certificate itself lists the improvements that will move the needle most.
Second, target the biggest wins first. On a website that meant image weight and code bloat. On a property it usually means insulation and heating. Spend where the return is greatest, not where the job is easiest.
Third, check what help exists. Just as we chose a green host rather than building our own, there are grants and funding schemes for energy improvements. They change often, so confirm what is current before you commit.
Fourth, keep going. A single upgrade is not the finish line any more than a single good test result is. The standard will keep rising; staying comfortably ahead of it is cheaper and calmer than meeting it in a panic.
The honest close
I am proud of where the Property118 site has reached: a GTmetrix Grade A, a Website Carbon rating of A, running on renewable energy, cleaner than most of the web. And I am equally clear that there is more to do, with further improvements on the way. That combination, real progress plus genuine room to improve, is not a weakness to hide. It is what good stewardship of any asset actually looks like, whether that asset is a website or a home you rent out.
Efficiency you can measure is efficiency you can improve. That is true of our work on Property118, and it is true of the properties you let.
Dave Fuller is Managing and Technical Director of Accent Design Group Ltd, the Norwich digital agency that has designed, built and maintained the Property118 website for over fifteen years.
Performance and carbon figures cited were tested on 18 July 2026 via GTmetrix and the Website Carbon Calculator. Regulatory details reflect government guidance current at the time of writing; readers should verify the latest position at GOV.UK and seek professional advice on their own properties. Last reviewed: 18 July 2026.
The post Efficiency You Can Measure, What Greening a Website Taught Us About Energy Standards appeared first on Property118.
View Full Article: Efficiency You Can Measure, What Greening a Website Taught Us About Energy Standards
Universal Credit claimants should manage their own finances – Government
Property118
Universal Credit claimants should manage their own finances – Government
The government has claimed tenants on Universal Credit remain responsible for rent payments.
In a written parliamentary answer, the government confirmed that if tenants get into arrears, rent payments may be sent directly to their landlord.
Universal Credit is typically paid once a month directly to the claimant, who is then responsible for paying the landlord. However, the landlord can request a Managed Payment to Landlord (MPTL) as part of an Alternative Payment Arrangement (APA).
UC claimant should manage their own finances
In a written parliamentary question, Liberal Democrat MP Joshua Reynolds asked: “What assessment has the government made of the adequacy of protections for private landlords where Universal Credit housing costs have been paid to tenants but the rent has not subsequently been paid to the landlord”.
In response, Stephen Timms, minister for social security and disability, said: “The default position in Universal Credit is that claimants should manage their own finances, including payment of their rent. This encourages self-reliance and eases the transition back into work.
“Where a claimant is vulnerable or if they get into arrears, rent payments may be sent direct to their landlord, on their behalf. Decisions related to direct payments of rent must be based upon the claimant’s best interests.
“Tenants remain responsible for their rental liabilities, even where payment goes straight to their landlord.”
Tenants left in tears
As previously reported by Property118, the Department of Work and Pensions (DWP) sparked fury as Universal Credit (UC) applicants face extensive demands to confirm their eligibility.
One landlord told Property118 that some of his tenants have been “left in tears” as they can not comply with the list of demands.
One of the demands asks to see a full-body picture including the feet of the tenant standing in the doorway of the property.
The post Universal Credit claimants should manage their own finances – Government appeared first on Property118.
View Full Article: Universal Credit claimants should manage their own finances – Government
Categories
- Landlords (19)
- Real Estate (9)
- Renewables & Green Issues (1)
- Rental Property Investment (1)
- Tenants (21)
- Uncategorized (12,940)
Archives
- September 2026 (23)
- August 2026 (61)
- July 2026 (63)
- June 2026 (70)
- May 2026 (70)
- April 2026 (78)
- March 2026 (72)
- February 2026 (55)
- January 2026 (52)
- December 2025 (62)
- August 2025 (51)
- July 2025 (51)
- June 2025 (49)
- May 2025 (50)
- April 2025 (48)
- March 2025 (54)
- February 2025 (51)
- January 2025 (52)
- December 2024 (55)
- November 2024 (64)
- October 2024 (82)
- September 2024 (69)
- August 2024 (55)
- July 2024 (64)
- June 2024 (54)
- May 2024 (73)
- April 2024 (59)
- March 2024 (49)
- February 2024 (57)
- January 2024 (58)
- December 2023 (56)
- November 2023 (59)
- October 2023 (67)
- September 2023 (136)
- August 2023 (131)
- July 2023 (129)
- June 2023 (128)
- May 2023 (140)
- April 2023 (121)
- March 2023 (168)
- February 2023 (155)
- January 2023 (152)
- December 2022 (136)
- November 2022 (158)
- October 2022 (146)
- September 2022 (148)
- August 2022 (169)
- July 2022 (124)
- June 2022 (124)
- May 2022 (130)
- April 2022 (116)
- March 2022 (155)
- February 2022 (124)
- January 2022 (120)
- December 2021 (117)
- November 2021 (139)
- October 2021 (130)
- September 2021 (138)
- August 2021 (110)
- July 2021 (110)
- June 2021 (60)
- May 2021 (127)
- April 2021 (122)
- March 2021 (156)
- February 2021 (154)
- January 2021 (133)
- December 2020 (126)
- November 2020 (159)
- October 2020 (169)
- September 2020 (181)
- August 2020 (147)
- July 2020 (172)
- June 2020 (158)
- May 2020 (177)
- April 2020 (188)
- March 2020 (234)
- February 2020 (212)
- January 2020 (164)
- December 2019 (107)
- November 2019 (131)
- October 2019 (145)
- September 2019 (123)
- August 2019 (112)
- July 2019 (93)
- June 2019 (82)
- May 2019 (94)
- April 2019 (88)
- March 2019 (78)
- February 2019 (77)
- January 2019 (71)
- December 2018 (37)
- November 2018 (85)
- October 2018 (108)
- September 2018 (110)
- August 2018 (135)
- July 2018 (140)
- June 2018 (118)
- May 2018 (113)
- April 2018 (64)
- March 2018 (96)
- February 2018 (82)
- January 2018 (92)
- December 2017 (62)
- November 2017 (100)
- October 2017 (105)
- September 2017 (97)
- August 2017 (101)
- July 2017 (104)
- June 2017 (155)
- May 2017 (135)
- April 2017 (113)
- March 2017 (138)
- February 2017 (150)
- January 2017 (127)
- December 2016 (90)
- November 2016 (135)
- October 2016 (149)
- September 2016 (135)
- August 2016 (48)
- July 2016 (52)
- June 2016 (54)
- May 2016 (52)
- April 2016 (24)
- October 2014 (8)
- April 2012 (2)
- December 2011 (2)
- November 2011 (10)
- October 2011 (9)
- September 2011 (9)
- August 2011 (3)
Calendar
Recent Posts
- Could a new LLP tax judgment help landlords caught in HMRC’s Spotlight 63?
- Why the nonsense £65 landlord database tax is just the start
- One million landlords set to use tenant deposit alternatives
- Why September could be the month to rethink your property portfolio
- Rents look set to rise as tenant demand grows – RICS
