Open letter to HMRC: What changed in the law behind BIM45690 and BIM45700?
 admin


Property118
Open letter to HMRC: What changed in the law behind BIM45690 and BIM45700?
Dear HMRC,
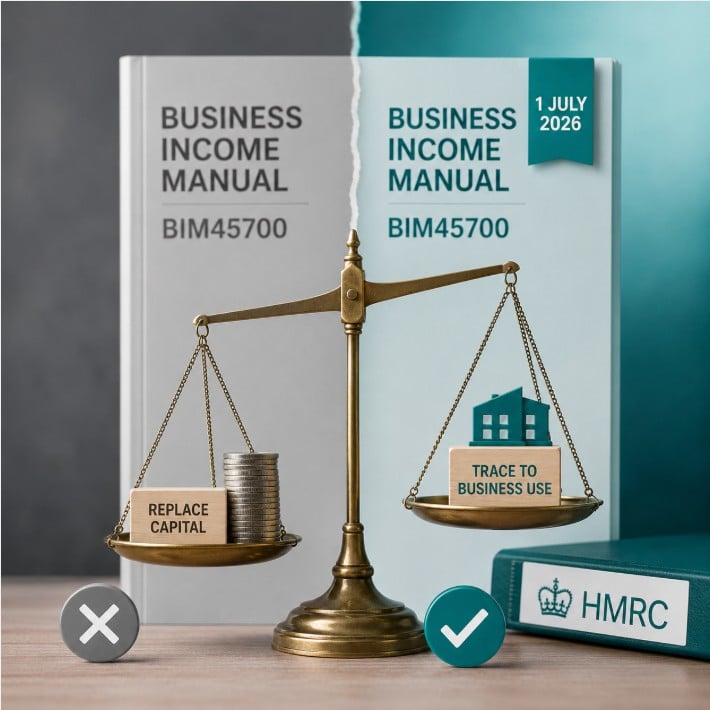
On 1 July 2026, HMRC amended several pages of its Business Income Manual dealing with interest deductions, the replacement of capital with borrowing and withdrawals from unincorporated businesses. The pages affected include BIM45690, “Funding the business”, and BIM45700, “Withdrawal of capital from a business”. Both pages expressly apply to the computation of trading profits and property income, which means the changes are directly relevant to individual landlords and property partnerships.
HMRC’s published update record describes the amendments to BIM45690 and BIM45700 as changes intended to provide “clearer context for the examples and remove unnecessary numerical calculations”. Having compared the previous and replacement wording, we are concerned that this description understates the significance of what has changed.
The former guidance
Before the July 2026 amendment, BIM45700 stated:
“A proprietor of a business may withdraw the profits of the business and the capital they have introduced to the business, even though substitute funding then has to be provided by interest bearing loans. The interest payable on the loans is an allowable deduction. This is on the basis that the purpose of the additional borrowing is to provide working capital for the business. There will, though, be an interest restriction if the proprietor’s capital account becomes overdrawn.”
This was not an obscure example buried in an unrelated section of the manual. It was a clear statement of HMRC’s published position on the replacement of capital introduced by a proprietor with external borrowing.
The guidance recognised that a proprietor might originally fund a business from personal resources, later withdraw that capital and replace it with interest-bearing borrowing. Provided the proprietor had not withdrawn more than the accumulated profits and capital properly standing to their credit, HMRC accepted that the replacement borrowing continued to fund the business and that the interest was deductible.
That position was highly relevant to landlords. A landlord might purchase or introduce a rental property using personal capital, operate the property as part of a property business and later refinance it. The former guidance recognised that withdrawing the capital originally committed to the business did not automatically convert the replacement borrowing into private borrowing merely because the proprietor subsequently used the withdrawn money personally.
The replacement wording
The revised BIM45700 now states:
“A proprietor of a business may withdraw the profits of the business and the capital they have introduced to the business, even though subsequent funding may then have to be provided by interest bearing loans. However, simply exchanging existing capital for loan finance does not on its own satisfy the wholly and exclusively test provided by S34. The interest payable on the loans is an allowable deduction where the borrowing is used for business expenditure or acquisition of assets used in the business.”
The first sentence continues to acknowledge that a proprietor may withdraw capital and replace it with borrowing. The sentences that follow appear to deprive that acknowledgement of much of its previous effect. HMRC now seems to require the replacement loan itself to be traced to fresh business expenditure or the acquisition of business assets.
The new Example 3 in BIM45690 makes the change even clearer. It describes a business proprietor who originally funded the acquisition of business assets from personal resources, later borrowed the same amount to facilitate the withdrawal of that capital and then used the money withdrawn for a private holiday. HMRC concludes that the interest is not deductible because the purpose of the borrowing was to facilitate a personal withdrawal.
That appears to be the opposite of the principle previously stated in BIM45700. Under the former guidance, the proprietor was entitled to withdraw capital previously introduced, even where substitute borrowing became necessary, subject to the capital account limitation. Under the revised guidance, the personal use of the money withdrawn appears capable of determining the tax treatment of the replacement borrowing.
This is not simply the removal of unnecessary arithmetic or the provision of clearer context. It appears to be a substantive change in HMRC’s interpretation of section 34 of the Income Tax (Trading and Other Income) Act 2005.
What changed in the law?
We would be grateful if HMRC would identify the legal development that prompted this change.
Has section 34 ITTOIA 2005 been amended in a way that changes the treatment of replacement borrowing? Has an Upper Tribunal, Court of Appeal or Supreme Court judgment established that the previous wording of BIM45700 was incorrect? Has another relevant authority emerged which HMRC considers requires the purpose of replacement borrowing to be determined principally by reference to the proprietor’s subsequent use of the capital withdrawn?
If there has been no relevant legislative amendment or binding judicial decision, the profession needs to understand why HMRC has replaced a longstanding published interpretation with a materially narrower one.
How does the new guidance reconcile with Scorer v Olin?
HMRC continues to quote the following passage from Scorer v Olin Energy Systems Ltd in BIM45665:
“The question whether interest was paid for the purposes of a trade must depend on whether the loan, on which the interest was paid, was itself incurred for the purposes of that trade. It does not necessarily follow that the purposes of the loan can be ascertained by looking at the immediate use to which the borrower applies the money.”
That passage appears particularly relevant to replacement borrowing. Where a proprietor originally provides capital to acquire or fund business assets, and an external lender subsequently replaces that funding, the immediate use of the cash released to the proprietor may not necessarily determine the purpose for which the replacement loan was incurred.
The new BIM45690 example nevertheless appears to reach its conclusion substantially because the proprietor used the withdrawn capital to pay for a private holiday. We would therefore be grateful if HMRC would explain how that example is reconciled with the passage from Scorer v Olin which remains within HMRC’s own guidance.
What does Silk v Fletcher establish?
The revised guidance places increased emphasis on Silk v Fletcher. That case involved an overdrawn capital account, drawings exceeding profits and evidential difficulty in demonstrating that all of the borrowing continued to fund the business.
The former BIM45700 guidance appeared to draw a practical distinction between withdrawing capital and accumulated profits properly standing to the proprietor’s credit, and withdrawing amounts that caused the capital account to become overdrawn. The revised BIM45705 now states that a capital account remaining in credit does not demonstrate that the interest is allowable, just as an overdrawn account does not by itself prove that the borrowing funded private expenditure.
We accept that a capital account balance cannot replace examination of the underlying facts. The more fundamental issue is whether Silk v Fletcher justifies abandoning the broader principle that a proprietor may replace capital genuinely introduced into a business with external borrowing.
The facts of Silk v Fletcher concerned drawings that exceeded profits and contributed capital. They were not simply a case of a proprietor withdrawing identifiable capital previously used to acquire or fund continuing business assets while an external lender replaced the proprietor as the source of finance.
We would therefore welcome HMRC’s explanation of why Silk v Fletcher is considered to support the revised treatment of straightforward replacement capital.
Is HMRC distinguishing between withdrawing capital and funding private expenditure?
There is an important commercial distinction between borrowing money to finance private expenditure and borrowing money to replace capital already committed to a business.
If a landlord increases borrowing by £100,000 and uses the money to purchase a private asset, without any corresponding capital previously introduced into the property business, the borrowing may plainly have a private purpose.
The position is different where the landlord originally invested £100,000 of personal capital to acquire or fund a rental property, and a lender subsequently advances £100,000 against that continuing business asset. Economically and commercially, the external lender has replaced the proprietor as the source of funding for the property business.
The fact that the proprietor is then free to use the returned capital personally does not necessarily establish that the lender funded the private expenditure. It may equally demonstrate that the lender replaced capital that the proprietor no longer needed to leave tied up in the business.
Does HMRC still recognise that distinction? If so, the revised examples do not make clear how it should be applied.
How will taxpayers who relied on the former guidance be treated?
For many years, landlords, business owners, accountants and tax advisers have relied upon the former wording of BIM45700 when considering refinancing and the withdrawal of capital.
HMRC’s manuals do not have the force of legislation, but taxpayers are entitled to expect significant changes in HMRC’s published interpretation to be explained clearly. Describing these amendments merely as providing clearer context does not alert readers to the possibility that HMRC may now challenge arrangements which its former guidance expressly appeared to accept.
We would therefore be grateful if HMRC would confirm whether the revised interpretation is intended to be applied to:
- borrowing entered into after 1 July 2026 only;
- interest arising after 1 July 2026 on borrowing already in existence;
- historic tax returns prepared in accordance with the former guidance; or
- all open periods, irrespective of the wording of HMRC’s guidance when the borrowing was arranged.
Taxpayers who made commercial decisions in good faith by reference to HMRC’s published guidance deserve clarity on this point.
Why was no technical explanation published?
The changes affect potentially large numbers of unincorporated businesses and landlords. They may alter the tax treatment of refinancing, the withdrawal of capital, succession planning, retirement funding and the replacement of proprietor finance with bank lending.
Despite that potential impact, HMRC’s update record does not identify any new legislation, judicial authority or policy paper supporting the change. Nor does it provide a comparison showing how the revised wording differs from the previous guidance.
We invite HMRC to publish a technical explanation setting out:
- the statutory and judicial basis for the revised interpretation;
- the reason the former BIM45700 wording was considered incorrect or incomplete;
- HMRC’s analysis of Scorer v Olin Energy Systems Ltd and Silk v Fletcher;
- the treatment of genuine replacement capital where the proprietor’s capital account remains in credit;
- the date from which HMRC intends the revised interpretation to apply; and
- HMRC’s approach to taxpayers who relied upon the former published guidance.
A request for clarity
HMRC is entitled to amend its manuals where it concludes that the existing guidance does not accurately reflect the law. Where a long-standing and widely relied-upon passage is replaced with wording that appears to produce a materially different outcome, transparency requires more than describing the amendment as clearer context.
This issue is not about whether interest should be deductible on borrowing genuinely used to finance private expenditure. It is about whether a proprietor remains entitled to withdraw capital previously introduced into a business while allowing external borrowing to replace that capital, and how the purpose of that borrowing should be determined.
The former BIM45700 guidance gave taxpayers and advisers a clear answer. The revised guidance appears to give a different one. We respectfully ask HMRC to explain what changed in the law.
Yours faithfully,
Mark Alexander
Founder of Property118.com
The post Open letter to HMRC: What changed in the law behind BIM45690 and BIM45700? appeared first on Property118.
View Full Article: Open letter to HMRC: What changed in the law behind BIM45690 and BIM45700?
Categories
- Landlords (19)
- Real Estate (9)
- Renewables & Green Issues (1)
- Rental Property Investment (1)
- Tenants (21)
- Uncategorized (12,940)
Archives
- September 2026 (23)
- August 2026 (61)
- July 2026 (63)
- June 2026 (70)
- May 2026 (70)
- April 2026 (78)
- March 2026 (72)
- February 2026 (55)
- January 2026 (52)
- December 2025 (62)
- August 2025 (51)
- July 2025 (51)
- June 2025 (49)
- May 2025 (50)
- April 2025 (48)
- March 2025 (54)
- February 2025 (51)
- January 2025 (52)
- December 2024 (55)
- November 2024 (64)
- October 2024 (82)
- September 2024 (69)
- August 2024 (55)
- July 2024 (64)
- June 2024 (54)
- May 2024 (73)
- April 2024 (59)
- March 2024 (49)
- February 2024 (57)
- January 2024 (58)
- December 2023 (56)
- November 2023 (59)
- October 2023 (67)
- September 2023 (136)
- August 2023 (131)
- July 2023 (129)
- June 2023 (128)
- May 2023 (140)
- April 2023 (121)
- March 2023 (168)
- February 2023 (155)
- January 2023 (152)
- December 2022 (136)
- November 2022 (158)
- October 2022 (146)
- September 2022 (148)
- August 2022 (169)
- July 2022 (124)
- June 2022 (124)
- May 2022 (130)
- April 2022 (116)
- March 2022 (155)
- February 2022 (124)
- January 2022 (120)
- December 2021 (117)
- November 2021 (139)
- October 2021 (130)
- September 2021 (138)
- August 2021 (110)
- July 2021 (110)
- June 2021 (60)
- May 2021 (127)
- April 2021 (122)
- March 2021 (156)
- February 2021 (154)
- January 2021 (133)
- December 2020 (126)
- November 2020 (159)
- October 2020 (169)
- September 2020 (181)
- August 2020 (147)
- July 2020 (172)
- June 2020 (158)
- May 2020 (177)
- April 2020 (188)
- March 2020 (234)
- February 2020 (212)
- January 2020 (164)
- December 2019 (107)
- November 2019 (131)
- October 2019 (145)
- September 2019 (123)
- August 2019 (112)
- July 2019 (93)
- June 2019 (82)
- May 2019 (94)
- April 2019 (88)
- March 2019 (78)
- February 2019 (77)
- January 2019 (71)
- December 2018 (37)
- November 2018 (85)
- October 2018 (108)
- September 2018 (110)
- August 2018 (135)
- July 2018 (140)
- June 2018 (118)
- May 2018 (113)
- April 2018 (64)
- March 2018 (96)
- February 2018 (82)
- January 2018 (92)
- December 2017 (62)
- November 2017 (100)
- October 2017 (105)
- September 2017 (97)
- August 2017 (101)
- July 2017 (104)
- June 2017 (155)
- May 2017 (135)
- April 2017 (113)
- March 2017 (138)
- February 2017 (150)
- January 2017 (127)
- December 2016 (90)
- November 2016 (135)
- October 2016 (149)
- September 2016 (135)
- August 2016 (48)
- July 2016 (52)
- June 2016 (54)
- May 2016 (52)
- April 2016 (24)
- October 2014 (8)
- April 2012 (2)
- December 2011 (2)
- November 2011 (10)
- October 2011 (9)
- September 2011 (9)
- August 2011 (3)
Calendar
Recent Posts
- Could a new LLP tax judgment help landlords caught in HMRC’s Spotlight 63?
- Why the nonsense £65 landlord database tax is just the start
- One million landlords set to use tenant deposit alternatives
- Why September could be the month to rethink your property portfolio
- Rents look set to rise as tenant demand grows – RICS
